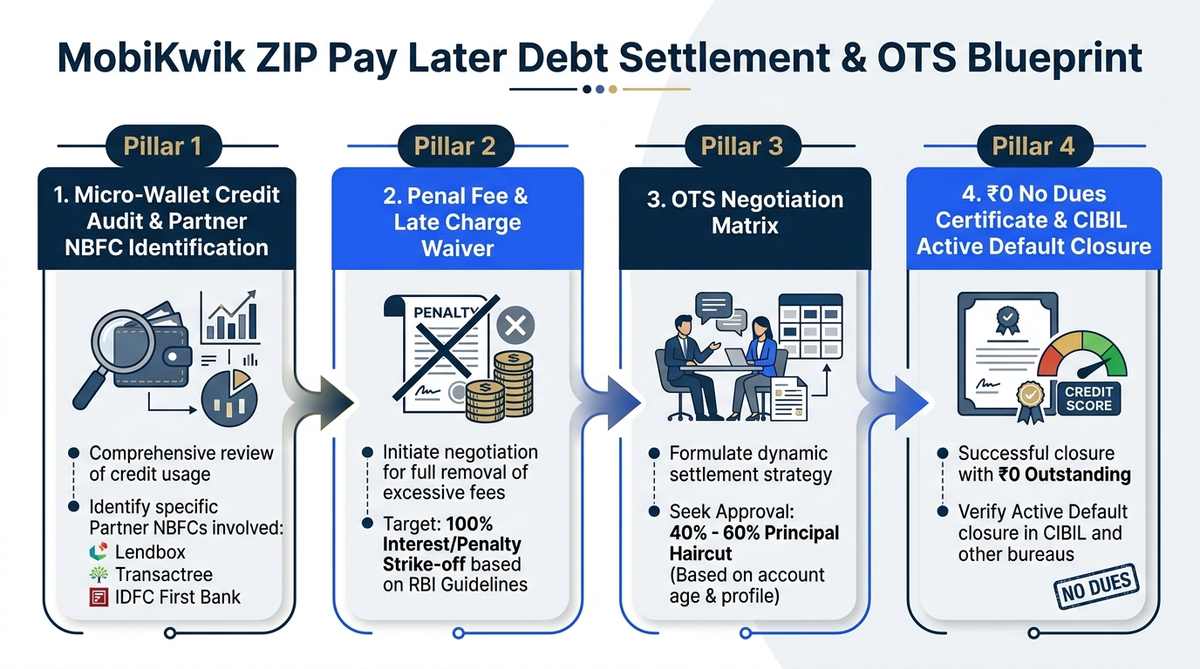
- Regulated NBFC Framework: MobiKwik ZIP is an unsecured credit line. RBI-regulated NBFCs back it. Defaulting is a civil matter under RBI compromise settlement rules.
- 100% Late Fee Elimination: Late fees and penal charges inflate balances. Formal OTS talks remove all penalty fees per RBI Fair Lending rules.
- Structured 40%–60% Principal Haircut: Loans overdue past 90 days allow lenders to approve deep principal discounts.
- Strict Anti-Harassment Protections. Calling your contacts or workplace violates RBI Digital Lending Guidelines and the DPDP Act 2023.
- Mandatory ₹0 NDC & CIBIL Resolution: Under RBI Circular RBI/2023-24/60, the NBFC must issue a No Dues Certificate within 30 days. This clears active defaults.
Understanding MobiKwik ZIP's Digital Lending Architecture
MobiKwik ZIP is a Buy Now Pay Later (BNPL) credit line. One MobiKwik Systems Limited runs it. It works like an unsecured personal loan. MobiKwik acts as a Digital Lending App (DLA) and Lending Service Provider (LSP). Partner NBFCs fund the loans. Partners include Transactree Technologies (Lendbox), Suryoday Small Finance Bank, and IDFC FIRST Bank.
Credit limits range from ₹10,000 to ₹60,000. The billing cycle lasts 15 days. If you face job loss or illness, you may miss a payment. The app then adds late fees of ₹250 to ₹1,000. It adds 36% to 48% penal interest. It also adds 18% GST. A ₹20,000 balance can grow past ₹38,000 in months.
The partner NBFC reports late payments to credit bureaus. These include CIBIL, Experian, Equifax, and CRIF High Mark. This default hurts your score. An unpaid loan is a civil dispute under the Indian Contract Act, 1872. Under RBI Master Directions, you have clear rights. You can stop harassment. You can waive unfair fees. You can settle via a One-Time Settlement (OTS).
MobiKwik ZIP Delinquency Lifecycle
Under RBI IRACP norms and Ind AS 109 rules, NBFCs track overdue ZIP loans by Days Past Due (DPD). Knowing these stages helps you time your settlement talks for top principal discounts.
In the first 60 days (SMA-0 and SMA-1), collection callers push for full pay. At 91 DPD, the NBFC marks the loan as an NPA. The lender must set aside capital reserves for the bad debt. To recover money, lenders shift focus toward One-Time Settlements.
| Delinquency Stage. | Overdue Days (DPD). | NBFC & App Recovery Actions. | Bureau & Legal Status. | Settlement Haircut Potential. |
|---|---|---|---|---|
| SMA-0 (Grace Period) | 1 – 30 Days. | Automated WhatsApp alerts, app notices, and UPI autopay debit attempts. | Initial overdue tag in bureau feeds. Minor credit score drop. | Negligible. App demands total bill payment plus late fee. |
| SMA-1 (Early Delinquency) | 31 – 60 Days. | Calls from recovery agents, daily reminders, and growing penal charges. | Credit score drops 40 to 80 points. Account marked irregular. | Low. Waiver of recent late fees only upon full principal pay. |
| SMA-2 (Pre-NPA Stress) | 61 – 90 Days. | Frequent collection calls, demand emails, and suspended credit line. | Severe CIBIL drop. Lender prepares formal demand notices. | Moderate. Full late fee waiver with small principal discount. |
| NPA (Substandard Asset) | 91 – 180 Days. | Moved to NBFC Stressed Assets Desk. Ind AS 109 provisions set. | Marked as active default. Pre-litigation notices issued. | High. 35%–50% Principal Haircut + 100% Fee Waiver. |
| Doubtful / Loss Asset | 181 – 365+ Days. | Full loss provisioned. Loan written off on NBFC balance sheet. | National Lok Adalat referrals and legal summons. | Maximum. 50%–60% Principal Haircut + Full Fee Strike-off. |
After 180 days, the NBFC writes off the defaulted loan on its books. Any recovery from an OTS brings fresh cash to the lender. This gives credit teams room to approve large principal discounts.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
How to Eliminate Predatory Late Fees
Late fees make defaulted BNPL balances grow fast. Under RBI Fair Lending Directives (Circular RBI/2023-24/53), lenders cannot add penal charges to principal. Penal charges must stay fair and reasonable.
Automated UPI autopay and e-NACH runs can trigger bounce fees of ₹250 to ₹500. Under NPCI and RBI rules, you have the right to pause or cancel e-mandates in your UPI or banking app. This stops extra return charges.
During OTS talks, our legal team seeks a 100% waiver of late fees, penal interest, and processing charges. We focus talks only on the original borrowed amount.
MobiKwik ZIP One-Time Settlement (OTS) Policies
Under RBI Master Directions (DOR.STR.REC.20/21.04.048/2023-24), NBFCs settle micro-loans through NPV recovery. Litigation costs on small loans are too high for lenders.
When you share a hardship file, the NBFC committee evaluates your case. They prefer guaranteed upfront cash over slow, uncertain collection steps.
Where C_t is expected recovery and r is the discount rate. Deductions account for legal costs and provisioning burden.
Realistic MobiKwik ZIP Settlement Haircut Slabs
| Partner NBFC | Delinquency Aging | Fee Waiver | Principal Haircut. | Target Offer. |
|---|---|---|---|---|
| Lendbox | 90 – 180 Days (NPA). | 100% Waiver. | 35% – 45% Waiver. | Offer 40%–50% of Principal. |
| Lendbox | 181+ Days (Written Off). | 100% Waiver. | 50% – 60% Waiver. | Offer 30%–40% of Principal. |
| Suryoday SFB | 90 – 180 Days (NPA). | 100% Waiver. | 30% – 40% Waiver. | Offer 45%–55% of Principal. |
| IDFC FIRST | 180+ Days (Doubtful). | 100% Waiver. | 45% – 60% Waiver. | Offer 35%–45% of Principal. |
MobiKwik ZIP Pay Later Debt Settlement & OTS Blueprint
Defending Against Aggressive Collection Tactics, WhatsApp
Defaulted accounts often go to third-party collection agencies. Some agents make non-stop calls. Some send fake WhatsApp notices. Others contact your family and coworkers.
Under RBI Digital Lending Guidelines (2022), agents cannot access your contacts. They cannot call third parties. Calls are only allowed from 8:00 AM to 7:00 PM. Sharing debt data also violates the DPDP Act, 2023.
If you face harassment, save call logs and chat records. Send a cease-and-desist notice to the NBFC Nodal Officer. You can also complain to the RBI Integrated Ombudsman (CMS).
Step-by-Step MobiKwik ZIP Settlement Roadmap
Follow these six simple steps to settle your MobiKwik ZIP account safely:
1Credit Report Audit & Partner NBFC Identification
Check your CIBIL and Experian reports. Find the underwriting NBFC. Note down the exact borrowed amount and overdue days.
2Revoking Digital Mandates & Centralizing Communications
Cancel UPI autopay and e-mandates in your banking app. This stops bounce fees. Ask the lender in writing to use only email.
3Compiling Hardship Dossier & Submitting Formal OTS Proposal
Collect proof of hardship, such as medical bills or job loss letters. Submit a compromise proposal under RBI Master Directions. Propose 25% to 35% of principal.
4Managing Counter-Demands & Eliminating Late Charges
Reject unfair counter-demands by citing RBI Fair Lending norms. Demand a 100% waiver of late fees. Negotiate a 40% to 60% principal discount.
5Forensic Verification of the OTS Sanction Letter
Check that the settlement letter is on official NBFC letterhead. Verify the loan number and terms before paying anything.
6Official Account Remittance & Securing the ₹0 No Dues Certificate
Pay the settlement directly to the official NBFC loan account using NEFT or RTGS. Under RBI Circular RBI/2023-24/60, obtain your No Dues Certificate within 30 days.
Navigating MobiKwik Sec 25 PSSA Demands & Lok Adalat
Borrowers may get demand notices under Section 25 of the Payment and Settlement Systems Act, 2007 (PSSA) for failed mandates. These are legal notices meant for conciliation.
A legal reply explaining your hardship helps start formal settlement talks. NBFCs also refer cases to National Lok Adalat. Lok Adalat settlements (40% to 60% waivers) become a binding Civil Court Decree.
| Resolution Channel | Governing Framework | Typical Haircut. | Resolution Speed | Legal Finality |
|---|---|---|---|---|
| Direct NBFC OTS | RBI Master Direction (2023). | 40% – 60% Haircut | 15-30 Days | Binding contract, ₹0 NDC. |
| National Lok Adalat | Legal Services Act, 1987. | 45% – 60% Haircut | Single-day | Civil Court Decree. |
| Sec 25 PSSA Defense | Payment Systems Act. | 35% – 50% Haircut | 1-3 Months | Settled, case withdrawal. |
| Digital Notice Reply | Advocate response. | 100% Fee Waiver | 7-14 Days | Halts collection. |
Forensic Verification of NBFC Settlement Letters
Never pay money to personal UPI accounts. Always ask for an official sanction letter from the lending NBFC. It must show company details, loan account numbers, settlement amounts, and full debt release terms.
Under RBI Circular RBI/2023-24/60, lenders must issue a No Dues Certificate and update credit bureaus within 30 days. If the lender delays, they must pay ₹5,000 per day in compensation.
MobiKwik ZIP Post-Settlement CIBIL Score Trajectory
Settling a MobiKwik ZIP loan updates your credit report to 'Settled' with a balance of ₹0. This stops monthly overdue flags and prevents further score drops.
After a 12-month cooling period, you can rebuild your credit score above 750 within 18 to 24 months. Use a secured FD credit card. Keep usage under 25%. Pay every bill on time.
Why Distressed MobiKwik ZIP Borrowers Trust SettleLoans
SettleLoans stops recovery calls with legal cease-and-desist notices. We remove 100% of unfair late fees under RBI rules. Our team negotiates 40% to 60% principal waivers and secures verified ₹0 No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: MobiKwik ZIP Pay Later Settlement
Can I legally settle a defaulted MobiKwik ZIP Pay Later credit line?
Yes. Regulated NBFCs fund MobiKwik ZIP credit lines. These include Transactree Technologies (Lendbox), Suryoday Small Finance Bank, and IDFC FIRST Bank. Under RBI Master Directions on Compromise Settlements (2023), borrowers have the legal right to settle. You can negotiate a One-Time Settlement (OTS) if you face financial hardship.
Why does a small MobiKwik ZIP balance of ₹15,000 balloon to ₹35,000+ so rapidly?
Missed due dates trigger monthly late fees and high penal interest of 36% to 48%. Extra GST gets added as well. Over a few months, these fees exceed the principal. Under RBI Fair Lending Practice norms, you can ask for a 100% waiver of these penal charges during settlement.
Which entity actually reports my MobiKwik ZIP default to CIBIL and credit bureaus?
MobiKwik is a digital lending app. The partner NBFC funds the loan and reports defaults to CIBIL, Experian, Equifax, and CRIF High Mark. Lenders like Lendbox or Suryoday SFB report your overdue DPD as an active default.
How can I stop recovery agent calls to my family, friends, and workplace for MobiKwik ZIP?
Under RBI Digital Lending Guidelines, agents cannot call your contacts, family, or employer. Such calls are illegal. You can send a legal cease-and-desist notice to stop them. You can also file a complaint on the RBI Integrated Ombudsman portal (CMS).
What percentage of discount or waiver can be negotiated on a MobiKwik ZIP default?
In a formal OTS, lenders waive 100% of late fees, penal interest, and GST. On the principal loan amount, borrowers usually get a 40% to 60% discount. The exact waiver depends on the delay and default age.
Can MobiKwik or its NBFC file a criminal police FIR or arrest me for non-payment?
No. An unpaid digital loan is a civil contract matter under the Indian Contract Act, 1872. The police cannot register an FIR or make arrests for unpaid loan dues. Threats of police action from recovery agents are illegal scare tactics.
How do I ensure the settlement offer is authentic and avoid fake settlement fraud?
Never pay money to personal UPI IDs or agent accounts. A valid OTS must have an official sanction letter. It must come on the letterhead of the lending NBFC. It must show your loan account number, settlement amount, and full debt release terms.
What happens to my CIBIL report after settling the MobiKwik ZIP account?
After you pay the settlement amount, the NBFC marks the account as 'Settled' with ₹0 balance. This stops further negative remarks. It also stops legal action and lets you rebuild your CIBIL score back to 750+ over 18 to 24 months.
How long does it take to receive the No Dues Certificate (NDC) from the partner NBFC?
Under RBI Circular RBI/2023-24/60, lenders must issue a No Dues Certificate within 30 days of settlement. They must also update credit bureaus in this time. If they delay past 30 days, they must pay ₹5,000 per day in compensation.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Guidelines on Digital Lending (DOR.CRE.REC.66/21.07.001/2022-23)
- RBI Master Direction: Compromise Settlements (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Fair Lending: Penal Charges & Prohibition of Compounding (RBI/2023-24/53)
- Reserve Bank: Integrated Ombudsman Scheme, 2021
- NALSA: Legal Services Authorities Act, 1987 — National Lok Adalat Framework