- Statutory Compromise Rights: Defaulting on a KreditBee app loan is strictly a civil contractual dispute. Under RBI Master Directions on Compromise Settlements, borrowers experiencing financial distress hold clear statutory rights to negotiate an authorized One-Time Settlement (OTS).
- Halting WhatsApp & Bot Harassment: Under RBI Digital Lending Directions (2022) and Fair Practices Codes, recovery agents are prohibited from contacting third-party contacts, sending threatening WhatsApp messages, or calling outside the 08:00 AM to 07:00 PM window.
- Stopping NACH Return Penalties: Cancelling electronic NACH auto-debit mandates under NPCI circulars halts recurring bank penalty fees. Legal representation demands 100% complete waiver of all accumulated bounce charges during settlement.
- Realistic 40%–65% Haircut: Once an account crosses 90+ Days Past Due (NPA classification), Krazybee Services assesses Net Present Value (NPV) recovery economics, unlocking substantial principal debt waivers.
- Mandatory ₹0 NDC Guarantee: Under RBI Circular RBI/2023-24/60, Krazybee Services must issue a formal No Dues Certificate and update credit bureaus within 30 days of settlement payment, subject to a ₹5,000/day statutory delay penalty.
KreditBee & Krazybee Services Framework
KreditBee has established itself as one of India's fastest-growing digital lending platforms, operated by Finnov Private Limited. The mobile application delivers instant personal loans, salaried credit lines, and short-term merchant financing ranging from ₹5,000 to ₹5,00,000 with rapid paperless disbursement. However, behind the consumer-facing mobile interface lies a regulated non-banking financial infrastructure primarily driven by Krazybee Services Private Limited, a Systemically Important Non-Deposit Taking Non-Banking Financial Company (NBFC-ND-SI) registered with the Reserve Bank of India under Section 45-IA of the RBI Act, 1934.
In addition to its proprietary NBFC book, KreditBee frequently operates through co-lending partnerships and digital lending arrangements with institutional lenders, including InCred Financial Services Limited, Vivriti Capital Limited, Northern Arc Capital Limited, MAS Financial Services, and Western Capital Advisors. When a borrower signs the digital loan agreement via electronic Aadhaar OTP, the underlying creditor is almost invariably Krazybee Services or one of its regulated institutional co-lending partners.
Retail digital loans are characterized by steep Annual Percentage Rates (ranging between 24% and 36% per annum), high upfront processing deductions, and short amortisation tenures of 3 to 24 months. When an unexpected economic disruption strikes—such as sudden employment termination, medical emergencies, small business turnover contraction, or severe cost-of-living shocks—borrowers frequently find it impossible to sustain monthly equated installments. Within days of non-payment, automated clearing systems trigger aggressive penalty compounding, causing a modest ₹1,00,000 loan to quickly inflate into an unmanageable ledger balance.
Crucially, under Indian jurisprudence and the Indian Contract Act, 1872, default on an unsecured digital personal loan is strictly a civil breach of contract. Borrowers are protected by comprehensive Reserve Bank of India statutory frameworks governing digital lenders and recovery practices, establishing enforceable legal rights to demand an audit of predatory penalty fees and negotiate a structured compromise One-Time Settlement (OTS).
KreditBee Delinquency Stages: From DPD 1–30 to Non-Performing Asset (NPA)
Under the Reserve Bank of India's Prudential Norms on Income Recognition, Asset Classification and Provisioning (IRACP) and Expected Credit Loss (ECL) frameworks under Indian Accounting Standard 109 (Ind AS 109), Krazybee Services systematically tracks digital loan defaults across structured Days Past Due (DPD) aging buckets. Understanding these institutional milestones is crucial for strategically timing settlement negotiations and securing the maximum principal debt haircut.
In the early delinquency phases (Buckets 1 and 2), KreditBee relies heavily on automated digital reminders and tele-calling bots. However, once an account crosses the pivotal 90-day threshold without payment, the asset is formally reclassified as a Non-Performing Asset (NPA). At this stage, Krazybee is required to lock regulatory capital into mandatory balance-sheet provisioning, shifting its institutional focus from standard installment recovery toward bad-debt recovery and compromise resolution.
| Delinquency Stage | Overdue Days (DPD) | KreditBee & Krazybee Recovery Actions | Legal & Judicial Exposure | Settlement Haircut Potential |
|---|---|---|---|---|
| SMA-0 (Early Delinquency) | 1 – 30 Days | Automated IVR calls, daily SMS/email alerts, repeated NACH mandate presentations. | Zero legal risk; initial bureau DPD tracking begins. | Negligible (NBFC demands full overdue installment payment). |
| SMA-1 (Mid Delinquency) | 31 – 60 Days | Intensive tele-calling, third-party recovery agency allocation, WhatsApp warning notices. | Statutory loan acceleration notices; sharp CIBIL score drop. | Low (Tenure extensions or partial interest waivers discussed). |
| SMA-2 (Pre-NPA Escalation) | 61 – 90 Days | Outsourced agency field collection warnings, formal loan recall demand letters. | Section 25 PSSA / Section 138 NI Act statutory legal demand notices. | Moderate (Discussions for complete penal fee waivers can commence). |
| NPA (Substandard Asset) | 91 – 180 Days | Transferred to Krazybee Stressed Assets Division; mandatory 15%–25% provisioning. | Magistrate Court summons under Sec 25 PSSA; Lok Adalat conciliation notices. | High (35%–50% Haircut achievable). |
| Doubtful / Write-Off Asset | 181+ Days | Technical write-off under Ind AS 109; assigned to specialized bad-debt recovery desks. | Civil summary recovery suits or permanent Lok Adalat compromise awards. | Maximum (50%–65% Haircut achievable). |
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Halting Automated Calling Bots, WhatsApp Intimidation & NACH Bounce Charges
One of the most distressing aspects of defaulting on a digital app loan like KreditBee is the sheer volume of automated recovery pressure. KreditBee utilizes high-frequency predictive dialers and AI calling bots that dial borrowers 20 to 50 times a day from constantly rotating virtual phone numbers. In parallel, outsourced debt recovery agencies frequently deploy aggressive WhatsApp messaging tactics, sending fabricated legal notices, threatening to call references or workplace managers, and making unauthorized field visits.
These aggressive collection practices are flagrant violations of the Reserve Bank of India's Digital Lending Guidelines (September 2022) and the RBI Master Circular on Fair Practices Code for NBFCs. Under these binding statutory regulations:
- Lenders and their agents are strictly prohibited from accessing, storing, or scraping a borrower's phone contact list, media files, or social media accounts.
- Contacting friends, relatives, colleagues, or employers who are not formal co-borrowers or legal guarantors is an unlawful invasion of privacy.
- Telephonic collection calls and home visits are strictly confined to the statutory window of 08:00 AM to 07:00 PM. Calling outside these hours, on public holidays, or late at night constitutes regulatory misconduct.
- Harassment, intimidating voice tones, abusive vernacular language, public humiliation, or false threats of criminal arrest are strictly actionable under civil and criminal law.
Concurrently, KreditBee's automated treasury systems often present electronic National Automated Clearing House (NACH) mandates multiple times in a single billing cycle. Each failed auto-debit attempt results in the destination bank debiting between ₹250 and ₹590 in return charges, while Krazybee levies separate internal bounce fees. This dual penalty mechanism rapidly drains borrower savings accounts without reducing a single rupee of core principal debt.
Distressed borrowers can permanently halt this drain by exercising their statutory rights under National Payments Corporation of India (NPCI) circulars to cancel or revoke the e-NACH mandate through their home bank branch or mobile banking portal. Furthermore, under the RBI Fair Lending Practices circular on Penal Charges in Loan Accounts (2023/2024), lenders are prohibited from compounding penal charges or capitalizing them into principal dues. During One-Time Settlement negotiations, legal representation ensures 100% of accumulated bounce penalties and late charges are completely expunged.
Krazybee Services OTS Haircut Dynamics & The Net Present Value (NPV) Formula
When an unsecured digital personal loan defaults, Krazybee Services evaluates whether to pursue formal legal litigation or accept a discounted compromise One-Time Settlement (OTS). Under the Reserve Bank of India's Master Directions on Compromise Settlements and Technical Write-offs, NBFC credit committees are required to base settlement approvals on a rigorous financial comparison: the Net Present Value (NPV) of Estimated Recovery through civil litigation versus the immediate cash realization of an OTS offer.
Civil recovery suits in Indian courts entail substantial legal advocacy retainer fees, court filing fees, process serving expenses, and typical procedural delays spanning 3 to 5 years. For an unsecured loan with zero mortgage collateral, the legal recovery yield is exceptionally low. Consequently, an upfront lump-sum OTS payment provides the NBFC with immediate capital relief, allows regulatory provision write-backs, and eliminates non-performing asset drag.
Where C_t represents estimated future cash recoveries over time, r is the NBFC hurdle discount rate, and significant deductions account for 3–5 years of civil court litigation friction, advocate fees, and capital locked in non-accrual NPA balance-sheet provisioning.
Based on this financial calculus, Krazybee Services Credit Committees establish internal settlement discount matrices. While initial collection calls may only offer token 10% to 15% interest discounts, seasoned legal advocates presenting a verifiable hardship dossier can systematically achieve 40% to 65% principal haircuts alongside 100% cancellation of all penal interest and bounce penalties.
Visual Blueprint: KreditBee Loan Settlement & Legal Shield
Step-by-step roadmap from automated bot harassment defense to ₹0 No Dues Certificate
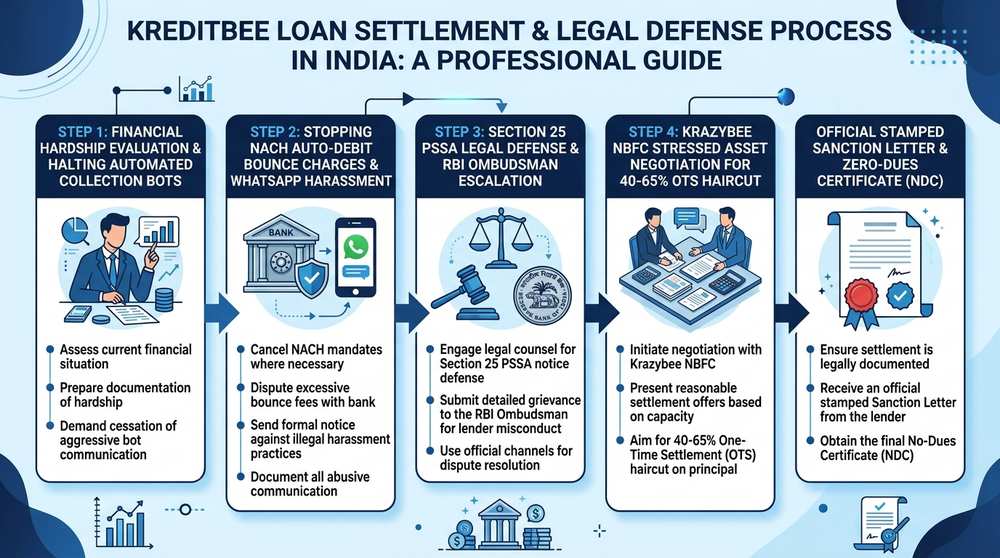
Statutory Borrower Rights Under RBI Digital Lending & Debt Recovery Regulations
Borrowers struggling with digital personal loan defaults frequently endure unlawful intimidation because they are unaware of the strict statutory protections enacted by Indian regulatory authorities and higher courts. Under the Reserve Bank of India Master Directions on Recovery Agents and NBFC Fair Practices Code:
1. Strict Prohibition of Third-Party Communication: Recovery agents have zero legal authority to contact your family members, parents, spouse, friends, neighbors, or workplace colleagues. The loan agreement is an individual civil contract between the borrower and Krazybee Services. Disclosing debt details to third parties is a direct violation of constitutional privacy rights affirmed by the Supreme Court in Justice K.S. Puttaswamy (Retd.) v. Union of India.
2. Criminality of Fake Police Notices & Arrest Threats: Outsourced collection tele-callers frequently forge court summons, fake police FIR drafts, or fabricated CBI / cybercrime arrest warrants and transmit them over WhatsApp to induce panic. In India, default on an unsecured personal loan is strictly a civil matter. Impersonating public servants and fabricating judicial documents are severe cognizable criminal offenses under the Bharatiya Nyaya Sanhita (BNS) and Section 66D of the Information Technology Act, 2000.
3. Regulatory Escalation Mechanisms: When recovery personnel violate RBI conduct norms, borrowers should preserve call recordings, screenshots of WhatsApp messages, and agent phone numbers. A formal complaint must be lodged with Krazybee's Principal Nodal Officer (PNO). If the grievance is unresolved within 30 days, it can be escalated to the RBI Integrated Ombudsman Scheme (cms.rbi.org.in), which regularly imposes severe compliance penalties on non-compliant NBFCs.
Step-by-Step Guide: How to Negotiate an Official OTS with KreditBee & Krazybee
Securing a legally binding, heavily discounted One-Time Settlement with Krazybee Services requires a disciplined, evidence-based strategy that bypasses junior tele-callers and directly engages decision-making credit authorities:
1Comprehensive Financial Hardship Dossier Compilation
Compile verifiable documentary evidence demonstrating that your loan default is non-wilful and caused by genuine involuntary hardship. Relevant documents include formal job termination or salary reduction letters, medical hospitalization discharge summaries, bank statements showing depleted liquidity, or business income tax filings evidencing revenue loss.
2Cancelling NACH Auto-Debits & Formalizing Written Channels
Instruct your bank to cancel the electronic NACH mandate to stop recurring return penalties. Serve a formal written notice to KreditBee and Krazybee Services directing that all debt communication be conducted exclusively via registered email or through your appointed legal counsel, establishing a clean evidentiary audit trail.
3Submitting Formal Hardship Petition to Stressed Assets Committee
Submit a formal compromise proposal addressed to Krazybee Services' Stressed Assets Division citing the RBI Master Direction on Compromise Settlements. Propose an initial settlement figure at 25% to 35% of core principal dues to establish an advantageous baseline for structured counter-negotiation.
4Managing Counter-Demands & Securing Maximum Haircut
Krazybee recovery desks will initially reject low opening offers and suggest minor interest concessions. Experienced debt settlement advocates counter these demands by establishing that settlement funds are being borrowed from third-party family members as a final one-time relief, successfully steering the approval toward the target 40% to 65% principal haircut band.
5Rigorous Forensic Audit of the OTS Sanction Letter
Before paying any funds, conduct a rigorous audit of the One-Time Settlement sanction letter. Verify that it is issued on official Krazybee Services Private Limited letterhead, contains the loan account number, sanctioned settlement sum, exact payment deadlines, and unambiguous covenants confirming complete debt extinguishment.
6Official Channel Payment & Enforcing ₹0 NDC Delivery
Remit the agreed settlement amount exclusively into the designated Krazybee loan account through official banking channels (NEFT/RTGS or in-app payment gateway). Under RBI Circular RBI/2023-24/60, the NBFC is statutorily required to deliver your stamped No Dues Certificate and update credit bureau records within 30 calendar days.
Navigating Section 25 PSSA Legal Notices & National Lok Adalat Settlements
When a KreditBee digital personal loan default crosses 60 to 90 days, Krazybee Services or its legal counsel will often dispatch a statutory demand notice under Section 25 of the Payment and Settlement Systems Act, 2007 (PSSA) or Section 138 of the Negotiable Instruments Act, 1881, arising from bounced electronic NACH mandates.
A Section 25 PSSA notice is a statutory precursor to a private complaint before a Judicial Magistrate Court; it is not an immediate arrest warrant or civil decree. Borrowers must never ignore this statutory notice. Serving a formal legal reply drafted by experienced debt defense advocates within the mandatory 15-day window establishes bona fide financial distress, challenges unauthorized repeated mandate presentations, and opens formal channels for a compromise OTS, which routinely halts criminal court litigation.
Furthermore, Krazybee Services regularly lists non-performing digital retail loan portfolios before quarterly National Lok Adalats organized by District Legal Services Authorities (DLSA) under the Legal Services Authorities Act, 1987. National Lok Adalat provides an exceptional judicial conciliation platform where NBFC nodal officers carry pre-authorized settlement mandates offering substantial debt waivers (often 45% to 65% haircuts). The resultant Lok Adalat settlement award possesses the legal status of a binding, non-appealable Civil Court Decree that permanently dismisses all pending legal claims.
| Resolution Avenue | Legal Mechanism | Haircut Potential | Typical Timeline | Judicial Finality |
|---|---|---|---|---|
| Direct NBFC Compromise OTS | Private settlement contract under RBI Master Directions. | 40% – 65% Principal Haircut | 15 to 30 Days | Binding contractual release with ₹0 NDC. |
| National Lok Adalat | Judicial conciliation before sitting judge and DLSA panel. | 45% – 65% Principal Haircut | Single-day hearing session | Civil Court Decree (Non-appealable finality). |
| Section 25 PSSA Defense | Formal advocate reply & compoundable conciliation. | 35% – 55% Principal Haircut | 1 to 3 Months | Magistrate complaint permanently withdrawn. |
| RBI Ombudsman Escalation | Regulatory complaint for Fair Practices violations. | Variable (Fee waiver + OTS) | 30 to 60 Days | Statutory directive issued to NBFC. |
Authenticating KreditBee OTS Sanction Letters & Enforcing the ₹0 NDC Mandate
In the fintech recovery space, fraudulent collection scams represent a major hazard for distressed borrowers. Rogue third-party collection agents often issue fake settlement discount letters over WhatsApp or demand cash/UPI transfers to personal bank accounts, falsely promising loan closure. If a borrower makes an unverified payment, Krazybee credits the funds against accumulated penal charges, leaving the default open and compounding.
To guarantee absolute legal validity, every settlement letter must undergo rigorous forensic verification. The OTS sanction letter must be issued directly on official Krazybee Services Private Limited letterhead (CIN: U65100KA2016PTC086990), featuring registered office details in Bengaluru, a unique proposal reference ID, the borrower's name and loan account number, sanctioned settlement amount, exact payment due dates, and an explicit covenant confirming that upon full payment, the loan balance becomes exactly ₹0 with all legal proceedings withdrawn.
Under Reserve Bank of India Circular RBI/2023-24/60 (Responsible Lending Conduct – Release of Movable/Immovable Property Documents on Repayment/Settlement of Personal Loans), Krazybee Services is statutorily mandated to deliver the official stamped No Dues Certificate (NDC) and update all four credit information companies (CIBIL, Experian, Equifax, CRIF High Mark) within 30 calendar days of receiving full settlement payment. If the lender fails to deliver the NDC within 30 days without lawful justification, it is statutorily liable to pay compensation of ₹5,000 per day of delay directly to the borrower.
CIBIL Score Trajectory Post-Settlement & Strategic Credit Rehabilitation
Executing a One-Time Settlement with KreditBee results in Krazybee Services reporting the loan account status to credit information companies (TransUnion CIBIL, Experian, Equifax, and CRIF High Mark) as 'Settled' or 'Post-Write-off Settled' with an outstanding balance of exactly ₹0. This creates an initial credit score drop of approximately 70 to 120 points.
Under RBI compromise directives, a mandatory 12 to 24-month cooling-off period applies before mainstream commercial banks approve fresh unsecured credit cards or personal loans. However, a 'Settled' record with a zero balance is infinitely superior to an open, compounding 'Default' status, which continues to degrade your credit score every single month and leaves you vulnerable to legal action.
Borrowers can systematically restore their credit score above 750+ within 18 to 24 months by adopting a disciplined rehabilitation roadmap: (1) Open a fixed-deposit-backed secured credit card (FD card) with a modest deposit of ₹20,000 to ₹50,000; (2) Maintain credit utilization strictly below 25% of the sanctioned credit limit; (3) Ensure 100% on-time payment records on utility bills, mobile post-paid accounts, and surviving financial obligations; (4) Perform quarterly credit report audits to verify that the KreditBee balance is reflected as ₹0 with zero active delinquency flags.
Why Distressed KreditBee Borrowers Trust SettleLoans
Resolving defaulted digital app loans requires strong legal defense against predatory collection practices and deep expertise in NBFC debt restructuring. SettleLoans shields borrowers by issuing formal cease-and-desist notices to stop abusive recovery calls and WhatsApp harassment, revokes unauthorized electronic NACH mandates, replies to Section 25 PSSA legal notices, and negotiates directly with Krazybee Services Stressed Asset Desks to achieve 40% to 65% debt waivers with 100% authentic No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
Frequently Asked Questions About KreditBee Loan Settlement
What is the KreditBee loan settlement process and how does an app loan OTS work?
The KreditBee loan settlement process is a legally binding compromise resolution executed between a distressed borrower and Krazybee Services Private Limited (or its registered co-lending NBFC/bank partners like InCred, Vivriti, or Northern Arc). When an unsecured digital personal loan crosses 90 days of continuous delinquency (entering Non-Performing Asset or NPA classification), automated tele-calling algorithms give way to the Stressed Assets Division. The borrower submits a verified hardship petition evidencing involuntary insolvency (job loss, business closure, or severe illness). Upon review of recovery Net Present Value (NPV), Krazybee issues a formal stamped One-Time Settlement (OTS) sanction letter granting a 40% to 65% principal haircut and 100% waiver of accrued penal interest and bounce fees, concluding with a ₹0 No Dues Certificate.
Is KreditBee a legitimate RBI-registered entity or an illegal Chinese 7-day loan app?
KreditBee is a fully legitimate, Reserve Bank of India-regulated digital lending platform operated by Finnov Private Limited. All loans disbursed through the KreditBee app are underwritten and funded by Krazybee Services Private Limited—a Systemically Important Non-Deposit Taking Non-Banking Financial Company (NBFC-ND-SI) registered with the RBI—alongside institutional co-lending partners like InCred, Vivriti Capital, Northern Arc, and MAS Financial. Unlike illegal 7-day APK scam apps, KreditBee is strictly bound by RBI Digital Lending Directions, the RBI Fair Practices Code, and statutory credit bureau reporting to CIBIL and Experian.
How can borrowers stop continuous automated IVR calls, WhatsApp threats, and reference harassment from KreditBee?
Under the RBI Master Directions on Recovery Agents (2022) and the Digital Lending Guidelines, KreditBee and its outsourced recovery agencies are prohibited from contacting individuals not named as co-borrowers, scraping contact lists, sending abusive WhatsApp threats, or placing calls outside the 08:00 AM to 07:00 PM statutory window. Borrowers can stop unlawful harassment by issuing a formal legal cease-and-desist notice to Krazybee's Principal Nodal Officer, revoking smartphone app data permissions, and escalating documented violations to the RBI Integrated Ombudsman portal at cms.rbi.org.in.
How do you stop recurring KreditBee NACH auto-debit bounce fees and bank return penalties?
When a digital loan defaults, KreditBee's automated clearing systems frequently represent the electronic NACH mandate multiple times per billing cycle, causing destination banks to debit ₹250 to ₹590 in return charges each time. Borrowers can stop this financial drain by submitting a written mandate cancellation request to their home bank under NPCI e-Mandate circulars, while simultaneously serving a written notice to Krazybee Services requesting an immediate suspension of electronic presentation pending OTS restructuring.
Can KreditBee file a police FIR, send real police officers, or have you arrested for loan default?
No. Under Indian civil jurisprudence and the Indian Contract Act, 1872, default on an unsecured digital personal loan is purely a civil breach of contract. Police officers have zero statutory authority to intervene in loan recovery or act on behalf of NBFCs. Any collection agent who impersonates police personnel, sends fabricated arrest warrants or FIR drafts on WhatsApp, or threatens criminal imprisonment is committing severe cognizable offenses under the Bharatiya Nyaya Sanhita (BNS) and the Information Technology Act, 2000.
What percentage of debt waiver or haircut can you negotiate on a defaulted KreditBee loan?
Once a KreditBee loan reaches 90 to 180+ Days Past Due (DPD) and transitions into Substandard, Doubtful, or Loss NPA status under Ind AS 109, borrowers with documented financial hardship can realistically negotiate a 40% to 65% principal haircut. Additionally, 100% of accumulated penal interest, overdue processing surcharges, and NACH bounce fees are completely cancelled under RBI-compliant compromise settlement policies.
What is a Section 25 PSSA legal notice from KreditBee and how should you respond?
A Section 25 PSSA notice is a statutory 15-day demand notice issued under the Payment and Settlement Systems Act, 2007, when an electronic NACH debit instruction dishonours due to insufficient funds. It is not an arrest warrant or court decree. Distressed borrowers must engage legal counsel to serve a formal written reply within the 15-day statutory timeline, citing bona fide financial distress, challenging predatory penalty compounding, and opening formal channels for a compromise OTS resolution.
Can Krazybee Services freeze or seize money from your other bank accounts under Section 171 Banker's Lien?
No. Under Section 171 of the Indian Contract Act, 1872, the right of general lien is strictly restricted to scheduled commercial banks holding deposits under the exact same Customer ID. Because Krazybee Services is a non-deposit-taking NBFC, it has no legal power to attach, freeze, or debit savings accounts maintained in third-party banks (such as SBI, HDFC, ICICI, or Axis Bank) without obtaining a formal execution decree from a competent Civil Court.
What is the statutory deadline for KreditBee to deliver the No Dues Certificate (NDC)?
Under RBI Circular RBI/2023-24/60, Krazybee Services and its co-lending partners are legally mandated to deliver a stamped No Dues Certificate (NDC) and update all four credit information companies (CIBIL, Experian, Equifax, CRIF High Mark) within 30 calendar days of receiving the full settlement remittance. If the lender fails to deliver the closure certificate within 30 days without valid justification, it must pay mandatory statutory compensation of ₹5,000 per day of delay directly to the borrower.
How does settling a KreditBee app loan impact your CIBIL score and how can you rebuild it?
Upon full settlement payment, KreditBee reports the account status to credit bureaus as 'Settled' or 'Post-Write-off Settled' with an outstanding balance of ₹0. While this causes a temporary credit score reduction of 70 to 120 points and initiates an institutional cooling period of 12 to 24 months, it permanently eliminates the damaging cycle of monthly default flags. Borrowers can restore their CIBIL score back to 750+ within 18 to 24 months through disciplined repayment on fixed-deposit-backed credit cards and maintaining low credit utilization.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Guidelines on Digital Lending (RBI/2022-23/111 DOR.CRE.REC.66/21.07.001/2022-23)
- RBI Master Direction: Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- Krazybee Services Private Limited: Fair Practices Code, Grievance Redressal Policy & Principal Nodal Officer Matrix
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online Redressal Portal for Fintech & Digital Lending Harassment
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987 — National Lok Adalat Conciliation Framework