- Lending Platform Reality: BharatPe and PostPe act as digital platforms. Your legal loan comes from licensed lenders like Unity SFB, Liquiloans, or Trillion Loans.
- Halting harassment &. Threats: WhatsApp threats, fake legal drafts. And unannounced shop visits violate RBI rules. A formal legal notice stops these tactics fast.
- Stopping QR Cuts &. Bounce Fees: You have a legal right under NPCI rules to cancel auto-debits at your bank. This protects your cash and ends bank return fees.
- Large 45% to 65% Debt Waivers: These digital loans carry no pledged collateral. Lenders offer 45% to 65% principal waivers once an account passes 90 days of default.
- Binding ₹0 No Dues Certificate: Under RBI rules, lenders must give you a stamped No Dues Certificate within 30 days. Delays cost the lender ₹5,000 per day.
Decoding the BharatPe & PostPe Ecosystem
BharatPe and its retail app PostPe offer digital loans across India. Under RBI digital lending rules, they operate as Lending Service Providers. They do not lend money directly from their own balance sheet. Instead, licensed banks and NBFC partners fund each loan.
Key lending partners include Unity Small Finance Bank, Trillion Loans, Liquiloans, and Northern Arc Capital. When a loan defaults, all legal power and settlement authority rest with these licensed lenders.
Defaulting on an unsecured digital credit line is a civil contract dispute under the Indian Contract Act, 1872. It is not a criminal offense. Because these loans have no pledged security, partner lenders use RBI compromise rules to offer deep debt waivers to distressed borrowers.
FinTech Credit Trap & Daily Deductions
BharatPe takes daily repayments by deducting 20% to 50% of customer QR payments. When shop sales drop, these daily deductions hurt working cash. If a merchant switches QR codes, automated systems trigger multiple bank auto-debits.
At the same time, PostPe consumer lines charge high interest and late fees. When payments stop, accounts move through regular default stages under RBI IRACP rules.
| default Stage. | Overdue Aging (DPD). | BharatPe / PostPe Recovery Actions. | Legal Exposure &. Bureau Impact. | Settlement Haircut Potential. |
|---|---|---|---|---|
| SMA-0 (Early Distress). | 1 – 30 Days. | Automated reminder calls, app alerts. And auto-debit runs. | Small score drop. zero legal risk. | Zero waiver (requires full overdue payment). |
| SMA-1 (Mid default). | 31 – 60 Days. | Calls from recovery desks. frequent WhatsApp notices. | CIBIL score drops 40 to 70 points. formal notices sent. | Low (tenure restructuring options offered). |
| SMA-2 (Pre-NPA Escalation). | 61 – 90 Days. | Third-party collection calls. threats of shop visits. | Section 25 PSSA or Section 138 demand notices. | Moderate (waiver of penal fees opens up). |
| NPA (Substandard Asset). | 91 – 180 Days. | Moved to the partner lender stressed asset desk. | Magistrate court filings. formal settlement notices. | High (40% to 55% principal waiver possible). |
| Doubtful / Loss Asset. | 181 – 365+ Days. | Account fully written off by the lender. | Arbitration notices. Lok Adalat settlement referrals. | Maximum (50% to 65% principal waiver possible). |
Once a loan stays unpaid for 90 days, the lender marks it as an NPA. After 180 days, the lender writes off the bad balance. A one-time lump-sum settlement gives the bank quick cash recovery and earns you a major debt waiver.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Stopping Daily QR Deductions & Auto-Debits
Multiple auto-debit attempts worsen debt distress. When your account has low funds, repeated e-NACH runs cause bank bounce fees of ₹250 to ₹590. Lenders also add penal interest and internal dishonour charges.
Under RBI rules, lenders cannot add extra adding interest on unpaid charges. You can stop this drain immediately. Instruct your bank to cancel the e-NACH mandate under NPCI rules. During settlement talks, our legal team ensures all bounce fees and fines are fully removed.
PostPe & BharatPe OTS Slabs & Policies
Under RBI settlement rules, partner lenders evaluate settlement offers using recovery math. Digital loans have no pledged collateral. Lenders compare a quick cash payment against high legal costs and court delays.
Here, expected recovery is weighed against court expenses, legal fees. And locked capital provisions.
Realistic Settlement Haircut Slabs by Digital Product & Aging
| Digital Facility Type. | default Aging Category. | Penal &. Bounce Waiver. | Principal Haircut Range. | Target Settlement Offer. |
|---|---|---|---|---|
| PostPe Consumer Credit Line. | 90 – 180 Days (NPA). | 100% Full Waiver. | 35% to 45% Principal Waiver. | Pay 45% to 55% of Principal. |
| PostPe Consumer Credit Line. | 181 – 365+ Days (Written Off). | 100% Full Waiver. | 50% to 65% Principal Waiver. | Pay 35% to 40% of Principal. |
| BharatPe Merchant Easy Loan. | 90 – 180 Days (NPA). | 100% Full Waiver. | 40% to 50% Principal Waiver. | Pay 45% to 50% of Balance. |
| BharatPe Merchant Easy Loan. | 181+ Days (Doubtful / Loss). | 100% All Penal Charges. | 55% to 65% Principal Waiver. | Pay 30% to 35% of Claim. |
PostPe & BharatPe Loan Settlement & Legal Defense Blueprint
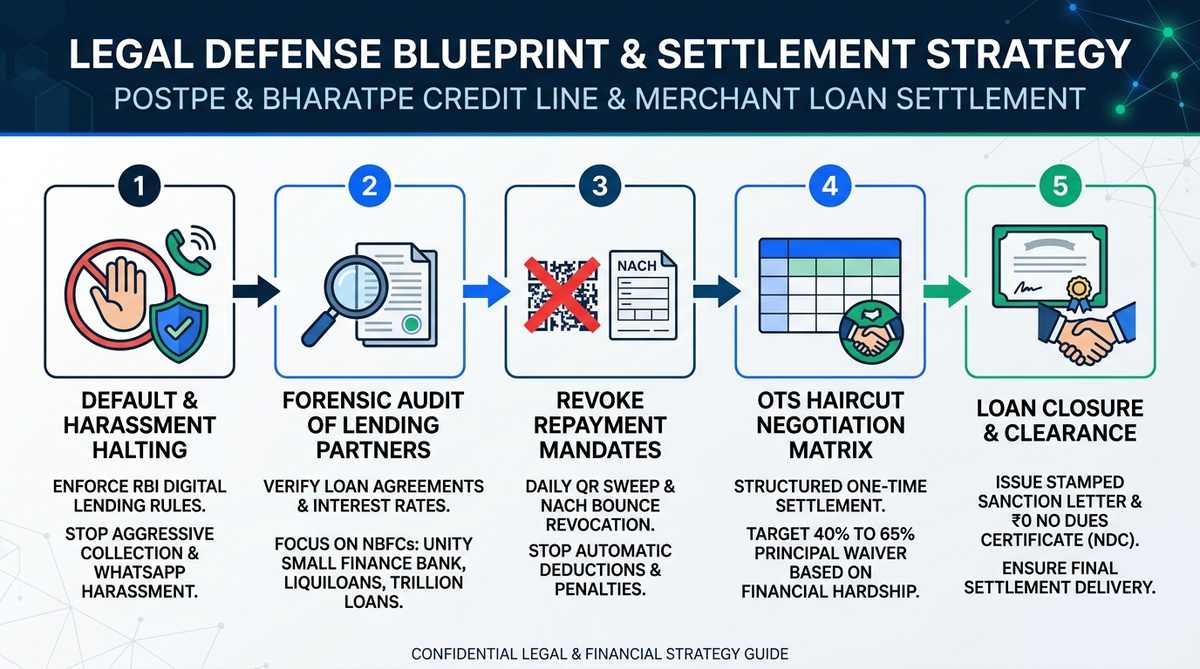
Defending Against Recovery Threats & Coercion
Borrowers facing default often receive dozens of automated calls every day. Unruly agents may send fake court notices on WhatsApp. They may also threaten to call your contacts or visit your shop.
These actions violate RBI digital lending guidelines. Apps cannot read your contact list or message third parties. Agents can only call between 8 AM and 7 PM. Using threats or fake notices is illegal threats under the Bharatiya Nyaya Sanhita, 2023. A formal Cease and Desist notice stops this harassment quickly.
Step-by-Step Guide to a Legally Binding Settlement with
Follow these steps to settle your debt directly with the licensed lender:
1Forensic Loan Audit & Partner NBFC Identification
Check your loan sanction letter and CIBIL report. Identify your true lender, such as Unity SFB or Liquiloans. Separate your core loan amount from bounce fees.
2Revoking e-NACH Mandates & Directing Communication
Ask your bank to cancel the e-NACH mandate under NPCI rules. Send a notice asking the lender to communicate only via formal email.
3Submitting Hardship Compromise Petition
Gather proof of income loss, business slowdown, or medical bills. Submit a formal hardship petition to the partner lender's stressed assets team.
4Navigating Negotiations & Credit Committee Approval
Our legal team counters initial small discounts. We show genuine financial distress to secure an authorized 45% to 65% debt waiver.
5Forensic Verification of the OTS Sanction Letter
Review the official settlement letter on the partner NBFC's letterhead. Verify the CIN, loan number, authorized signature. And full debt discharge terms.
6Direct Account Remittance & Enforcing ₹0 NDC Delivery
Pay the settlement amount directly into the official partner NBFC loan account. Under RBI rules, the lender must deliver your No Dues Certificate within 30 days.
Navigating PostPe Sec 25 PSSA & Lok Adalat
When a digital loan remains unpaid past 60 to 90 days, lenders may issue legal notices. These include Section 25 PSSA notices for bounced auto-debits and Section 138 NI Act notices for cheques. A Section 25 notice is a 15-day demand letter, not an arrest warrant. A timely legal reply explaining your financial hardship prevents court escalation.
Under Supreme Court rulings in Perkins Eastman and TRF Ltd., one-sided arbitrator appointments are invalid. Distressed loans are also settled in National Lok Adalat sessions. Lok Adalat settlements hold the power of a final civil court decree with 45% to 65% debt waivers.
| Resolution Channel. | Governing Legal Framework. | Achievable Haircut. | Resolution Timeline. | Enforceability &. Finality. |
|---|---|---|---|---|
| Direct Partner NBFC OTS. | RBI settlement Master Direction (2023). | 45% – 65% Debt Waiver | 15 to 30 Days. | Binding contract with stamped ₹0 NDC. |
| National Lok Adalat. | Legal Services Authorities Act, 1987. | 50% – 65% Debt Waiver | Single-day hearing. | Civil Court Decree with zero appeal. |
| Arbitration Defense. | Arbitration &. settlement Act, 1996. | Converts to Compromise OTS. | 3 to 8 Months. | Challenged under Perkins precedent. |
| Section 25 PSSA Defense. | Payment and Settlement Systems Act, 2007. | 40% – 55% Debt Waiver | 2 to 6 Months. | Compounded and dismissed upon OTS. |
Sanction Letter Audit & ₹0 NDC Delivery
Avoid fake collection letters. Always confirm that your settlement letter is on the corporate letterhead of the licensed partner lender. It must include registered office details, loan numbers. And a clear debt discharge clause.
Under RBI Circular RBI/2023-24/60, lenders must deliver a formal No Dues Certificate within 30 days of full payment. If the lender delays without cause, it must pay you ₹5,000 for each day of delay.
PostPe Post-Settlement CIBIL Recovery
Settling a loan marks the account as 'Settled' with a ₹0 balance in credit bureaus. Your score may drop by 70 to 120 points initially. However, settlement eliminates active default tags and removes legal risk.
You can rebuild your credit score above 750 in 18 to 24 months. Use a secured credit card backed by a fixed deposit and pay every bill on time.
Why Borrowers in PostPe
SettleLoans stops unlawful recovery harassment through formal legal notices. We cancel predatory auto-debits, defend legal notices. And negotiate directly with partner NBFC teams for maximum debt waivers and official No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: PostPe & BharatPe Loan Settlement
Who actually lends the money on PostPe and BharatPe, and why does it matter for settlement?
BharatPe and PostPe are tech platforms, not registered banks. Regulated partners like Unity Small Finance Bank, Trillion Loans, and Liquiloans fund the loans. Under RBI rules, only these licensed lenders can approve settlements and issue No Dues Certificates.
How can merchants stop BharatPe daily QR deductions and auto-debit sweeps?
Merchants can write to BharatPe support and the partner lender to explain cash troubles. Next, switch your daily sales to a different QR code. Finally, ask your bank to cancel the e-NACH auto-debit mandate under NPCI rules.
What percentage of debt waiver or haircut can be negotiated on defaulted PostPe and BharatPe loans?
PostPe and BharatPe loans are unsecured with no pledged collateral. Once a loan is unpaid for over 90 days, partner lenders routinely offer 45% to 65% debt waivers. They also cancel 100% of late fees and bounce penalties.
Can BharatPe or PostPe recovery agents legally message my phone contacts or send WhatsApp threats?
No. RBI digital lending rules strictly ban agents from messaging phone contacts. Agents cannot send threats, use abusive words, or call after 7 PM. You can report violations to the lender's Nodal Officer and the RBI Ombudsman.
Can BharatPe or its partner NBFC file a criminal police FIR or arrest a borrower for defaulting on a loan?
No. Loan default is a civil contract dispute under the Indian Contract Act, 1872. The police cannot file an FIR or arrest you for default. Threats of arrest by agents violate the law.
What should you do if you receive a Section 25 PSSA or Section 138 NI Act notice from a partner NBFC?
A Section 25 PSSA notice is a 15-day demand letter, not an arrest warrant. You should hire a lawyer to send a formal legal reply. The reply explains your financial hardship and asks for an official compromise settlement.
How do you handle unilateral private arbitration notices issued by BharatPe partner NBFCs?
Supreme Court rulings in Perkins Eastman and TRF Ltd make one-sided arbitrator appointments illegal. Your lawyer can challenge the arbitrator under the Arbitration Act. This halts the case and moves the lender toward a settlement.
How does settling a PostPe or BharatPe loan impact my CIBIL score and credit report?
The lender marks the account as 'Settled' with a ₹0 balance in credit bureaus. Your score drops initially. However, settlement stops new negative marks. You can rebuild your score back above 750 within 18 to 24 months using a secured card.
How long does it take to receive the official No Dues Certificate (NDC) after settling a BharatPe loan?
Under RBI Circular RBI/2023-24/60, lenders must issue your No Dues Certificate within 30 days of full payment. If they delay without valid cause, they must pay you ₹5,000 for each day of delay.
Why is paying an external collection agency or individual agent's UPI ID dangerous?
Never pay money to an agent's personal UPI ID or bank account. Third-party agents cannot grant legal debt waivers. Money paid to agents will not update your official loan account or clear your CIBIL record.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Guidelines on Digital Lending (RBI/2022-23/111 DOR.CRE.REC.66/21.07.001/2022-23)
- RBI Master Direction: Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Master Circular: Fair Practices Code for Non-Banking Financial Companies (NBFCs) &. Digital Lending Service Providers
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online CMS Portal for FinTech harassment, Excessive fines &. NDC Redressal
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987. National Lok Adalat settlement Framework