Debt stress can feel overwhelming. If recovery calls cause deep anxiety, depression, or dark thoughts, seek help right away. Free professional counselors are ready to support you 24/7:
National Tele-MANAS Helpline
Dial: 14416 / 1800-891-4416
Govt. of India 24/7 Free Mental Health Support
KIRAN Mental Health Helpline
Dial: 1800-599-0019
Ministry of Social Justice 24/7 Helpline
- Zero Criminality in Loan Default: Loan default is a civil contract issue. Honest inability to pay can never lead to arrest or jail.
- Criminal Abetment Deterrence (Sec 108 BNS / Sec 306 IPC): Harassment is a crime. Abusive agents face up to 10 years in prison.
- Absolute Third-Party Contact Prohibition: RBI Master Directions ban calls to third parties. Agents cannot contact family, friends, or employers.
- 24-Hour Legal Shield: A lawyer Cease-and-Desist notice stops all calls. Direct visits halt within 24 hours.
- Institutional OTS Resolution: Close your debt via One-Time Settlements (OTS). Banks offer 40% to 65% waivers.
1. The Anatomy of Psychological Harassment
Life brings sudden money crises. Job loss and medical emergencies happen without warning. Inability to pay EMIs is a civil dispute. It is never a crime. But collection agencies often break the law. They use fear and public shame to corner borrowers.
Harassment follows a set pattern. Auto-dialers make 40 to 80 calls daily. Agents change phone numbers to bypass blockers. Next, they send fake legal notices on WhatsApp. They threaten fake arrest warrants. Then, they call elderly parents and office managers. They try to cause extreme shame.
This pressure causes severe panic and sleep loss. Borrowers fall into deep despair. They feel trapped and fear jail. This fear is baseless. Indian penal law and RBI rules protect your basic rights.
2. Statutory Deterrence
Indian law separates civil loan recovery from criminal acts. Pushing a borrower to self-harm is a serious crime.
Section 108 of the Bharatiya Nyaya Sanhita, 2023 (BNS) and Section 306 IPC punish abetment of suicide. The crime carries up to 10 years in prison. Courts treat non-stop abuse, public shaming. And home trespass as criminal abetment.
Key Criminal Penal Provisions Invoked Against Illegal Recovery Harassment
Section 108 BNS / Section 306 IPC: Abetment of Suicide
Applies when severe mental torture drives a person to despair. Field agents and bank managers face non-bailable jail terms.
Section 351 BNS / Section 503 &. 506 IPC: Criminal Intimidation
Punishes threats of violence, property seizure, or fake court cases. Carries two to seven years in prison.
Section 308 BNS / Section 383 &. 384 IPC: Extortion
Forcing payments or seizing jewelry through threats is extortion. It is a cognizable criminal offense.
Section 329 BNS / Section 441 &. 442 IPC: Criminal House-Trespass
Entering private homes without consent is illegal. Call police at 112 for criminal house-trespass.
High Courts and the Supreme Court refuse to quash FIRs under Section 306 IPC / Section 108 BNS. Lenders cannot use recovery targets to torture borrowers.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Constitutional Sanctity
Borrower rights are backed by the Constitution of India. Article 21 protects life and personal liberty. Life means living with dignity and peace. It bars mental and physical abuse.
In Justice K.S. Puttaswamy (Retd.) v. Union of India (2017) 10 SCC 1, privacy was made a fundamental right. It shields your personal life and home. Agents who call relatives or shout in corridors break constitutional law.
In ICICI Bank Ltd. v. Prakash Kaur &. Ors. (2007) 2 SCC 711, the Supreme Court banned musclemen. All loan recoveries must follow court due process.
In Jolly George Varghese v. The Bank of Cochin (1980) 2 SCC 360, Justice V.R. Krishna Iyer ruled that poverty is not a crime. Poor debtors cannot be jailed for unpaid debts.
4. RBI Master Directions & Fair Practices Code
The RBI sets binding rules for debt recovery. These rules apply to all banks and NBFCs under the Master Direction on Outsourcing and the Fair Practices Code (FPC).
Every recovery agent must follow these strict rules:
Mandatory RBI Standards Governing Debt Collection Conduct
Permitted Contact Hours (8:00 AM to 7:00 PM Only)
Agents can only call between 8:00 AM and 7:00 PM. Night calls break RBI rules.
Strict Prohibition on Third-Party Outreach
Lenders cannot call your family, friends, or office. Sharing debt details with others is illegal.
Mandatory Identification &. Authorization
Visiting agents must carry official bank authorization letters. They must also show valid ID cards.
Recognition of Legal Representation
When you appoint a lawyer, direct agent contact must stop. All talks must move to counsel.
Banks hold strict vicarious liability for agent misconduct. Under the RBI Integrated Ombudsman Scheme (2021), you can win up to ₹20 Lakhs for losses and up to ₹1 Lakh for mental agony.
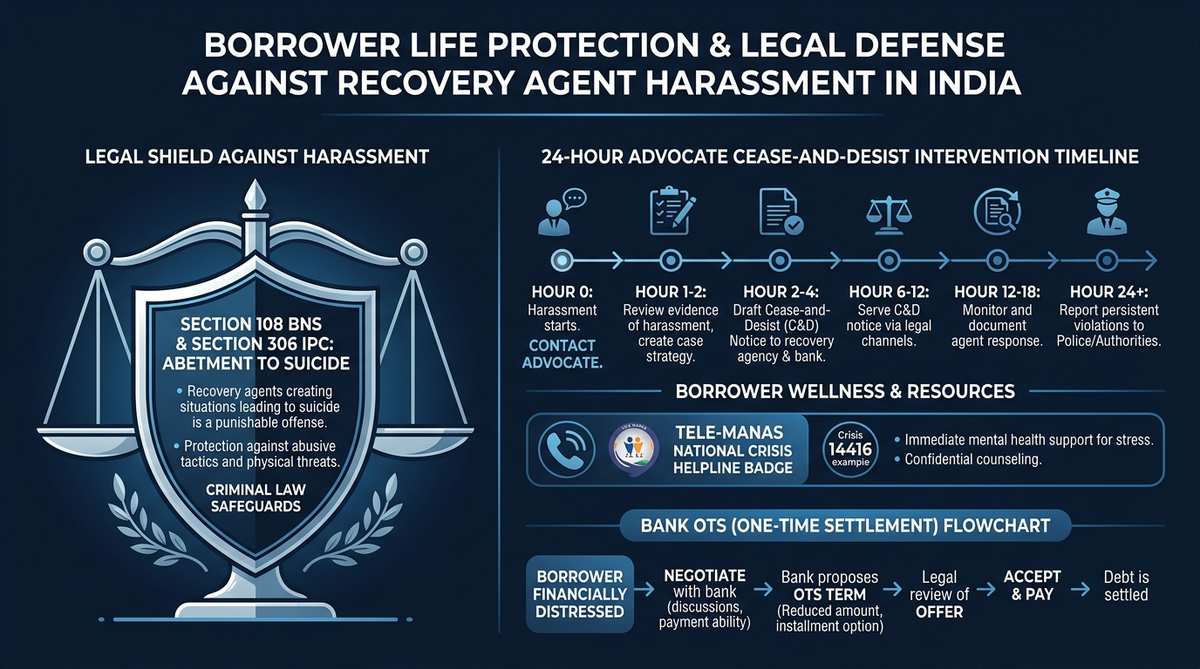
6. The 24-Hour Advocate Intervention
Borrowers need quick relief from abusive calls and visits. Arguing with telecallers does not work. The fastest way to stop abuse is legal representation.
When you hire SettleLoans, our lawyers act fast. We file a Vakalatnama and send a Statutory Cease-and-Desist Notice. We serve it to bank directors and collection agencies.
Hour 0 to 2: Case Intake &. Evidence Compilation
We log call records and abusive chats. We note violations of Section 108/351 BNS and RBI codes.
Hour 2 to 6: Drafting &. Dispatch of Cease-and-Desist Notice
We issue legal notices demanding an immediate halt to calls. We warn of criminal abetment liability.
Hour 6 to 18: Institutional Escalation &. Ombudsman Filing
We file complaints with the RBI Ombudsman. This puts the bank under regulatory audit.
Hour 18 to 24: Direct Contact Freezes &. Dialogue Shift
The bank orders agents to stop calls. All visits halt. Communications shift to our advocates.
Moving communication to lawyers stops panic immediately. You gain peace of mind. You can focus on your job, health. And debt settlement.
7. Bank NPA Accounting Realities
Debt stress is solvable because banks follow clear rules. Under RBI norms, overdue loans become Non-Performing Assets (NPAs) after 90 days.
When a loan becomes an NPA, the bank locks profits as mandatory provisions:
- Substandard Asset (90 to 365 Days): Bank locks 15% in reserve funds.
- Doubtful Asset (12 to 24 Months): Bank locks 100% of the unsecured balance.
- Loss Asset / Written-Off Portfolio: 100% balance sheet write-off against profit.
Suing in court takes 3 to 5 years. Banks must pay court fees and lawyer costs. Under Section 60 of the Code of Civil Procedure (CPC), essential clothes, beds. And tools cannot be seized. Banks use a Net Present Value (NPV) recovery formula:
C_t is recovery cash flow over time t. r is the discount rate. Court delays reduce bank returns.
Court suits offer low net returns. Banks prefer structured One-Time Settlements (OTS). A 40% to 65% waiver gives quick cash and frees locked provisions.
8. Structured One-Time Settlement (OTS) Forensics
Never pay cash or UPI to agents directly. Informal cash only pays late fees. Your main loan balance stays unchanged.
A valid settlement needs three clear steps:
1. Verified OTS Sanction Letter
Issued on bank letterhead. It states the agreed sum, waiver rate. And payment dates.
2. Direct Account Remittance
Pay only to your official bank loan account. Never use personal agent UPI links.
3. Bank-Stamped No Dues Certificate
Get a No Dues Certificate under RBI Circular RBI/2023-24/60. This closes the loan forever.
After full payment, credit bureaus update the status to "Settled". This ends your debt liability and stops calls permanently.
9. Harassment Tactics vs Penal Provisions Matrix
This table outlines illegal recovery acts, penal sections, RBI violations. And direct legal solutions:
| Harassment Tactic. | Penal Offense (BNS / IPC). | RBI Regulatory Violation. | Direct Legal Remedy. |
|---|---|---|---|
| Pushing Defaulter to Extreme Despair / Suicide Threats. | Section 108 BNS / Section 306 IPC (Abetment to Suicide). | Breach of Customer Dignity &. Fair Practices Code. | File Police FIR. Call Tele-MANAS at 14416. |
| Abusive Language, Verbal Threats of Violence. | Section 351 BNS / Section 503 &. 506 IPC (Criminal Intimidation). | Outsourcing Master Direction Para 7 (Harassment Bar). | File Complaint with Magistrate (Sec 175 BNSS). Send Cease-and-Desist Notice. |
| Calling Relatives, Friends, Employers or HR Dept. | Section 356 BNS / Section 499 IPC (Defamation). Sec 66E IT Act. | Privacy Breach. Ban on Calling Third Parties. | File RBI Ombudsman Complaint for up to ₹20 Lakhs. Defamation Claim. |
| Forced Doorstep Entry, Corridors Shouting &. Trespass. | Section 329 BNS / Section 441 &. 442 IPC (House-Trespass). | Visit Rules Breach (8 AM–7 PM Only. ID Mandate). | Call 112 Police for Trespass. Record Video Proof. |
| Fabricated Arrest Warrants &. Fake Court Summons. | Section 336 &. 338 BNS / Section 465 &. 468 IPC (Forgery &. Fraud). | Ban on Deceptive Debt Collection Practices. | File Bar Council Complaint &. Cyber Crime FIR. |
| Coercing Immediate Cash Delivery or Asset Seizure. | Section 308 BNS / Section 383 &. 384 IPC (Extortion). | Breach of Payment Rules. Ban on Unlawful Seizure. | File Police Extortion FIR. File High Court Writ under Article 226. |
10. SettleLoans Anti-Harassment Defense Framework
No one should live in fear of collection threats. Debt is a money issue. It is never a moral failure. SettleLoans shields borrowers from rogue collection agents.
Our banking advocates offer strong legal defense across India. We protect your rights under Section 108 BNS, RBI Fair Practices rules, and Supreme Court privacy mandates. We issue Cease-and-Desist notices that halt harassment within 24 hours. Then, we negotiate 40% to 65% One-Time Settlements. We secure clean No Dues Certificates and restore your peace.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
11. FAQs: Recovery Harassment, Legal Rights & Crisis Support
Read clear answers on recovery abuse, Section 108 BNS laws, crisis helplines. And debt relief in India.
What should I do immediately if recovery agent harassment is pushing me to severe depression or suicidal thoughts?
Your life comes first. Call the Tele-MANAS helpline at 14416 or 1800-891-4416 now. You can also dial KIRAN at 1800-599-0019 for free help. Loan default is only a civil dispute. It is never a crime. Next, hire a debt lawyer. Your advocate sends a Cease-and-Desist notice to the bank. This notice stops all agent contact within 24 hours.
Can recovery agents and bank managers be jailed if their harassment leads to a suicide attempt or extreme distress?
Yes. Section 108 of the Bharatiya Nyaya Sanhita, 2023 (BNS) and Section 306 IPC punish abetment of suicide. It is a non-bailable crime. It carries up to 10 years in prison. The Supreme Court of India has ruled firmly on this. Agents and bank staff who cause mental trauma face direct jail.
How does appointing a debt settlement advocate stop recovery agent harassment within 24 hours?
RBI rules mandate fair loan recovery. First, you sign a Vakalatnama with your lawyer. Then, your lawyer sends a Cease-and-Desist notice to the bank. The bank must stop all calls and visits at once. All future talks go through your lawyer.
Can a bank or loan recovery agency contact my family members, parents, spouse, or employer?
No. RBI rules ban lenders from calling family, friends, or your boss. Agents cannot share loan details with others. Doing so breaks RBI Fair Practices and privacy under Article 21. It is also defamation under Section 356 BNS / Section 499 IPC.
What criminal sections apply against recovery agents who use abusive language or threats of violence?
Threats and abuse by agents are crimes. Police can file cases under Section 351 BNS / Section 506 IPC for intimidation. Extortion falls under Section 308 BNS / Section 384 IPC. Trespass falls under Section 329 BNS / Section 441 IPC. You can file a police FIR and alert the RBI Ombudsman.
Can I go to jail for being unable to pay an unsecured personal loan or credit card bill?
No. You cannot go to jail for unpaid loans or cards. Default is a simple civil contract breach. The Supreme Court in Jolly George Varghese v. The Bank of Cochin upheld this under Article 21. Agents who threaten arrest break the law.
What evidence should I gather to prove recovery agent harassment and mental torture?
Keep clear proof of all abuse. Record calls where agents make threats or call after 7:00 PM. Save screenshots of WhatsApp chats and SMS texts. Keep CCTV clips of visits. Download call logs showing frequent calls. This proof helps you file police FIRs and RBI complaints.
What compensation can the RBI Integrated Ombudsman award for mental agony caused by recovery harassment?
The RBI Integrated Ombudsman can pass binding cash orders. Lenders may pay up to ₹20 Lakhs for money loss. The Ombudsman can also grant up to ₹1 Lakh for mental agony and harassment.
How does a formal One-Time Settlement (OTS) resolve my debt permanently after harassment is stopped?
Your lawyer stops all abuse first. Next, your advocate seeks a One-Time Settlement (OTS). Banks often offer 40% to 65% waivers on bad loans. Once you pay the agreed sum, the bank gives a No Dues Certificate (NDC). This closes the debt for good.