- Civil Matter. Zero Police Powers. Loan default is a civil dispute. Police cannot summon or arrest you.
- Cognizable Crime (Section 204 BNS). Posing as police brings 3 years in jail. Section 170 IPC and IT Act apply.
- Strict RBI Harassment Ban. RBI bans false legal threats. Agents cannot impersonate police officers.
- Instant Cyber & Police FIR Recourse. Report calls on cybercrime.gov.in. Dial 1930. File a police FIR.
- Leverage for 45%–65% OTS. Impersonation proof creates strong leverage. Banks agree to 45% to 65% OTS settlements.
1. The Crisis of Police Impersonation
Fake police calls rise daily. Rogue agencies break debt collection laws. Agents pose as police officers. They pretend to be court bailiffs.
Callers want to cause panic. They make fake arrest threats. They threaten police home raids. They cite Section 318(4) BNS. They invoke Section 420 IPC. Some send fake notices with forged emblems.
Callers claim to be Crime Branch inspectors. They demand fast UPI payments. They threaten instant arrest.
Loan default is a civil dispute. The Contract Act applies here. The Supreme Court confirms this. Default is not a crime.
Real police never collect loan dues. Posing as police is a crime.
2. Statutory Criminal Offenses
Posing as police is strictly illegal. The Bharatiya Nyaya Sanhita (BNS), 2023 applies. The IPC punishes offenders too:
Impersonating a Public Servant (Section 204 BNS / Section 170 IPC).
Posing as police is a crime under Section 204 BNS. It violates Section 170 IPC. It brings 3 years in jail.
Cheating by Personation & Cyber Fraud (Section 66D IT Act, 2000).
Calling as fake police is cyber fraud. Section 66D IT Act applies. It orders 3 years in jail and heavy fines.
Criminal Intimidation & Extortion (Section 351 & 308 BNS / Sections 506 & 384 IPC).
Threatening arrest to extort money is illegal. Section 351 BNS and Section 308 BNS apply. Section 506 IPC and Section 384 IPC apply too. It brings up to 7 years in jail.
Forgery of Government Seals & Insignia (Section 336 BNS / Section 468 & 471 IPC).
Forging police seals on notices is a crime. Section 336 BNS applies. Section 468 IPC and Section 471 IPC apply. It is a non-bailable offense.
Lawyers record these crimes. This holds banks liable. Lenders stop rogue agents fast.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. RBI Master Directions
The RBI protects loan borrowers. Banks face direct blame for agent abuse.
The Supreme Court banned brute force in debt collection. The Shanti Devi Sharma (2008) case sets this rule. Banks bear full liability for agent harm.
Lenders cannot use fake legal threats. Calls before 8 AM are banned. Calls after 7 PM are banned too.
Agents must hold IIBF DRA certificates. They must show ID cards. They cannot hide their true identity.
Under RBI Outsourcing rules, banks own agent acts. Illegal calls bring heavy RBI fines.
RBI rules protect your rights. Supreme Court orders help you too. They force banks to settle debts fast.
4. Bank Accounting & Fake Police Threat Risks
Why do recovery agents use illegal threats? They face heavy financial pressure. Third-party agencies work on commission. They earn 10% to 25% of collected funds. After 90 days of default, loans become Non-Performing Assets (NPAs). This triggers mandatory RBI provisioning rules:
| Asset Delinquency Stage. | Overdue Aging Timeline. | Mandatory RBI Capital Provision. | Settlement / Haircut Scope. |
|---|---|---|---|
| Special Mention Account (SMA-1/2). | 31 to 90 Days Overdue. | 5% General Capital Provision. | Penal Interest & Late Fee Waivers. |
| Substandard NPA. | 91 to 365 Days Overdue. | 25% Unsecured Capital Provision. | 35% to 45% Principal Haircut. |
| Doubtful NPA 1 (D1). | 12 to 24 Months Default. | 100% Unsecured Capital Provision. | 45% to 55% Principal Haircut. |
| Doubtful NPA 2 / Loss Asset. | 24+ Months or Written-Off. | 100% Full Balance Sheet Write-Off. | 55% to 65% Principal Haircut. |
Unsecured debts lack pledged assets. Order 37 CPC suits take years. DRT trials take long too. Court costs and legal retainers add up. Thus, banks check the Net Present Value (NPV) of Recovery. They compare long legal fights against fast cash settlements:
Here C_t is cash flow. The letter r is the rate. Deductions cover court costs, legal fees, RBI risks, and locked funds.
Lawyers expose criminal impersonation fast. The bank risks heavy RBI fines. They risk public shame too. Credit teams act fast. They remove rogue agencies. They grant a 45% to 65% OTS settlement.
5. Fake Police Call Defense Roadmap
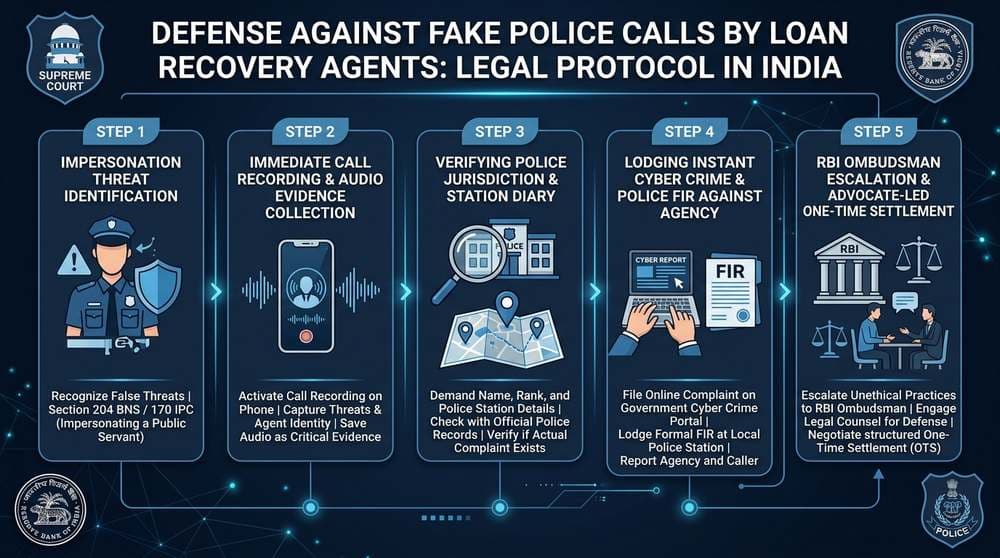
The visual roadmap below shows our 5-step defense plan. Experienced banking litigation advocates use this plan. It helps spot fake officers, record audio proof, lodge FIRs, and secure debt relief.
6. The Emergency 5-Step Protocol
Fake police calls cause fear. Do not panic. Never pay money in fear. That invites more calls. Follow this clear 5-step plan:
Step 1: Activate Call Recording & Preserve Digital Evidence.
Turn on auto call recording. Let the caller speak. Note the phone number, date, and time. Save all WhatsApp chats and fake notices.
Step 2: Cross-Examine & Demand Official Verification Details.
Ask for the caller's full name. Ask for their belt number and rank. Request the police station address. Demand the General Diary (GD) entry number. Warn them the call is being recorded.
Step 3: Verify with the Local Police Station Landline.
Find the police station landline online. Call the station directly. Ask the Duty Officer if such a notice exists. Police always confirm it is fake.
Step 4: Lodge a Complaint on the National Cyber Crime Portal (cybercrime.gov.in / 1930).
Lodge a complaint at cybercrime.gov.in. Or dial helpline 1930. Pick "Cyber Extortion / Cheating by Personation". Attach audio files and forged notices.
Step 5: Retain an Advocate to Serve a Criminal Legal Notice on the Bank.
Hire a debt defense lawyer. Send a legal notice to the bank MD. Send a copy to the Principal Nodal Officer. Warn them of Section 204 BNS action. File an RBI Ombudsman complaint.
These steps stop recovery threats. You create an official police record. You keep your family safe.
7. Converting Criminal Recovery Harassment into an
Fake police calls show agency panic. Agencies know civil suits take years. They know unsecured debts lack assets to seize. Exposing fake calls gives you immense leverage. You can win a strong One-Time Settlement (OTS).
Do not pay unfair penalty charges. Debt defense lawyers draft formal bank settlement plans:
Submit proof of financial distress. Add medical records, job loss letters, or business loss proof. Show that default was not planned.
Demand a 100% waiver on late fees and interest. Seek a 45% to 65% cut on principal debt based on NPA age.
Make sure terms order the bank to recall your file. The bank must ban all third-party agency calls.
Split the settlement sum across 2 to 4 monthly parts. Settle debt without losing family emergency funds.
8. Sanction Letter Forensics, Direct Remittance, RBI ₹0 NDC
Be careful when closing a debt settlement. Fraudulent agents often make fake settlement letters. They make verbal promises to pocket cash tokens. Never transfer money without legal verification of the sanction letter.
- Institutional Bank Letterhead. Official bank letterhead is mandatory. Look for internal reference numbers. Check the manager signature.
- Borrower & Account Identifiers. Check your full legal name and PAN. Verify the 16-digit loan account number.
- Unconditional Debt Extinguishment Clause. The letter must state full debt waiver. All claims must end upon payment.
- Direct Bank Account Remittance. Pay directly into your registered loan account. Use NEFT, RTGS, or bank portals. Never pay agents directly.
Under RBI Circular RBI/2023-24/60, lenders must issue an official No Dues Certificate (NDC) within 30 calendar days. They must clear credit bureau records. Any delay beyond 30 days triggers a penalty. The bank must pay ₹5,000 per day to the borrower.
Credit Bureau Reporting & Score Rehabilitation After Settlement
After settlement, lenders report the loan as "Settled" or "Post-Write-off Settled". The overdue balance becomes ₹0. Your credit score may drop at first. But default interest stops immediately. Collection calls end for good. Use a secured credit card. Keep credit usage below 30%. Pay bills on time. Your score can cross 750 in 18 to 24 months.
9. Coercive Threats vs Legal Resolution Matrix
Compare coercive recovery threats against genuine judicial channels and advocate settlements:
| Resolution Channel. | Legal Authority & Jurisprudence. | Borrower Protection Level. | Typical Timeline. | Final Legal Effect. |
|---|---|---|---|---|
| Fake Police / Threat Calls. | Section 204 BNS and Section 170 IPC crime. | Zero protection. Severe mental stress. | Non-stop ongoing harassment. | Triggers police FIR and RBI fines. |
| Civil Court Litigation (Order 37 CPC). | Order 37 CPC civil dispute. | Full court process and legal defense rights. | 2 to 4 Years. | Judicial order with strict execution rules. |
| RBI Banking Ombudsman Portal. | RBI Integrated Ombudsman Scheme 2021. | Direct regulatory check on unfair collection. | 30 to 45 Days. | Binding RBI orders and financial relief. |
| Advocate-Led 55% OTS. | Mutual compromise settlement agreement. | Full legal safety and final closure. | 15 to 30 Days. | Total debt closure with ₹0 NDC. |
10. SettleLoans Legal Defense & Anti-Harassment Advisory
Handling fake police threats needs skilled banking lawyers. We enforce RBI rules and BNS laws. SettleLoans gives complete legal defense across India. We send cease-and-desist notices to bank leaders. We file reports with Cyber Police and the RBI Ombudsman. We talk directly to bank credit heads. Our lawyers win 45% to 65% principal waivers with official No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
11. FAQs: Fake Police Calls & Recovery Agent Harassment
Read clear answers about fake police calls, recovery agent impersonation, and debt settlement in India.
Can a police officer call or arrest me for an unpaid personal loan or credit card default?
No. Loan default is a civil dispute. Police cannot summon or arrest you for debt. Police need a court warrant to act.
What criminal offenses does a recovery agent commit by pretending to be a police officer?
Posing as police violates Section 204 BNS and Section 170 IPC. It breaches Section 66D IT Act. It also violates Section 351 BNS and Section 308 BNS.
How can I instantly identify whether a police call regarding loan recovery is genuine or fake?
Real police never ask for cash or UPI transfers. Demand officer name, rank, and police station. Ask for notice under Section 35(3) BNSS or Section 41A CrPC. Check station landline numbers.
What steps should I take immediately when receiving a fake police call from a recovery agent?
Stay calm. Turn on call recording. Note caller number and time. Never transfer money. Lodge a report at cybercrime.gov.in (dial 1930). Have a lawyer send notice to the bank.
Can I file an FIR against the recovery agency and the lending bank for impersonation?
Yes. You can file an FIR under Section 204 BNS (Section 170 IPC). You can add Section 318(4) BNS (Section 420 IPC) and Section 66D IT Act. Banks bear vicarious liability for agent acts.
What are the RBI rules regarding recovery agents using police threats or harassment?
Under RBI rules, agents cannot use threats or pose as police. They cannot call before 8 AM or after 7 PM. Breaking rules brings heavy RBI fines.
Can a fake police call give me legal leverage to negotiate a One-Time Settlement (OTS)?
Yes. Audio proof gives strong legal leverage. Banks fear police FIRs and RBI fines. Credit teams recall accounts and approve a 45% to 65% OTS waiver.
What documents are required in a genuine One-Time Settlement sanction letter?
A real OTS letter uses bank letterhead. It shows your name, PAN, and loan account number. It states the agreed sum, due date, and full debt closure terms.
What is the mandatory RBI timeline for issuing a No Dues Certificate after loan settlement?
Under RBI Circular RBI/2023-24/60, banks must issue an NDC within 30 days. They must update credit bureaus. Late delivery triggers a ₹5,000 per day penalty.
Will a loan settlement permanently ruin my CIBIL credit score?
No. The bureau marks the loan as 'Settled' with ₹0 balance. The score drop is short-lived. Good credit habits rebuild your score past 750 in 18 to 24 months.