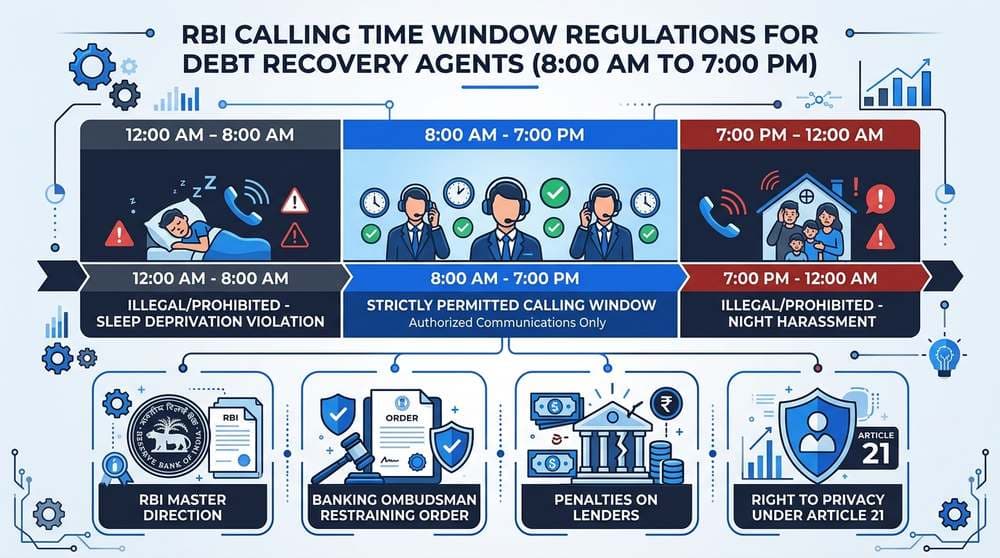
- Strict 8:00 AM to 7:00 PM Calling Window: The RBI bans early calls. It bans calls after 7:00 PM. All night calls are illegal.
- Constitutional Right to Sleep (Article 21): Sleep is a basic right. The Supreme Court in Ramlila Maidan protected sleep from disturbance.
- Criminal Intimidation Penalties: Late threats bring criminal cases. Sections 351, 352, and 308 BNS apply. (These replace Sections 503, 506, and 384 IPC.)
- Instant Banking Ombudsman Injunction: Send call logs to the RBI Ombudsman. This freezes collection calls fast. Banks face strict audits.
- Leveraging Harassment for 45%–65% OTS: Timing violations give strong legal leverage. Banks agree to 45% to 65% OTS settlements.
1. The Crisis of Predatory Calling Hours
Agencies often target borrowers late at night. Borrowers get endless calls. Agents send robocalls and chats at midnight, 2:00 AM, or before 6:30 AM.
This timing is intentional. Agencies call when you rest. They disrupt sleep to spark panic. Their goal is quick debt recovery under extreme stress.
Late calls cause panic. They lead to deep fatigue. This mental stress pushes borrowers into bad terms. It forces illegal fee payments.
Lenders use auto-dialers all night. These systems spam phones with fake threats. They bypass normal calling limits.
Late-night debt collection is illegal in India. The RBI sets strict hours. Violations create civil, regulatory, and criminal liability for lenders.
2. Statutory Framework
RBI rules control debt recovery. They stem from Section 21 and Section 35A of the Banking Regulation Act, 1949. They also derive from the RBI Act, 1934. These rules bind banks and loan apps.
The RBI Master Direction on Fair Practices Code sets strict hours. The Outsourcing Guidelines also apply. Agents cannot call before 8:00 AM. They cannot call after 7:00 PM. Calls outside this window break the law.
The Supreme Court protects borrowers under Article 21. In Ramlila Maidan (2012), the court upheld the Right to Sleep.
Sleep is vital for health. In Prakash Kaur (2007) and Shanti Devi Sharma (2008), the Supreme Court banned force in collections.
Calls are allowed from 8:00 AM to 7:00 PM only. Night calls are banned.
Banks cannot disown rogue agencies. Lenders bear full blame for agent actions.
In Puttaswamy (2017), the Supreme Court protected home privacy.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Criminal Intimidation, Tort of Harassment
Late-night threats by agents are crimes. Sections 351, 352, and 308 of the Bharatiya Nyaya Sanhita (BNS), 2023 protect you.
Key criminal laws against late recovery calls include:
Criminal Intimidation (Section 351 & 352 BNS / Sections 503 & 506 IPC)
Threatening harm over night calls is criminal intimidation. Threats bring up to seven years in jail, a fine, or both.
Extortion & Threat of Injury (Section 308 BNS / Sections 383 & 384 IPC)
Demanding money through threats is extortion. It brings up to three years in prison plus court fines.
Cyber Harassment & Electronic Stalking (Section 66E, 67 & 72 IT Act, 2000)
Sending abusive audio clips or continuous robocalls is cyber harassment. The IT Act punishes it with up to three years in jail.
Victims can also file civil damage suits or Consumer Court cases. Courts award ₹50,000 to ₹5,00,000 for mental agony and sleep loss.
4. Bank Accounting & Night Calling Violations
Banks follow strict accounting rules. When loans remain unpaid for 90 days, lenders mark them as Non-Performing Assets (NPAs).
For NPAs, banks must lock capital in mandatory provisions. Provisions rise from 15% to 100% as loans age. This locked money hurts bank profits.
C_t is recovery cash flow. r is discount rate. Court fees and locked funds reduce bank returns.
When a lawyer proves night calling violations, bank risk rises. Lenders face Ombudsman fines of up to ₹20 Lakhs and public scrutiny.
Banks fear Ombudsman penalties. They want quick cash recovery. Thus, banks choose the settlement route. Recovering 35% to 55% in cash yields higher returns.
5. Visual Framework: RBI Debt Recovery Operating Window
This chart outlines RBI calling hours. It highlights banned night hours. It also shows your legal remedies:
6. Emergency Action Plan
When late calls start, act calmly. Save all evidence. Clear records help lawyers take swift action.
Follow these four advocate steps to halt illegal night debt collection calls:
Never delete call logs. Export CDR logs from your telecom provider. Record calls. Ask agents for their name and agency. Save screenshots of late texts.
Your lawyer sends a legal notice to the bank Principal Nodal Officer. The notice cites call timestamps. It demands an agency freeze within 48 hours.
File a complaint on the RBI CMS portal (cms.rbi.org.in). Attach CDR logs, audio files, and the notice. The Ombudsman can award up to ₹20 Lakhs in compensation.
If calls contain threats or vulgar abuse, file a police complaint. Also report on cybercrime.gov.in under Sections 351, 352, and 308 BNS.
7. Strategic Advocate Negotiations
A regulatory breach is your best negotiation tool. When lawyers prove night calls, the power shifts to you.
Banks want to avoid RBI scrutiny. Call audio proves timing breaches. It can spark RBI audits and heavy fines.
Your lawyer shows financial hardship along with proof of RBI violations. The bank waives 100% of penal interest and accepts a 35% to 55% settlement.
Banks fear Ombudsman penalties. They also want quick cash recovery. Thus, banks choose the settlement route.
8. Forensic Sanction Letter Verification
Beware of fake settlement letters from rogue agents. Never pay without verifying the sanction letter.
An authentic One-Time Settlement Sanction Letter must meet strict banking rules:
- Issued on official bank letterhead with digital code.
- States borrower name, PAN, and exact loan account number.
- Specifies total waiver, net payment sum, and due dates.
- Signed by an authorized bank officer with power of attorney.
- Never transfer funds to personal UPI IDs or agency accounts.
- Pay directly into your specific loan account via RTGS/NEFT.
- Collect official printed cash receipts if paying at a counter.
- Retain transaction UTR numbers for permanent records.
Under RBI Circular RBI/2023-24/60, lenders must issue an NDC in 30 days. They must update credit scores. Lenders pay ₹5,000 per day for any delay.
9. Night Calling Legal Defense Matrix
This table compares lawful recovery rules with illegal practices and direct remedies:
| Operational Parameter | Permissible Legal Standard (RBI) | Actionable Illegal Practice | Statutory Remedy & Legal Provision |
|---|---|---|---|
| Calling Time Window | Only 8:00 AM to 7:00 PM. Permitted on working days. | Calls at night or before 8:00 AM. Illegal midnight calls. | RBI Master Direction. Art. 21 Right to Sleep. |
| Tele-calling Frequency | Max 2 to 3 calls per week. Reasonable follow-up. | Continuous calls. Robocall spam and threats. | TRAI UCC Norms. Sec 351 BNS Intimidation. |
| Identification Protocol | Must share name and bank. Must show DRA ID card. | Fake names. Spoofed calls. Fake police threats. | Sec 319 BNS Impersonation. RBI Outsourcing rules. |
| Third-Party Disclosure | Strict privacy. Contact only the borrower. | Calling family, friends, or employers. | Sec 356 BNS Defamation. DPDPA 2023 rules. |
| Verbal Demeanor | Polite and civil talk. Non-threatening tone. | Abusive words. Shouting. False arrest threats. | Sec 352 BNS Insult. Police FIR action. |
| No Dues Certificate | Must issue in 30 days. Clean credit update. | Holding NDC back. Demanding extra illegal fees. | RBI ₹5,000 per day penalty compensation. |
10. SettleLoans Night Harassment Legal Defense
At SettleLoans, we believe loan default is never a crime. No citizen should face sleep loss or late-night threats.
Our banking lawyers provide strong legal defense across India. We serve legal notices on lenders. We file RBI Ombudsman cases. We also secure 45% to 65% OTS debt waivers with clean No Dues Certificates.
We serve legal notices on bank Nodal Officers. We halt calls within 24 to 48 hours.
We file complaints with the RBI Ombudsman and Cyber Police. We secure fast restraining orders.
We leverage documented violations. We negotiate OTS settlements with No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: Late-Night Recovery Harassment & Legal Remedies
Clear legal answers on recovery calling hours. Learn RBI rules, sleep rights, and complaint steps.
Q1.What are the legal calling hours for bank recovery agents in India?
Under RBI Master Directions, agents can only call from 8:00 AM to 7:00 PM. Calls, messages, or visits outside these hours break RBI rules.
Q2.Is calling at midnight or early morning considered a criminal offense?
Yes. Calling late at night or early morning is criminal intimidation under Section 351 BNS / Section 506 IPC. It also violates Article 21.
Q3.How can I obtain an immediate restraining order against predatory recovery calls?
You can file a complaint with the RBI Banking Ombudsman on the CMS portal. A legal notice to the bank Nodal Officer freezes calls at once.
Q4.What penalties does the RBI impose on banks for late-night calling violations?
The RBI imposes heavy monetary fines on banks for timing breaches. The RBI can order lenders to ban the agency and pay damages to borrowers.
Q5.Can recovery agents use automated diallers or virtual numbers to bypass timing restrictions?
No. Using auto-dialers to call outside 8:00 AM to 7:00 PM is illegal. It breaks both RBI digital lending rules and TRAI telecom norms.
Q6.Can a recovery agent contact my family members or spouse after 7:00 PM?
No. Agents cannot call family members or employers at any hour. Doing so breaks RBI privacy rules and Section 356 BNS / Section 499 IPC.
Q7.How does documenting late-night calls help in One-Time Settlement (OTS) negotiations?
Proof of late-night calls gives you strong leverage. Banking lawyers use this proof to negotiate an OTS, winning 45% to 65% debt waivers.
Q8.What evidence should I preserve to prove illegal recovery call timings?
Save call logs with exact timestamps. Keep call recordings showing the agent name and agency. Save screenshots of late-night SMS and chat messages.
Q9.Can I file a police FIR if recovery agents threaten me over late-night phone calls?
Yes. If calls involve threats or abuse, you can file a police FIR under Sections 351, 352, and 308 BNS. You can also report on the cyber portal.
Q10.What is the mandatory timeline for receiving a No Dues Certificate after OTS payment?
Under RBI Circular RBI/2023-24/60, lenders must issue an NDC within 30 days of settlement payment. Delays incur a penalty of ₹5,000 per day.