- Ban on Unregistered Numbers: TRAI and RBI rules require recovery calls to use 140-xxx or 160-xxx series. Using virtual numbers to bypass caller blocks is illegal.
- IT Act Impersonation Protections: Using spoofed caller IDs triggers criminal liability under Section 66D IT Act. Offenses carry up to 3 years in jail.
- DoT Chakshu Portal Complaints: Debtors can file complaints on the DoT Sanchar Saathi Chakshu portal. This leads to telecom audits, SIM cancel. and IMEI blocks.
- Bank Bank Liability: Under Section 182 Contract Act and RBI rules, lenders are liable for collection agents. Banks cannot disown abuse by third-party callers.
- Turning abuse into 55% OTS: Documenting digital abuse in an advocate notice creates high regulatory risk for the bank. Lenders quickly halt calls and offer a 45% to 65% settlement.
1. The Modern Architecture of Digital Harassment
Debt collection in India has changed fast in recent years. Direct branch visits and direct calls have been replaced by digital calling setups. When loans go unpaid, debtors face non-stop automated calls. These calls come from rotating virtual numbers, cloud SIP lines. And disposable VoIP channels.
Collection agencies use automated dialers with smart rotation scripts. When you block a number on Truecaller, the dialer switches to a new caller ID. It picks from hundreds of virtual numbers. This bypasses phone blocking tools. This leads to non-stop ringing all day.
Agencies use cloud call systems that cycle through mobile number ranges. If you hang up, the dialer calls back right away. It uses a new virtual line to cause distress.
Collectors use automated WhatsApp bots with hidden timers. They send threats and fake notices. They rely on auto-deletion to erase proof before you see a lawyer.
Rogue callers often pose as court bailiffs or crime branch officers. They demand instant UPI payments to unverified accounts. Debtors should know that these tactics are illegal cyber offenses and direct violations of RBI rules.
2. Statutory Laws on Virtual Number Harassment
Indian telecom and cyber laws ban anonymous, automated. And spoofed bank calls. Recovery agencies break clear laws when using virtual lines and VoIP dialers. These rules come from TRAI, DoT, MeitY. And the RBI:
Under TRAI TCCCPR rules, every bank and collection agency must register on telecom DLT platforms. All recovery calls must come from approved 140-xxx or 160-xxx series. Calling from private 10-digit SIMs or virtual numbers is illegal and leads to immediate telecom disconnection.
Anyone using devices to cheat by personation faces up to 3 years in jail. Courts also impose heavy fines under Section 66D IT Act.
Sharing debtor contact details with unvetted cloud dialer networks is a breach of data privacy. It attracts severe civil damages.
The RBI Master Direction limits recovery calls strictly between 8:00 AM and 7:00 PM. Automated robocalls outside these hours violate central banking rules.
The Supreme Court confirmed in the Puttaswamy (2017) case that privacy is a basic right under Article 21. No lender can subject debtors to non-stop digital stalking or automated spamming.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Bank Liability for Virtual Harassment Agents
Lenders often claim they are not responsible for rogue callers, blaming third-party agencies instead. Under Indian contract law and banking rules, this defense is completely invalid.
The relationship between a lender and its collection agency is governed by the Doctrine of Bank Liability:
Section 182 & 238 Indian Contract Act, 1872 (Principal-Agent Law)
Section 182 defines the principal-agent relationship. Under Section 238, frauds and misrepresentations by agents legally bind the principal bank itself.
RBI Master Direction on Managing Risks and Code of Conduct in Outsourcing of Financial Services
The RBI states that outsourcing debt recovery does not reduce the bank's legal duties. Banks must ensure agents follow the Fair Practices Code and use only verified phone lines.
Judicial Precedent: ICICI Bank Ltd. v. Prakash Kaur (2007) 2 SCC 711
The Supreme Court ruled that banks cannot use musclemen or threats to recover debt. Lenders remain directly liable in court for agent misconduct.
When lawyers serve a legal notice on bank executives, the lender cannot escape liability. Proving that the bank shared your file with rogue dialer networks exposes the bank to severe fines.
4. Bank Provisions & Virtual Harassment Fallout
Knowing bank accounting explains why agencies use intense virtual dialing campaigns. bank banks and NBFCs follow strict RBI reserves rules. When an unsecured personal loan or credit card default passes 90 days, it becomes a defaulted Asset (NPA). The bank must set aside capital buffers:
| Prudential Asset Category. | default Aging Bracket. | Mandatory RBI Capital Provision. | settlement / Haircut Scope. |
|---|---|---|---|
| Special Mention Account (SMA-1/2). | 31 – 90 Days Overdue. | 5% Standard Capital Buffer. | Penal Interest & Overdue Charge Waivers. |
| Substandard NPA. | 91 – 365 Days Overdue. | 25% Unsecured reserves. | 30% – 45% Principal Haircut. |
| Doubtful Asset 1 (D1). | 12 – 24 Months Default. | 100% Full reserves Requirement. | 45% – 55% Principal Haircut. |
| Doubtful Asset 2 / Loss Asset. | 24+ Months / Write-Off Bucket. | 100% Balance Sheet Write-Off. | 55% – 65% Principal Haircut. |
Third-party collection agencies earn high commissions of 12% to 28% on recovered funds. Tele-callers lose payouts when loans enter deep write-off stages. Because of this, they use auto-dialers to pressure debtors. Once lawyers stop the calls, the bank reviews the loan. The bank evaluates the debt using the Net Present Value (NPV) of Recovery formula:
Where C_t is the expected recovery cash flow. And r is the discount rate. Deductions account for 3 to 5 years of legal delays, ombudsman fines. And locked capital reserves.
Banks realize that pursuing hostile digital collection creates severe legal risks. Sanctioning a settlement with a 45% to 65% principal waiver becomes the bank's smartest money choice.
5. Virtual Number Harassment Defense Roadmap
The roadmap below shows the 5-step process used by banking lawyers. It helps preserve digital evidence, file DoT Chakshu complaints. And secure a 55% OTS.
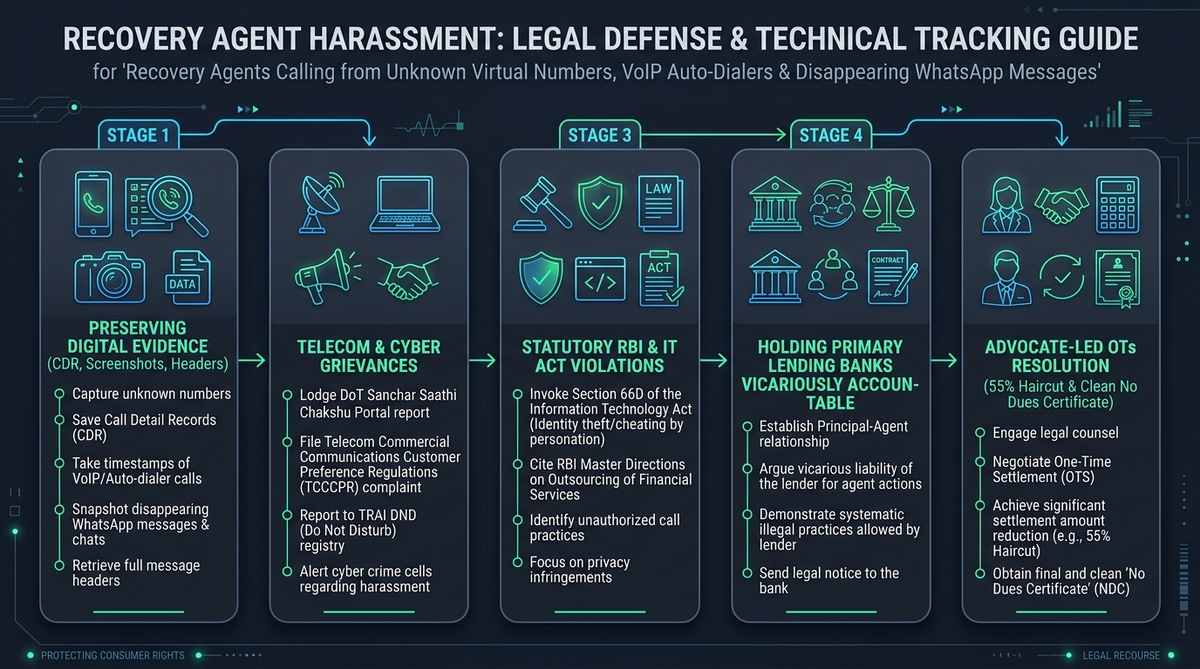
6. Digital Evidence & Forensics Against Spoofing
When dealing with virtual auto-dialers and hidden WhatsApp messages, verbal complaints are not enough. The RBI Ombudsman and cyber crime units need clear digital proof under Section 63 of the Bharatiya Sakshya Adhiniyam, 2023:
Step 1: Telecom Provider CDR (Call Detail Record) Retrieval
Request itemized Call Detail Records from your mobile operator (Jio, Airtel, Vi). Official CDR logs prove call frequencies, timestamps. And numbers. This provides hard evidence of automated abuse.
Step 2: WhatsApp Header Capture & Video Screen Forensics
Take instant full-screen screenshots showing the sender's full phone number and timestamp before messages disappear. Record a continuous screen video scrolling through the chat context.
Step 3: Filing Formal Complaint on DoT Sanchar Saathi Chakshu Portal
Visit the official Sanchar Saathi portal (sancharsaathi.gov.in) and open the Chakshu facility. Report the virtual numbers and dialer patterns under suspected fraud. This triggers telecom audits and SIM blacklisting.
Step 4: TRAI TCCCPR Telecom Carrier Escalation
Forward unregistered virtual numbers to your carrier. Send an SMS to 1909 or use the TRAI DND app to report spam.
Compiling this digital record enables your legal counsel to hold both the agency and the bank fully accountable.
7. Converting Digital Harassment into Leverage
Digital abuse is stressful. But it gives the debtor strong legal leverage. Persistent robotic calling shows the lender has no fast legal way to claim your assets. By hiring a lawyer to document these violations, you shift the advantage in your favor.
Our banking defense lawyers use these documented infractions to settle a One-Time Settlement (OTS):
Show proof of income loss, job changes. or medical bills. This proves that your default was genuine.
Secure a 100% waiver on late fees and penal interest,. a 45% to 65% reduction on the principal balance.
Require the bank to cancel all collection agency mandates and permanently remove your numbers from auto-dialer lists.
Divide the negotiated settlement sum into 2 to 4 monthly installments to settle without selling personal assets.
8. Sanction Letter Forensics & NDC for Spoofed Calls
Debtors must be careful when receiving settlement offers over WhatsApp or phone calls. Rogue agents often share fake settlement letters to meet monthly targets. Never pay any money until your legal counsel verifies the sanction letter.
- Official Bank Letterhead: Must be on official bank paper. It must have a reference number, corporate email. And manager signature.
- Exact Debtor Details: Must show your full legal name, PAN. And exact loan account number without mistakes.
- Full Debt closure: Must confirm that paying the settlement amount closes the loan completely with no balance remaining.
- Direct Account payment: Pay only into your own official loan account via net banking, NEFT. or bank counters. Never send money to an agent's UPI.
Under RBI Circular RBI/2023-24/60, lenders must issue an official No Dues Certificate (NDC) within 30 days of settlement payment. They must also update CIBIL, Experian, Equifax. and CRIF to show zero balance. Any delay beyond 30 days incurs a legal penalty of ₹5,000 per day.
CIBIL Bureau Reporting Dynamics & Credit Score Rehabilitation
After settlement, credit bureaus mark the account as "Settled" with an outstanding balance of ₹0. This stops monthly score erosion. With a secured card and timely payments, debtors rebuild credit scores above 750 in 18 to 24 months.
9. Virtual Calling Legal Defense Matrix
Evaluating these response strategies helps debtors take decisive legal action:
| Action Strategy. | Legal Foundation. | Protection Level. | Expected Timeline. | Final Legal Effect. |
|---|---|---|---|---|
| App Blocking (Truecaller). | Local device number filter. | Fails against rotating virtual numbers. | Continuous. | No debt relief. Calls resume from new numbers. |
| DoT Chakshu Portal Filing. | DoT Fraud Team & TRAI TCCCPR. | High. Triggers telecom audit and number blocking. | 7 – 15 Days. | Shuts down calling pool. Creates legal proof. |
| RBI Banking Ombudsman. | RBI Integrated Ombudsman Scheme, 2021. | Enforces Fair Practices Code against the bank. | 30 – 45 Days. | Orders bank to stop misconduct with payout. |
| Advocate Notice & 55% OTS. | Principal-Agent Liability & OTS Contract. | Immediate. Halts calls and collection visits. | 15 – 30 Days. | Full debt closure with 45%–65% waiver and ₹0 NDC. |
10. SettleLoans Digital Harassment Defense
Stopping virtual number calls needs expert banking lawyers. SettleLoans provides complete legal defense across India. We preserve digital evidence and file complaints on DoT Chakshu and RBI portals. We settle 45% to 65% loan waivers with authentic No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
11. FAQs: Virtual Numbers, Auto-Dialers & Legal Remedies
Clear, verified answers to key questions about virtual calls, VoIP dialers, DoT Chakshu complaints. And debt settlement in India.
Is it legal for recovery agents to call from unknown virtual numbers or VoIP auto-dialers?
No. Under TRAI rules and RBI Master Directions, recovery calls must come from 140-xxx or 160-xxx numbers. Using 10-digit mobile SIMs or VoIP virtual lines to bypass blocking is illegal.
How do recovery agencies use auto-dialers and virtual numbers to bypass Truecaller?
Collection agencies use cloud SIP trunking and automated dialers linked to large pools of virtual numbers. When a number is flagged as spam on Truecaller, the system switches to a new caller ID. This creates non-stop calls without revealing the agency's true name.
What is the Department of Telecommunications (DoT) Chakshu portal and how does it help?
Chakshu is a citizen reporting tool on the Government of India Sanchar Saathi portal at sancharsaathi.gov.in. It helps users report fraud calls and recovery abuse via SMS, WhatsApp. And calls. Reporting virtual numbers leads to telecom KYC checks and permanent SIM blocking.
How can I preserve digital evidence from disappearing WhatsApp messages and VoIP calls?
To preserve evidence under Section 63 of Bharatiya Sakshya Adhiniyam, take full screenshots. Make sure the phone number, date. And text are visible. Save chat exports and get Call Detail Records (CDR) from your mobile operator.
Can the lending bank be held legally responsible for illegal calls made by third-party recovery agencies?
Yes. Under Section 182 of the Indian Contract Act, banks are liable for their recovery agents. The RBI Outsourcing rules also hold lenders fully responsible. Banks cannot excuse illegal collection acts.
What sections of the Information Technology Act apply to recovery agent spoofing and virtual number threats?
Using spoofed virtual numbers violates Section 66D of the IT Act. It carries up to 3 years in jail. Sharing debtor data with dialer apps also violates Sections 43A and 72A.
What are the permissible calling hours for debt recovery agents under RBI directives?
The RBI strictly allows recovery calls only between 8:00 AM and 7:00 PM. Calls, robocalls. or WhatsApp messages received before 8:00 AM or after 7:00 PM violate the RBI Fair Practices Code.
How does digital harassment provide leverage to negotiate a One-Time Settlement (OTS)?
When lawyers submit evidence of TRAI and RBI violations, lenders face huge fines. Bank leaders act quickly to avoid ombudsman fines. They halt collection calls and approve a 45% to 65% OTS.
Should I transfer funds directly to UPI IDs or links provided by recovery callers on WhatsApp?
Never. Rogue agents often share personal UPI handles or QR codes to take funds. All settlement payments must go directly into your official loan account. Pay via net banking, NEFT. or bank counters after getting a sanction letter.
What is the mandatory RBI timeline for issuing a No Dues Certificate after completing a settlement?
Under RBI Circular RBI/2023-24/60, lenders must issue a No Dues Certificate (NDC) within 30 days of settlement payment. They must also update CIBIL and other bureaus to show zero balance. Delays beyond 30 days incur a penalty of ₹5,000 per day payable to the debtor.