- Civil Dispute Nature. Unsecured loan default is a civil contract breach under the Indian Contract Act, 1872. Local police cannot arrest you for debt defaults.
- Anti-Harassment Shield. RBI rules ban recovery visits in Chowk, Godowlia, and Thatheri Bazar. Agents cannot call before 8 AM or after 7 PM. They cannot call relatives.
- Varanasi Kutchery Defense. Our advocates appear in court for Section 138 NI Act and Section 25 PSSA summons under Vakalatnama. We secure bail fast and stop recovery.
- DLSA Lok Adalat Decrees. Settlements signed at DLSA Lok Adalat act as Civil Court decrees under Section 21 Legal Services Act 1987. Banks cannot appeal.
- Deep Debt Waivers. Borrowers get 40% to 70% principal cuts. Banks drop all penal fees. You get a formal No Dues Certificate in 30 days.
1. Debt Landscape & Borrowers in Varanasi & Eastern UP
Varanasi links trade across Prayagraj, Gorakhpur, Bhadohi, Mirzapur, and Jaunpur. The city relies on Banarasi silk weaving. Major wholesale saree hubs include Chowk, Thatheri Bazar, Madanpura, and Godowlia. Hotels and tour operators near the Ghats also drive local commerce.
Local businesses face cash crunches and slow sales. To stay open, silk traders take unsecured personal loans. Salaried staff at BHU, MGKVP, and BLW also face debt stress from medical costs.
When EMIs bounce, banks send harsh collection agents. These agents visit shops and threaten families. They also give false police threats. Our advocates use RBI rules and court remedies to shield borrowers.
2. Statutory Protections for Varanasi Borrowers
Loan default is a civil breach of contract under the Indian Contract Act, 1872. It is not a crime. The RBI Fair Practices Code sets strict debt recovery rules.
Recovery agents cannot visit you before 8 AM or after 7 PM. They cannot use abuse or threats. They cannot call friends, family, or business clients. Agents must show IIBF cards and bank ID.
We send a Cease-and-Desist Notice to the bank. This notice stops agent visits. The bank must deal in writing with our advocates.
Section 60(1) CPC protects basic home items, clothes, and weaver tools from court seizure. It also protects minimum wage amounts. Lenders cannot take property without a court order. Forced seizure is illegal trespass under BNS and IPC.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Varanasi Kutchery, District Courts & Police Jurisdiction
Collection agents often make false threats of police arrest or court warrants. You must know your rights at Varanasi District Court (Varanasi Kutchery at Orderly Bazar / Shivpur Road). Civil debt is separate from criminal law.
Police in Sigra, Cantt, Bhelupur, and Chowk cannot arrest you for unpaid loans. Supreme Court rulings in Lalita Kumari v. Government of U.P. and Arnesh Kumar v. State of Bihar bar police in loan defaults. If agents threaten police action, our advocates file complaints for criminal intimidation.
Banks usually file two types of court cases in Varanasi District Court:
If an EMI cheque bounces, the bank gives a 15-day notice. Then they file a case in Varanasi Kutchery. Cheque bounce is bailable by law. Under Section 147 of the NI Act, you can settle and compound the case at any time.
When NACH auto-debits bounce, banks file cases under Section 25 of the Payment and Settlement Systems Act, 2007. Our advocates appear under Vakalatnama. We get bail and move the case to Lok Adalat.
For loans under ₹20 Lakhs, banks cannot go to DRT in Prayagraj. The RDB Act 1993 sets a ₹20 Lakh minimum. Lenders must file Order 37 CPC suits in civil court. These suits take 3 to 5 years. This delay helps us win deep OTS discounts.
4. Bank Accounting Realities in Varanasi
Understanding RBI rules helps you get big loan cuts. When you miss EMIs, banks tag loans as SMA-0, SMA-1, or SMA-2. Past 90 days, the loan becomes an NPA.
NPA rules force banks to set aside cash reserves. Banks must set aside 15% for Substandard NPAs, up to 40% for Doubtful Assets, and 100% for Loss Assets. This locks bank funds. Lenders offer One-Time Settlements to free up this capital.
Our advocates submit an OTS file to the Settlement Committee. The bank compares fast OTS cash with slow civil suits using an NPV formula:
Where C_t is expected recovery and r is discount rate. Court fees and locked NPA funds reduce bank returns.
Unsecured loans have no pledged property for SARFAESI auction. Civil suits in Varanasi take years and cost high stamp fees. Showing high Net Present Value wins our clients 40% to 70% principal cuts.
5. Visual Blueprint: The Complete Eastern UP Loan Settlement
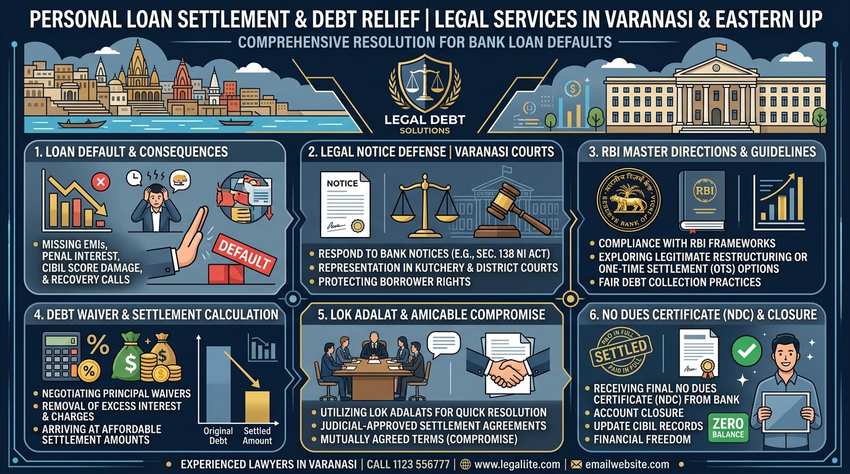
The diagram below shows the loan settlement steps in Varanasi, Prayagraj, and Gorakhpur. It covers hardship audits, court defense, OTS talks, and No Dues Certificates via DLSA Lok Adalat:
6. Strategic One-Time Settlement (OTS) Negotiation Framework
A good OTS requires clear steps, loan audits, and direct talks. Dealing alone with agents brings false promises. Informal token payments get lost as extra fees. Our advocates follow 4 clear stages:
Stage 1: Loan Ledger Audit. We audit your bank statements. We remove illegal penal interest and bounce charges under RBI Circular RBI/2023-24/53. This resets your debt to pure principal.
Stage 2: Hardship File. Banks require proof of financial distress. We submit audited accounts. These show sales drops for silk traders, GST falls, medical bills, or job loss letters.
Stage 3: Zonal Desk Talks. We bypass local recovery agents. Our advocates negotiate directly with bank Zonal desks in Varanasi. These include SBI at Kutchery Road and Bank of Baroda at Orderly Bazar. Union Bank at Sigra and PNB at Maldahiya are also included.
Stage 4: Sanction Letter. When terms are agreed, the bank issues a formal OTS sanction letter. We verify all terms to ensure full debt closure and case withdrawal.
7. Varanasi DLSA Lok Adalat Settlement
The National Lok Adalat is the best place to settle personal loans in Eastern UP. It is run by DLSA Varanasi at the Kutchery court complex in Orderly Bazar.
Lok Adalats are statutory forums under the Legal Services Authorities Act, 1987. Both pre-litigation notices and pending Section 138 NI Act cases can be settled here.
Settling your loan through the Varanasi DLSA Lok Adalat offers four key legal benefits:
Status of a Final Civil Court Decree
Under Section 21 of the Legal Services Authorities Act 1987, a Lok Adalat award acts as a civil court decree. It closes the loan permanently.
Absolute Bar on Future Appeals
Banks cannot appeal a Lok Adalat award in District Court, Allahabad High Court, or Supreme Court. The loan is closed forever.
Automatic Criminal Compounding
In Section 138 NI Act and Section 25 PSSA cases, Lok Adalat orders act as compounding decrees under Section 147 NI Act. All court cases are dropped.
Zero Court Fees & Full Fee Refund
Lok Adalat sessions are free. If a pending civil suit is settled here, court fees are refunded under the Court Fees Act, 1870.
8. Sanction Letter Forensics & NDC in Varanasi
A loan settlement needs two documents: a Bank Sanction Letter and a No Dues Certificate (NDC). Agents sometimes send fake letters on WhatsApp. We verify every paper before you pay:
Key Terms in OTS Letter. The letter must come on official bank letterhead with a reference number. It must have the seal and signature of an authorized manager. It must state your name, loan number, agreed settlement sum, and payment schedule. It must confirm case withdrawal.
RBI 30-Day NDC Rule. Under RBI Circular RBI/2023-24/60, banks must issue your No Dues Certificate within 30 days of final payment. If delayed, the bank must pay you ₹5,000 per day.
CIBIL Score Repair. The bank reports your status as "Settled" with ₹0 dues across CIBIL, Experian, CRIF High Mark, and Equifax. This stops penal fees and bad reporting. You can rebuild your CIBIL score to 750+ within 18 to 24 months with a secured credit card.
9. Court Trial vs. Advocate-Led OTS in Varanasi
When facing bank legal notices in Varanasi Kutchery, compare contested court litigation against an advocate-led OTS:
| Strategic Parameter | Contested Civil Court Litigation | Advocate-Led OTS & Lok Adalat Settlement |
|---|---|---|
| Resolution Horizon | 3 to 6 years in civil and High Court. | 45 to 90 days from hardship filing to final NDC. |
| Financial Exposure | Full debt + high penal interest + rising court costs. | 40% to 70% debt waiver; penal interest is waived. |
| Court Appearances | Frequent personal appearances for trials and hearings. | Appearance through advocate under Vakalatnama. |
| Recovery Harassment | Ongoing collection calls and shop visits. | Completely stopped through formal legal notices. |
| Legal Finality | Subject to appeals, revisions, and execution petitions. | Final Civil Decree under Section 21 Legal Services Act. |
| Credit Bureau Impact | Active 'Suit Filed' status with damaged credit score. | Updated to 'Settled' with ₹0 dues on your file. |
10. SettleLoans Legal Defense in Varanasi
SettleLoans provides complete legal defense for silk traders, hotel owners, and salaried staff in Varanasi, Prayagraj, and Gorakhpur. Our advocates stop agent harassment with cease-and-desist notices. We defend Section 138 NI Act and Section 25 PSSA cases in Varanasi Kutchery. We also secure 40% to 70% bank OTS cuts with official No Dues Certificates and DLSA Lok Adalat decrees.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Varanasi
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Varanasi can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Kachehri, Circuit House Road, Varanasi, Uttar Pradesh - 221002
Jurisdiction: Oversees loan recovery summary suits and cheque bounce litigation for weavers, local traders, and salaried consumers across Purvanchal.
Address: ADR Centre, District Court Campus, Kachehri, Varanasi - 221002
Lok Adalat Conciliation: Permanent Lok Adalat and mediation cells facilitate amicable one-time settlements, halting aggressive third-party agent visits.
11. FAQs: Varanasi & Eastern UP
Clear answers to key questions about personal loan settlement, court defense, and borrower rights in Varanasi.
Why do silk traders, business owners, and salaried employees in Varanasi need specialized loan settlement advocates?
Varanasi is the main commercial hub of Eastern UP. Silk traders in Chowk, Godowlia, and Thatheri Bazar often face cash flow issues. Hospitality operators and salaried staff at BHU and DLW also face debt stress. When loans default, banks send recovery agents to your shop or home. Our Varanasi advocates invoke RBI rules to stop agent visits. We reply to court notices at Varanasi Kutchery. We also negotiate One-Time Settlements (OTS) with 40% to 70% waivers.
Can Varanasi Police arrest me or file a criminal FIR for an unpaid personal loan or credit card debt?
No. Loan default is a civil dispute under the Indian Contract Act, 1872. Police stations in Sigra, Cantt, Bhelupur, and Chowk have no power to arrest you for unpaid loans. Under Supreme Court rulings in Lalita Kumari and Arnesh Kumar, civil defaults cannot become criminal cases. If recovery agents threaten police action, our advocates file complaints with the Police Commissioner and District Magistrate.
How do I handle a Section 138 NI Act or Section 25 PSSA summons from Varanasi District Court (Kutchery)?
Do not ignore court summons from Varanasi Kutchery. Banks file cheque bounce cases under Section 138 NI Act or NACH bounce cases under Section 25 PSSA. You can appear through an advocate under Vakalatnama and secure bail quickly. Cheque bounce is compoundable under Section 147 NI Act. We refer the matter to Lok Adalat to close the case permanently upon paying the agreed OTS.
How does the District Legal Services Authority (DLSA) Lok Adalat in Varanasi finalize loan settlements?
DLSA Varanasi holds regular Lok Adalats at the Kutchery court complex. A judicial bench reviews pre-litigation disputes and pending court suits. Once an OTS is reached, the bench issues a formal Lok Adalat Award. Under Section 21 of the Legal Services Authorities Act, 1987, this award acts as a final Civil Court decree. The lender cannot appeal it, and the debt is closed permanently.
Can banks freeze or auto-debit my business or salary accounts in other banks in Varanasi?
Banks can only set off funds in their own branches under Section 171 of the Indian Contract Act. They cannot freeze your accounts in other banks in Varanasi, Prayagraj, or Gorakhpur without a court order under Section 60 or Order 38 Rule 5 CPC. Our advocates help protect your operating accounts.
What percentage of debt waiver can borrowers in Eastern UP expect during bank OTS negotiations?
Unsecured loans overdue past 90 to 180 days qualify for 40% to 70% debt waivers. Banks first remove 100% of penal interest and late fees. Our advocates then negotiate deep principal cuts based on your documented hardship.
Can borrowers residing across Prayagraj, Gorakhpur, Bhadohi, or Jaunpur settle their loans remotely through Varanasi advocates?
Yes. SettleLoans assists borrowers across Varanasi, Prayagraj, Gorakhpur, Bhadohi, Mirzapur, and Jaunpur. Our advocates audit your loan ledgers, draft legal replies, and talk directly with bank Zonal SARB desks. We also represent you at DLSA Lok Adalat sessions.
What is the mandatory RBI timeline for lenders to issue a No Dues Certificate (NDC) post-settlement?
Under RBI Circular RBI/2023-24/60, lenders must issue your No Dues Certificate within 30 days of full settlement. If the bank delays beyond 30 days, it must pay you compensation of ₹5,000 per day of delay.