- Centralized PSU Recovery Hubs. PSU banks in Patna transfer unpaid personal loans to SARB and SASTRA centers. These units handle aggressive recovery.
- legal RBI Compromise Framework. The RBI Master Direction of June 8, 2023 allows compromise settlements. All banks and NBFCs in Bihar can offer OTS terms.
- BSLSA National Lok Adalat Power. Quarterly Lok Adalats at Patna Civil Court provide binding settlement awards. Borrowers get 100% penal fee waivers.
- Criminal Harassment Shields. Abusive recovery calls and home threats violate RBI fair practice rules. Borrowers can report rogue agents to Patna Police.
- Mandatory 30-Day NDC Delivery. Lenders must issue a No Dues Certificate within 30 days. Delays require ₹5,000 daily payout under RBI rules.
1. Banking & Default Landscape in Patna and Greater Bihar
Patna is Bihar's economic hub. Retail credit has grown fast. Major bank branches line Boring Road, Fraser Road, and Kankarbagh. PSU lenders dominate the market. SBI, PNB, Bank of Baroda, and Canara Bank lead retail loans. Private banks and NBFCs issue loans too.
Many local families face financial stress. Wholesale traders in Marufganj face cash flow drops. Salaried workers suffer job cuts and high medical bills. These hardships lead to loan defaults.
When defaults happen, banks rarely offer easy options. Instead, recovery agents call often and send harsh notices. Panicking makes things worse. You need structured legal defense.
Our loan settlement services in Patna, Bihar protect your rights. We stop recovery harassment. We audit improper interest charges. We negotiate affordable OTS terms directly with bank managers.
2. PSU Bank SARB Architecture & Legal Paths
PSU banks in Bihar use dedicated recovery units. When a loan is unpaid for 90 days, it becomes an NPA. The account moves to zonal recovery hubs.
In Patna, SBI runs its SARB near Gandhi Maidan. PNB operates its SASTRA Center at Exhibition Road. Canara Bank and Bank of Baroda run recovery offices too. They focus on recovery through legal notices.
Banks in Patna follow a clear legal path:
If a cheque bounces, the bank sends a 15-day notice. Bank advocates then file criminal cases. They appear before the Judicial Magistrate at Patna Civil Court.
When NACH or ECS auto-debits bounce, lenders file Section 25 cases. These carry quasi-criminal liability.
Lenders file summary suits at Patna Civil Court. The borrower must apply for court leave to defend the claim.
Private lenders often start one-sided arbitration. They seek ex-parte awards under Section 36 of the Arbitration Act.
Agents often threaten property seizure under SARFAESI Act, 2002. This is false. SARFAESI applies only to secured loans. Unsecured personal loans and cards cannot trigger SARFAESI action.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Borrower Legal Protections in Patna
Loan default is a civil matter, not a crime. RBI rules protect honest borrowers from abuse. The Supreme Court and Patna High Court uphold your rights.
Lenders in Patna must obey the RBI Fair Practices Code. They must follow recovery agent guidelines:
- Time and Place Restrictions. Agents can call only between 8:00 AM and 7:00 PM. Unannounced visits without prior notice are illegal.
- Absolute Privacy Protections. Lenders cannot share loan details with neighbors, bosses, or relatives. Creating social pressure groups is illegal.
- Prohibition of Verbal Abuse and threats. Threats and abuse break the law. They violate Section 351 and Section 352 of BNS, 2023.
- Mandatory Agent Identification. Recovery agents must show bank ID cards. They must carry formal authorization letters.
Facing recovery abuse in Bihar? File a police complaint in Patna, Gaya, or Muzaffarpur. Alert the Patna SSP or local police. Our advocates send legal notices to bank nodal officers. We report violations to the RBI Integrated Ombudsman.
4. NPA Balance Sheet Accounting in Patna
A 40% to 60% waiver needs financial logic, not emotions. Banks use RBI reserves rules and Net Present Value (NPV) models.
Banks follow RBI IRACP norms. They must reserve capital against bad loans:
| Asset status. | default Aging. | Mandatory RBI Provision (Unsecured). | Balance Sheet Financial Impact. | Target Settlement Haircut. |
|---|---|---|---|---|
| Standard / SMA-0 to SMA-2. | 1 – 90 Days Overdue. | 0.40% – 5.0%. | Normal operational provision. | Penal charge waivers only. |
| Sub-Standard Asset. | 91 Days – 12 Months NPA. | 25% Unsecured Provision. | Direct profit deduction. | 20% – 35% Principal Haircut. |
| Doubtful-1 (D1 Asset). | 12 – 24 Months Default. | 100% Full reserves. | Full loan amount locked. | 35% – 50% Principal Haircut. |
| Doubtful-2 / Doubtful-3. | 24 – 48+ Months Default. | 100% Full reserves. | High balance sheet drag. | 45% – 60% Principal Haircut. |
| Loss Asset. | Identified Uncollectible. | 100% Written-off Asset. | Fully written off in books. | 55% – 70% Principal Haircut. |
When an unsecured loan turns Doubtful or Loss, the bank locks 100% capital. This hurts bank profits. Under the RBI Master Direction of June 8, 2023, bank committees use this formula:
Here, C_t is future recovery. The letter r is the discount rate. Deductions cover court delays, legal fees. And capital costs.
When our team presents a lump-sum cash offer, the bank saves legal costs. A 50% settlement today gives more value than five years of court cases.
5. Settlement Process Roadmap in Patna
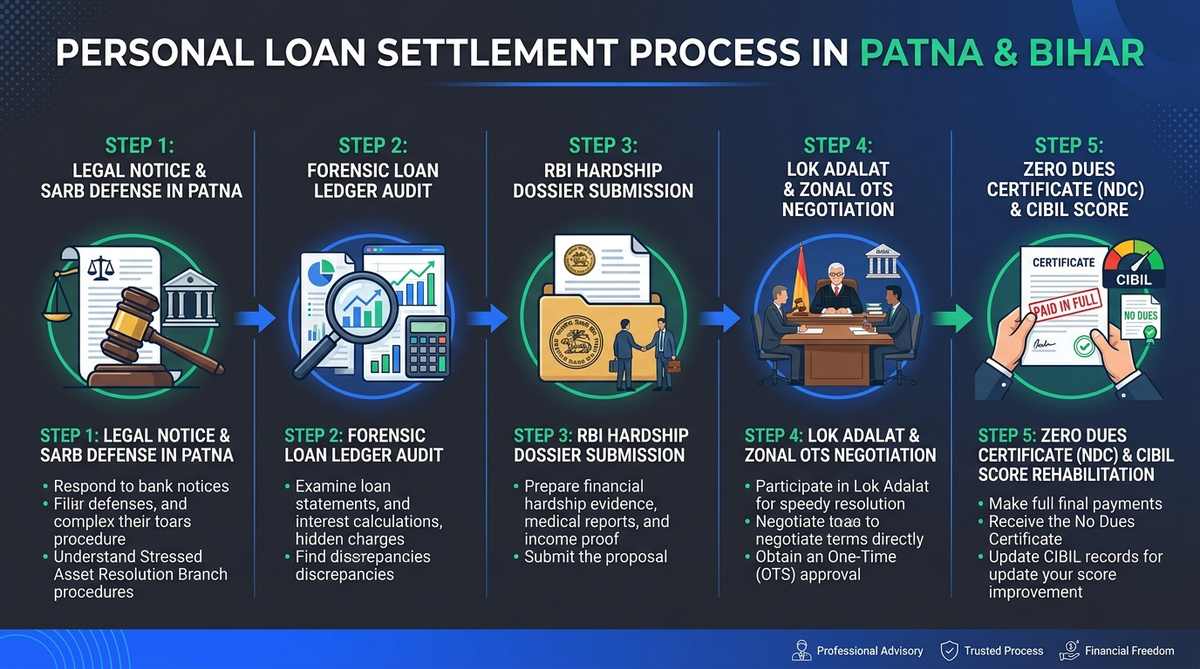
The roadmap below shows 5 key steps to settle bank loans in Patna. Learn to defend against notices. Secure an OTS waiver. Rebuild your credit score.
6. Advocate-Led Settlement Framework in Patna & Bihar
Settling bank debt requires a clear legal strategy. Negotiating alone brings risks. Agents make false verbal promises. Our legal team uses a proven 5-phase framework:
Phase 1: Forensic Loan Ledger & Legal Audit
We collect full loan statements from the bank. We review the account in detail. We remove illegal penal fees and compound interest. This gives us the true principal baseline.
Phase 2: Formal Legal Representation & Anti-Harassment Notice
We submit a formal Vakalatnama to the bank zonal head. This moves all messages to our legal office. It stops agents from visiting your home or workplace.
Phase 3: Hardship Dossier Submission Under RBI June 2023 Policy
We draft a compromise petition under RBI rules. We attach proof of financial hardship. This includes income tax returns, medical records, or business loss proofs.
Phase 4: Bilateral Zonal Negotiation & Discretionary Approval
Our advocates negotiate directly with the Bank Zonal Committee in Patna. We use NPA reserves rules. We secure 40% to 60% principal waivers. We also structure a 1-to-3 installment payment plan.
Phase 5: Execution of Consent Decree & Legal Closure
Are Section 138 or Section 25 cases pending? We record consent terms at Patna Civil Court or Lok Adalat. All court cases get dismissed.
This structured approach makes your settlement permanent and legally binding.
7. Patna DLSA Lok Adalat Representation
Lok Adalats are key forums for debt settlement in Bihar. The BSLSA organizes quarterly National Lok Adalats. Benches sit at Patna Civil Court, Gaya, Muzaffarpur, and Bhagalpur.
Lok Adalats run under the Legal Services Authorities Act, 1987. Special benches resolve bank recovery cases quickly.
Settling in Patna Lok Adalat offers key legal benefits:
- Final and Binding Judicial Award. Under Section 21, a Lok Adalat award acts as a civil decree. It is final. No party can appeal it.
- Full Refund of Court Fees. Lok Adalat settlements refund court fees in full. This follows the Court Fees Act, 1870.
- optional Bank Waivers. Bank zonal heads at Lok Adalat hold high approval powers. They can waive 100% penal interest and grant deep principal discounts.
For debts above ₹20 Lakhs, banks approach DRT Patna near Exhibition Road. Our advocates defend borrowers at DRT Patna. We challenge inflated claims. We secure court-approved settlements.
8. Sanction Letter Audit & NDC in Patna
Rogue agents in Bihar sometimes issue fake settlement letters. They make false verbal promises to collect money. Never pay without a verified sanction letter.
Before paying, our advocates check five key points:
The letter must come from the bank's corporate email. Or it must bear the Zonal Manager's signed letterhead.
The letter must show your 16-digit account number. It must list total debt, waiver amount. And net payable sum.
The letter must confirm full closure upon payment. Your balance must become ₹0.
The letter must promise to withdraw all court cases. This includes Section 138 and Section 25 suits.
Never pay cash to recovery agents. Pay via Demand Draft or NEFT/RTGS into your official loan account. Always collect a bank receipt.
RBI Statutory Mandate on 30-Day NDC Delivery & Credit Bureau Updates
Under RBI Circular RBI/2023-24/60, banks in Bihar must issue an NDC in 30 days. They must return security cheques. Any delay costs the bank ₹5,000 per day in borrower payout.
The bank reports the account to credit bureaus. CIBIL, CRIF, Experian, and Equifax show the loan as "Settled". The balance becomes ₹0. This stops negative default marks. You can rebuild credit to 750+ in 12 to 18 months with a secured card.
9. Debt Resolution Matrix for Patna Borrowers
Compare debt relief choices in Patna. Find the best balance of savings and safety:
| Resolution Pathway. | Legal Mechanism &. Forum. | Principal Haircut Potential. | Resolution Timeline. | Key Legal &. Credit Impact. |
|---|---|---|---|---|
| Advocate-Led Zonal OTS. | Direct talks with Bank Zonal Committee (SAMC). | 40% – 60% Principal Waiver. | 45 – 90 Days. | Full legal closure. zero liability. ₹0 No Dues Certificate. |
| National Lok Adalat Settlement. | settlement bench under Legal Services Act. | 35% – 55% Principal Waiver. | Single Session. | Binding civil decree. court fee refund. no future appeals. |
| Contested Court Litigation. | Civil Court / DRT Patna legal defense. | 0% (Full Claim + Legal Fees). | 3 – 7 Years. | High legal costs. long delays. risk of asset attachment. |
| Debt Reschedulement / Restructuring. | Loan tenure extension / EMI moratorium. | 0% (Full Debt Repayable). | 30 – 60 Days. | No principal relief. higher total interest cost over time. |
| Unmanaged Loan Default. | Inaction &. ignoring legal notices. | 0% (Rising Penal Charges). | Indefinite. | Severe recovery harassment. Section 138 criminal summons. |
10. SettleLoans Legal Relief in Patna & Bihar
Facing heavy debt in Bihar? You need skilled legal help. SettleLoans helps borrowers resolve bank, NBFC. And microfinance debt.
Our banking advocates audit loan statements. We stop recovery harassment with legal notices. We represent you at Patna Lok Adalat and courts. We secure high OTS waivers with ₹0 No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Patna
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Patna can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Bank Road, Near Gandhi Maidan, Patna, Bihar - 800004
Jurisdiction: Trial courts handle Section 138 cheque dishonor cases, NBFC digital app disputes, and civil summary recovery petitions.
Address: ADR Bhavan, Civil Court Premises, Bank Road, Patna - 800004
Lok Adalat Conciliation: Empowers borrowers under Bihar State Legal Services Authority (BSLSA) to settle debt with full interest and penalty waiver decrees.
11. FAQs: Patna, Bihar
Find clear legal answers for Patna. Learn about SARB notices, Lok Adalat terms. And borrower rights.
Can I legally settle an unsecured personal loan or credit card debt in Patna, Bihar?
Yes. Debt settlement is completely legal in Patna. It follows the RBI Master Direction of June 8, 2023. This rule covers banks and NBFCs across Bihar. Borrowers with genuine hardship can apply for an OTS. Lenders can waive penal interest. They also discount the core principal balance.
What is an SBI SARB or PNB SASTRA notice, and how should borrowers in Bihar respond?
SARB and SASTRA are PSU bank recovery wings. When loans stay unpaid past 90 days, accounts move here. A SARB notice means the bank plans legal action. Never ignore these formal notices. An advocate must send a prompt reply. This stops harassment and starts compromise talks.
How does the National Lok Adalat in Patna Civil Court facilitate debt settlement?
Bihar State Legal Services Authority organizes regular Lok Adalats. Benches sit at Patna Civil Court and district courts. Judges and senior advocates guide the talks. Lenders offer deep compromise discounts here. Agreements become binding court awards under Section 21. There are zero court fees and no future appeals.
What legal protections exist against aggressive recovery agent harassment in Patna?
Borrowers have strong protections under RBI rules. Agents cannot call before 8 AM or after 7 PM. They cannot contact friends or relatives. Abusive language and threats are strictly banned. Violations break Section 351 of Bharatiya Nyaya Sanhita. You can file a police complaint in Patna. You can also alert the RBI Ombudsman.
What percentage of debt waiver can borrowers in Bihar expect during a personal loan OTS?
Banks in Patna evaluate loan age and borrower distress. They routinely waive 100% of penal interest. They also waive unpaid late fees. On core principal, waivers range from 35% to 60%. Unsecured loans in Doubtful or Loss stages get the highest discounts.
How does personal loan settlement differ from SARFAESI proceedings in Bihar?
SARFAESI Act applies only to secured loans with mortgaged property. It never applies to unsecured personal loans or credit cards. For unsecured debt, banks cannot seize your home. They can only file civil suits or cheque bounce cases. An OTS settles unsecured debt safely.
Can microfinance (NBFC-MFI) and digital loan app debts be settled in Bihar?
Yes. Microfinance lenders and digital loan apps follow RBI guidelines. Lenders cannot use coercive group recovery tactics. SettleLoans advocates stop illegal collection agent calls. We negotiate lump-sum compromise closures directly with lender management.
What is the mandatory timeline for banks in Patna to issue a No Dues Certificate (NDC)?
Under RBI Circular RBI/2023-24/60, banks must issue an NDC in 30 days. They must return security cheques. Any delay costs ₹5,000 per day in borrower payout.
How does a loan settlement affect CIBIL scores, and how can borrowers in Bihar rebuild credit?
Credit bureaus mark settled accounts with ₹0 balance. This stops negative default marks. Rebuild credit with a secured card. Pay on time. Regain a 750+ score in 12 to 18 months.