- Centralized PSU Recovery Teams. Public sector banks in Ranchi send bad retail and personal loans to SARB and SASTRA cells for legal recovery.
- Statutory RBI Compromise Rules. Under the RBI Master Direction on Compromise Settlements (June 8, 2023), banks and NBFCs in Jharkhand can approve One-Time Settlements (OTS).
- JHALSA National Lok Adalat. Regular Lok Adalats at Ranchi Civil Court grant binding settlement orders with full penal fee waivers.
- Protection from Harassment. Home visits, office threats. And abuse violate the RBI Fair Practices Code. They are punishable under Bharatiya Nyaya Sanhita (BNS) with Ranchi Police.
- Mandatory 30-Day NDC Delivery. Under RBI Circular RBI/2023-24/60, lenders must issue a ₹0 No Dues Certificate within 30 days or pay a ₹5,000 daily penalty.
1. Banking & Default Landscape in Ranchi
Ranchi is the capital of Jharkhand. It hosts mining firms, steel offices. And transport hubs. Main Road, Doranda, Lalpur, Ashok Nagar, Morabadi, Hinoo, Namkum, Kanke Road, and Harmu have seen rapid growth in personal loans. Major banks like SBI, PNB, Bank of India, and Canara Bank operate here alongside private lenders and digital NBFCs.
Jharkhand relies heavily on industry. Many borrowers work for public sector units like CCL Ranchi, BCCL Dhanbad, CMPDI, SAIL Bokaro, MECON, and HEC Ranchi. Local vendors, coal truckers. And contractors also use personal loans to fund their work.
When payments stop due to slow bills or illness, loan default happens. Personal loans and credit cards become hard to pay. After 90 days of missed EMIs, banks mark accounts as Non-Performing Assets (NPAs) and start recovery.
Handling banks alone can lead to agent harassment and costly legal notices. A trusted personal loan settlement company in Ranchi, Jharkhand protects your rights. Our advocates help you get a formal One-Time Settlement (OTS) directly with bank zonal heads.
2. PSU Bank SARB Structure in Ranchi
Public sector banks in Jharkhand handle bad loans through centralized recovery hubs. When an unsecured personal loan defaults past 90 days, the branch transfers the file to a specialized stressed asset recovery wing.
In Ranchi, key recovery hubs include the State Bank of India Stressed Assets Recovery Branch (SARB) near Kutchery and Main Road. Another major center is the Punjab National Bank Circle SASTRA office. Bank of India and Canara Bank also run regional recovery cells at Club Road. These teams manage bad loan recovery across Ranchi, Khunti, Ramgarh, Gumla, and Lohardaga.
Bank recovery units in Jharkhand follow a set legal path to recover money:
When cheques bounce, bank lawyers send a 15-day notice. If unpaid, they file criminal cases in Ranchi Civil Court or district courts across Jharkhand.
For dishonored NACH or auto-debit payments, lenders file cases that carry the same legal weight as cheque bounce cases.
Banks file these suits before Ranchi Civil Court judges for fast debt decrees. Borrowers must apply for court leave to defend.
Private lenders and NBFCs often start arbitration on their own. They appoint sole arbitrators to get fast awards under Section 36 of the Arbitration and Conciliation Act.
Recovery agents in Ranchi, Dhanbad, and Jamshedpur often threaten home seizure under the SARFAESI Act, 2002 for personal loans. In law, SARFAESI applies only to secured loans backed by a registered mortgage. Unsecured personal loans are fully exempt from SARFAESI property takeovers.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Borrower Legal Protections in Ranchi
Loan default is a civil matter, not a crime. The RBI, the Supreme Court of India. And the High Court of Jharkhand at Ranchi hold that banks cannot use force against borrowers.
Banks and NBFCs in Ranchi, Jamshedpur, Bokaro, and Dhanbad must follow clear rules. These are set by the RBI Master Direction on Fair Practices Code for Lenders and the RBI Guidelines on Recovery Agents (August 2022):
- Time and Place Limits. Agents cannot call or visit before 8:00 AM or after 7:00 PM. Unannounced visits to your home or office are unlawful.
- Workplace Privacy. Lenders cannot share loan details with bosses, coworkers, or family. They cannot contact neighbors in CCL, BCCL, or SAIL townships.
- No Threats or Abuse. Agents cannot threaten arrest or police action. Using abusive words violates Section 351 and Section 352 of Bharatiya Nyaya Sanhita, 2023 (formerly Sections 503 and 506 IPC).
- Agent ID Proof. Every recovery agent must carry a bank ID card. They must show the bank authorization letter when asked.
Salaried staff in Jharkhand have strong legal protection under Section 60 of the Code of Civil Procedure (CPC), 1908. Under Section 60(1)(i), the first one thousand rupees and two-thirds of the remaining salary are exempt from civil court attachment. Under Section 60(1)(k), Provident Fund (PF), Gratuity. And pensions cannot be attached by any court or lender.
If agents break these rules in Ranchi, Jamshedpur, or Dhanbad, file a complaint. You can report them to the Senior Superintendent of Police (SSP) Ranchi, your local Thana, or the Cyber Cell. Our lawyers also send legal notices to bank nodal officers. We file formal complaints with the RBI Integrated Ombudsman under the 2021 scheme.
4. NPA Balance Sheet Accounting in Ranchi
Securing a 40% to 60% principal waiver in Ranchi is not about emotional appeals. It rests on bank accounting rules, RBI provisioning rules, and Net Present Value (NPV) recovery math.
Under the RBI Master Direction on Prudential Norms (IRACP), banks in Jharkhand must set aside capital from their profits for bad loans:
| Asset Classification. | default Aging. | Mandatory RBI Provision (Unsecured). | Balance Sheet Financial Impact. | Target Settlement Haircut. |
|---|---|---|---|---|
| Standard / SMA-0 to SMA-2. | 1 – 90 Days Overdue. | 0.40% – 5.0%. | Mild operational provision. | Penal fee waivers only. |
| Sub-Standard Asset. | 91 Days – 12 Months NPA. | 25% Unsecured Provision. | Direct profit deduction. capital cost. | 20% – 35% Principal Haircut. |
| Doubtful-1 (D1 Asset). | 12 – 24 Months Default. | 100% Full Provisioning. | Total loan value locked. | 35% – 50% Principal Haircut. |
| Doubtful-2 / Doubtful-3. | 24 – 48+ Months Default. | 100% Full Provisioning. | Locked Tier-1 capital. audit pressure. | 45% – 60% Principal Haircut. |
| Loss Asset. | Identified Uncollectible. | 100% Written-off Asset. | Fully written off on balance sheet. | 55% – 70% Principal Haircut. |
When an unsecured personal loan in Ranchi becomes a Doubtful or Loss asset, the bank has already set aside 100% of the funds in reserve. This locked capital hurts the bank's Capital to Risk-Weighted Assets Ratio (CRAR). Bank credit committees review OTS offers using the Net Present Value formula. This follows the RBI Master Direction on Compromise Settlements and Technical Write-offs (June 8, 2023):
Here, C_t is the expected future cash recovery. The letter r is the bank discount rate. Deductions cover 3 to 5 years of court delay in Ranchi Civil Courts, lawyer fees. And balance sheet drag.
Our lawyers present a verified cash settlement offer. The bank's math shows that accepting 50% cash today gives more value. It beats fighting an unsecured claim for five years in Jharkhand courts.
5. Loan Settlement Roadmap in Ranchi
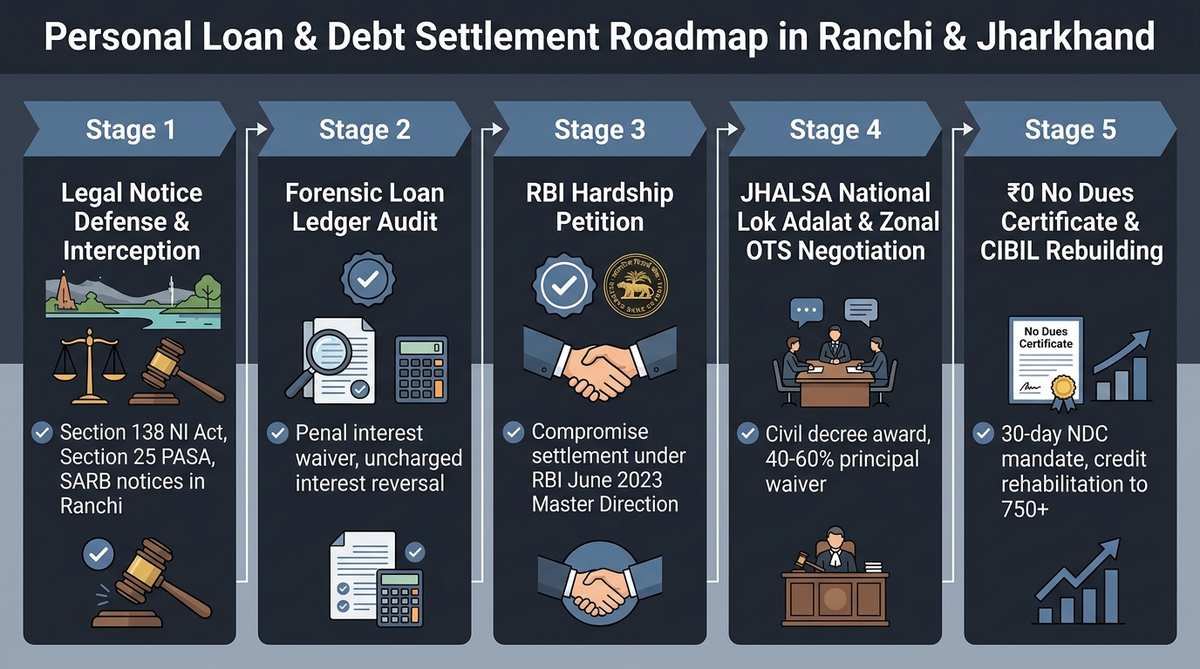
The roadmap below shows the 5-step legal process to settle bank loans in Ranchi, Jamshedpur, Dhanbad, and Jharkhand. It covers notice defense, Lok Adalat talks, No Dues Certificate delivery, and CIBIL score repair.
6. Advocate-Led Settlement Framework in Ranchi & Jharkhand
A good loan settlement requires a clear legal strategy. Dealing with banks without a lawyer leaves borrowers open to agent pressure and broken verbal deals. Our legal team follows a proven 5-phase debt settlement process in Ranchi and Jharkhand:
Phase 1: Forensic Loan Ledger & Legal Audit
We obtain complete account statements from the bank's Ranchi branch or SARB cell. We audit the ledger to strip away illegal penal interest and extra fees to find the real baseline principal.
Phase 2: Formal Legal Representation & Anti-Harassment Notice
We serve a formal Vakalatnama and legal notice to the bank's Zonal Head and Nodal Officer. This directs all future calls to our legal team and stops recovery agent visits.
Phase 3: Hardship Dossier Submission Under RBI June 2023 Policy
We draft an OTS petition under the bank's board policy and RBI rules. We attach strong proof like income tax returns, medical bills, business losses, or bank statements.
Phase 4: Bilateral Zonal Negotiation & Discretionary Approval
Our lawyers meet directly with the bank's Zonal Stressed Assets Management Committee (SAMC) in Ranchi. Using NPA aging rules, we seek a 40% to 60% principal waiver with easy installments.
Phase 5: Execution of Consent Decree & Legal Closure
For active Section 138 NI Act or Section 25 PASA cases, we file consent terms in Ranchi Civil Court or Lok Adalat. This closes all court cases.
This legal process ensures that every rupee you pay goes toward closing your loan under clear statutory rules.
7. Lok Adalat Settlements in Ranchi
Lok Adalat is a helpful legal forum for debt resolution in Jharkhand. The Jharkhand State Legal Services Authority (JHALSA) holds quarterly National Lok Adalats in all 24 districts. These include Ranchi Civil Court, Jamshedpur, Dhanbad, and Bokaro.
Lok Adalats function under the Legal Services Authorities Act, 1987. Benches with a judge and an advocate conciliator help resolve bank loan disputes.
Settling a loan through Lok Adalat in Ranchi has key advantages:
- Binding Court Decree. Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat award is equal to a civil court decree. It is final and cannot be challenged in any court.
- Full Refund of Court Fees. When a civil suit or Section 138 case settles in Lok Adalat, court fees are refunded under the Court Fees Act, 1870.
- High Fee Waivers. PSU bank zonal managers at Lok Adalat hold high waiver powers. They can grant 100% penal interest waivers and large principal discounts on the spot.
For debts above ₹20 Lakhs with commercial loans or guarantees, banks file cases before the Debts Recovery Tribunal (DRT) Ranchi near Kutchery. Our lawyers represent borrowers before DRT Ranchi. We file replies, halt coercive steps. And structure fair settlements.
8. Sanction Letter Audit & NDC in Ranchi
A major risk in debt settlement across Jharkhand is fake settlement letters. Rogue recovery agents often share fake letters on duplicate bank letterheads or make false verbal promises to collect money for themselves.
Before you pay any money, our legal team verifies the settlement letter against five strict checks:
The sanction letter must come from the bank's official email domain. It must be signed by the Zonal Head (AGM or Chief Manager).
The letter must list your 16-digit loan account number, total ledger dues, waiver amount. And final settlement sum.
The terms must state that paying the agreed sum closes the loan in full with zero balance left.
The letter must state that the bank will drop all Section 138 NI Act, Section 25 PASA. And arbitration cases.
Never pay cash to any collection agent or third party. Always pay by Account Payee Demand Draft or direct RTGS/NEFT into your loan account against an official bank receipt.
RBI Statutory Mandate on 30-Day NDC Delivery & Credit Bureau Updates
Under RBI Circular RBI/2023-24/60, all commercial banks and NBFCs in Jharkhand must issue an official No Dues Certificate (NDC). They must also return original papers within 30 calendar days of receiving full settlement payment. If the lender delays without valid cause, it must pay the borrower payout of ₹5,000 per day of delay.
The bank must also update credit bureaus (CIBIL, CRIF High Mark, Experian, and Equifax) with a status of "Settled" or "Post-Write-off Settled" with an outstanding balance of ₹0. While this temporarily impacts credit scores, it stops ongoing default marks. Borrowers can rebuild their CIBIL score to 750+ within 12 to 18 months through careful credit card use.
9. Debt Resolution Matrix in Ranchi
Borrowers in Ranchi should compare their debt relief choices to find the best balance of cost savings and legal protection:
| Resolution Pathway. | Legal Mechanism &. Forum. | Principal Haircut Potential. | Resolution Timeline. | Key Legal &. Credit Impact. |
|---|---|---|---|---|
| Advocate-Led Zonal OTS. | Direct talks with Bank Zonal Committee (SAMC). | 40% – 60% Principal Waiver. | 45 – 90 Days. | Cleanest closure. complete legal immunity. ₹0 No Dues Certificate. |
| JHALSA Lok Adalat Settlement. | Conciliation bench under Legal Services Authorities Act. | 35% – 55% Principal Waiver. | Single Session. | Binding civil decree. zero court fees. permanent bar on suits. |
| Contested Court Litigation. | Civil Court Ranchi / DRT Ranchi Section 19 defense. | 0% (Full Claim + Legal Fees). | 3 – 7 Years. | High legal costs. long court delays. asset attachment risk. |
| Debt Reschedulement / Restructuring. | Tenure extension / EMI moratorium recalculation. | 0% (Full Debt Repaid). | 30 – 60 Days. | No principal relief. higher total interest over longer term. |
| Unmanaged Loan Default. | Inaction and ignoring statutory demand notices. | 0% (Rising Penal Charges). | Indefinite. | Harsh recovery visits. criminal cases under Section 138 NI Act. |
10. SettleLoans Legal Relief in Ranchi & Jharkhand
Resolving heavy bank debt in Ranchi, Jamshedpur, Dhanbad, and Bokaro needs skilled legal support. SettleLoans is a top debt relief advisory in Jharkhand. We defend borrowers against aggressive PSU recovery teams and private collection agents.
Our banking advocates review loan files and send legal notices to stop harassment. We represent clients at Ranchi Civil Court and JHALSA Lok Adalat benches. We negotiate directly with bank zonal committees to secure large OTS waivers and official ₹0 No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Ranchi
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Ranchi can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Kutchery Chowk, Morabadi Road, Ranchi, Jharkhand - 834001
Jurisdiction: Judicial Magistrate First Class benches adjudicate Section 138 cheque return trials, Section 25 PSSA notices, and police mediation on collection abuse.
Address: Nyaya Sadan, Civil Court Campus, Kutchery, Ranchi - 834001
Lok Adalat Conciliation: Supervised by Jharkhand State Legal Services Authority (JHALSA), conducting Lok Adalat compromise hearings with enforceable decree issuance.
11. FAQs: Loan Settlement in Ranchi
Here are clear answers about loan settlement, SARB notices, JHALSA Lok Adalat. And borrower rights in Jharkhand.
Can I legally settle an unsecured personal loan or credit card debt in Ranchi, Jharkhand?
Yes. Settling a personal loan or credit card in Ranchi is fully legal. The process follows the RBI Master Direction on Compromise Settlements (June 8, 2023). Public sector banks, private banks, and NBFCs across Jharkhand can approve One-Time Settlements (OTS) for borrowers in genuine financial distress. The bank waives penal interest, extra fees. And a large share of the principal.
What is an SBI SARB or PNB SASTRA notice, and how should borrowers in Jharkhand respond?
SARB (Stressed Assets Recovery Branch) and SASTRA are special recovery wings run by PSU banks like SBI and PNB in Ranchi. When a loan is overdue for over 90 days, the branch sends the file to SARB. A SARB notice means the bank is ready for legal action. Never ignore this notice. Send an advocate-drafted reply right away to stop recovery pressure and start OTS talks.
How does the JHALSA National Lok Adalat in Ranchi Civil Court facilitate debt settlement?
The Jharkhand State Legal Services Authority (JHALSA) holds quarterly National Lok Adalats in Ranchi Civil Court, Jamshedpur, Dhanbad, and Bokaro. Sitting judges and senior lawyers preside over these benches. They help borrowers and bank officials reach a fair compromise. Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat award is final and legally binding. There are no court fees. And banks offer maximum fee waivers.
Are PSU and government employees in Jharkhand protected against unlawful salary attachment for personal loans?
Yes. Section 60 of the Code of Civil Procedure (CPC), 1908 protects staff of CCL, BCCL, CMPDI, SAIL, HEC, railways. And state offices. The law bans the attachment of the first thousand rupees and two-thirds of the rest of your salary. Also, Provident Fund (PF), gratuity. And pensions are fully safe from attachment.
What legal protections exist against aggressive recovery agent harassment in Ranchi and the mining belt?
Borrowers in Jharkhand are protected under the RBI Fair Practices Code. Recovery agents cannot call or visit before 8:00 AM or after 7:00 PM. They cannot call your family, visit your workplace, or enter PSU housing colonies without consent. For violations, file a complaint with the Senior Superintendent of Police (SSP) Ranchi under Section 351/352 of Bharatiya Nyaya Sanhita (BNS) and raise a grievance with the RBI Ombudsman.
What percentage of debt waiver can borrowers in Jharkhand expect during a personal loan OTS?
Waivers depend on loan delay, hardship proof. And whether the debt is unsecured. Banks in Ranchi routinely waive 100% of penal charges and late fees. They also offer a 35% to 60% waiver on the principal balance. When a loan reaches Doubtful (D1/D2) or Loss asset status, the bank has already provisioned for the loss. This allows deeper discounts.
Can mining contractors and MSME suppliers in Jharkhand settle unsecured business loans and personal credit lines?
Yes. Mining contractors, vendors. And small business owners in Ranchi, Ramgarh, Dhanbad, and Jamshedpur can settle unpaid credit lines. If you face cash flow issues from delayed client bills, our lawyers draft compromise requests with bank records, tax returns. And contract proof.
What is the mandatory timeline for banks in Ranchi to issue a No Dues Certificate (NDC)?
Under RBI Circular RBI/2023-24/60, all banks and NBFCs must issue a No Dues Certificate (NDC) and return original papers within 30 days of receiving full settlement payment. If the lender delays without cause, it must pay the borrower ₹5,000 for each day of delay.
How does personal loan settlement affect CIBIL scores, and how can borrowers in Jharkhand rebuild credit?
After settlement, the bank reports the account to CIBIL and CRIF High Mark as 'Settled' with a ₹0 balance. This stops negative monthly reporting. Borrowers can rebuild their score above 750 within 12 to 18 months by taking a secured credit card against a fixed deposit and paying on time.