- Merged Bank Setup: Union Bank runs one core system. It includes old Andhra Bank and Corporation Bank loans.
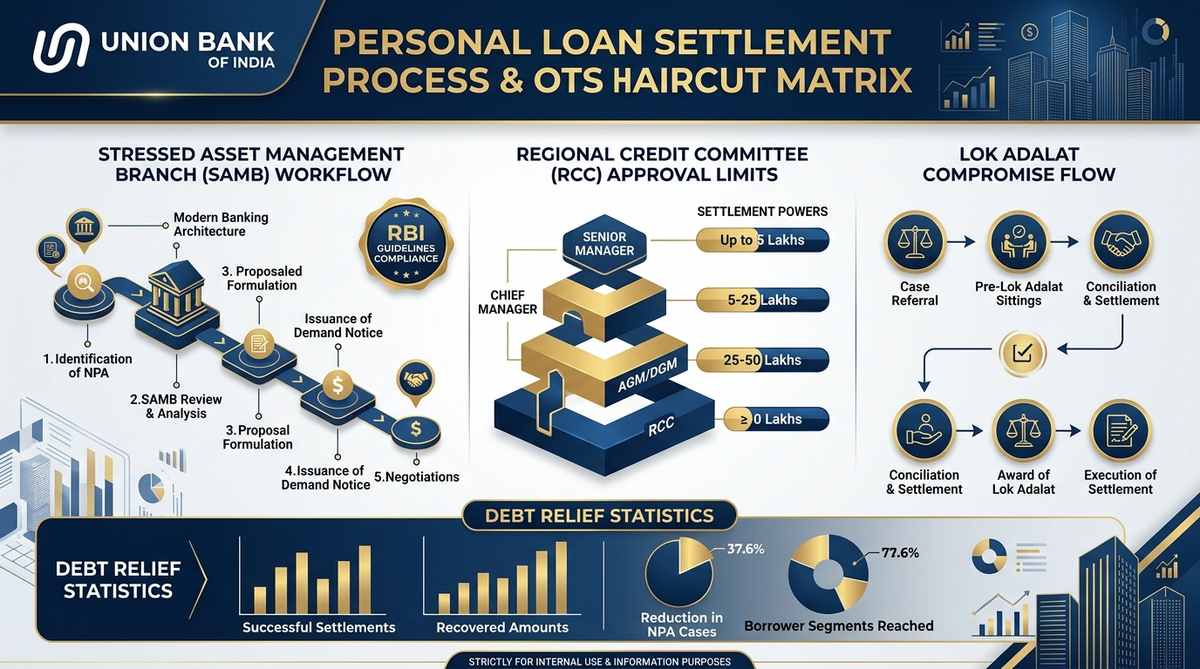
- SAMB Desk Resolution: Loans past 90 days default move to SAMB desks and Regional Credit Committees (RCC).
- 40% to 60% Haircut: Older NPA accounts qualify for 40% to 60% principal write-offs. All penal interest is removed.
- Lok Adalat Finality: Lok Adalat orders act as final Civil Court Decrees under Section 21 of the Legal Services Authorities Act, 1987.
- 30-Day NDC Rule: Under RBI Circular RBI/2023-24/60, the bank must issue a ₹0 No Dues Certificate within 30 days.
Navigating Retail Loan Default
Union Bank merged with Andhra Bank and Corporation Bank. It is now a large public bank. All loans run on one system.
Union Bank follows strict CVC and CAG rules under the Banking Companies Act, 1970. Staff cannot make oral deals. Every waiver needs clear written proof of hardship.
From Base Branch Delinquency to Stressed Asset Management
Union Bank tracks unpaid dues in three stages. These are SMA-0 (1–30 days), SMA-1 (31–60 days), and SMA-2 (61–90 days). After 90 days of default, the loan becomes an NPA.
Auto-calls and branch SMS alerts ask you to pay the overdue EMI right away.
Collection agents call more often. Penal fees and late charges get added.
Interest stops adding to the account. The file moves to the SAMB recovery desk.
Between Day 90 and Day 120, your loan moves to the Stressed Asset Management Branch (SAMB). Base branch staff cannot grant cuts. But SAMB officers hold power to review files. They can approve 40% to 60% principal waivers.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Banker's Right of General Lien, CIF Auto-Sweeps, and
Under Section 171 of the Indian Contract Act, 1872, Union Bank holds a general lien. The bank can debit your savings or deposits in Union Bank to cover unpaid dues.
- Internal UBI Accounts: Savings and deposits in any Union Bank branch can be debited by the bank.
- External Banks Safe: Union Bank cannot touch accounts in other banks like SBI, HDFC, or ICICI.
- Court Order Needed: To freeze outside accounts, the bank needs a civil court order under Order 38 Rule 5 CPC.
If you face default, move your salary account to another bank. This keeps your living funds safe while your lawyer negotiates an OTS.
Defending Sec 25 PSSA & Sec 138 NI Act
During default, Union Bank sends statutory notices. Knowing your legal defense helps you stop court risks:
Section 25 of the Payment and Settlement Systems Act, 2007 (PSSA)
Sent when NACH auto-debits bounce. You get 15 days to reply. A lawyer reply shows hardship. It halts court action and opens OTS talks.
Section 138 of the Negotiable Instruments Act, 1881 (NI Act)
Sent for bounced cheques. A lawyer reply under Section 147 NI Act turns the dispute into an OTS settlement.
SARFAESI Act Inapplicability on Unsecured Loans
SARFAESI rules apply only to secured loans like home loans. Union Bank cannot take your home for personal loans without a civil decree.
Union Bank of India Settlement Workflow & Approvals
Union Bank OTS Policy & Valuation Rules
Union Bank settles loans using Net Present Value (NPV). SAMB officers weigh fast cash against slow court trials. Quick cash is worth more than long trials:
Here C_t means cash recovered over time. The letter r is the discount rate. The formula cuts out legal costs and bad loan provisions.
Penal Waivers: 100% Elimination
Unpaid penal interest, extra penalty rates, late fees. And bounce charges are 100% waived in an approved OTS.
Principal Haircut: 40% to 60%
Based on default age (Doubtful or Loss), real hardship cases get a 40% to 60% principal waiver.
Procedural Stages and Delegation of Financial Powers
Forensic Loan Audit
Get your full loan account statement. Separate the core principal from extra penalty charges.
Hardship Dossier Compilation
Gather proof of money loss. Collect medical bills, job layoff letters, or business closure records with a sworn affidavit.
Submission to Competent Authority
Submit your petition to the right authority: Chief Manager (up to ₹5L), AGM (up to ₹25L), RCC (up to ₹50L), or ZCC (above ₹50L).
Sanction Letter Verification & Payment
Verify the stamped OTS sanction letter on bank letterhead before you pay money into your loan account.
Resolving Union Bank Defaults via Statutory Lok Adalat
Union Bank refers bad loans to National Lok Adalat benches set up by NALSA. Bank officers carry pre-set limits. They can offer 45% to 60% principal waivers on the spot.
Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat award is a final Civil Court Decree. No appeal lies against it. It ends all claims by the bank permanently.
Verifying Bank Letterhead Sanctions, ₹0 NDC Mandate, and
Mandatory Clauses in an Authentic UBI OTS Letter
- Official Stationery: Printed on Union Bank letterhead with branch seal, date. And officer signature.
- Full Debt closure: Confirms that the agreed sum pays off the loan in full.
- Litigation Withdrawal: Guarantees the bank will drop Section 25 PSSA, Section 138. And civil suits.
- Credit Reporting: Confirms the bank will update CIBIL status to 'Settled&apos. with a ₹0 balance.
Under RBI Circular RBI/2023-24/60, Union Bank must issue your ₹0 No Dues Certificate within 30 days. Any delay costs the bank ₹5,000 per day paid to you. You can raise your credit score past 750 in 18 to 24 months with a secured card.
Comparing Debt Resolution Pathways
| Resolution Parameter. | Unassisted Individual. | Outsourced Recovery Agent. | SettleLoans Legal Advocacy. |
|---|---|---|---|
| Authority Level. | Branch Clerk (No Powers). | Tele-Caller (Zero Authority). | SAMB Head / Regional Credit Committee. |
| Average Haircut. | 10% – 20% (Interest Only). | 0% – 15% (Unverified). | 40% – 60% Principal &. Charges. |
| Harassment Defense. | None. calls continue. | Severe field pressure. | Immediate Cease-and-Desist Notice. |
| Notice Defense (Sec 25/138). | Unrepresented. | Not provided. | Formal Advocate Legal Reply. |
| Sanction Letter. | Informal email. | High fraud risk. | Stamped Bank Letterhead Sanction. |
| NDC &. CIBIL Closure. | Prolonged office delay. | No follow-up. | Enforced 30-Day RBI NDC Delivery. |
Expert Legal Representation for Union Bank Loan Settlement
SettleLoans offers expert legal help for Union Bank loans. We stop agent harassment fast. We deal directly with SAMB desks to secure top waivers.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: Union Bank of India Personal Loan Settlement
What is the Union Bank of India personal loan settlement process and how does it operate?
Union Bank loan settlement is a formal compromise process. It follows bank policy and RBI rules. After 90 days of default, a loan turns into an NPA. The case moves to the SAMB desk. The borrower files a hardship dossier. The Regional Credit Committee (RCC) reviews it. After approval, UBI issues an OTS Sanction Letter. Paying this sum closes the loan with a ₹0 No Dues Certificate.
How does the tripartite merger of Andhra Bank and Corporation Bank into Union Bank affect loan settlements?
Andhra Bank and Corporation Bank loans now run on Union Bank systems. All settlements follow Union Bank rules. Old default age counts toward loan loss provisions. This helps older loans get 40% to 60% principal cuts.
What percentage of debt haircut does Union Bank of India typically approve on unsecured personal loans?
Union Bank often approves 40% to 60% principal waivers on bad loans. Also, all unpaid penal interest and bounce fees are completely waived under an approved OTS.
What is the role of Stressed Asset Management Branches (SAMB) and Regional Credit Committees (RCC)?
Local branch managers cannot waive loan principal due to audit rules. Defaulted loans past 90 days move to SAMB units. SAMB officers verify financial loss. They submit settlement files to the Regional Credit Committee (RCC) for approval.
Can Union Bank of India freeze or debit funds from other bank accounts under Section 171?
Under Section 171 of the Indian Contract Act, 1872, Union Bank holds a lien on internal accounts. It can debit savings in Union Bank, Andhra Bank, or Corporation Bank. But Union Bank cannot touch accounts in outside banks without a civil court order.
How does settling a personal loan through Union Bank's Special Lok Adalat OTS scheme work?
Union Bank joins National Lok Adalats organized by NALSA. Officers carry pre-set settlement grids. They offer 45% to 60% discounts. Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat award is a final Civil Court Decree. It closes the loan permanently.
How should borrowers respond to Section 25 PSSA and Section 138 notices from Union Bank of India?
When NACH debits or cheques bounce, Union Bank issues legal notices. Send an advocate reply within 15 days. Explain your financial hardship. Offer an OTS to prevent magistrate court cases.
Why is Union Bank of India's OTS process more formal than private banks and fintech apps?
As a PSU bank, Union Bank follows CVC and CAG rules. Every rupee of loan waiver needs clear audit proof. The file must prove real hardship and good recovery value for the bank.
What is the statutory timeline for Union Bank of India to issue the No Dues Certificate (NDC)?
Under RBI Circular RBI/2023-24/60, Union Bank must issue a ₹0 No Dues Certificate (NDC) within 30 days of full payment. Any delay brings a penalty of ₹5,000 per day paid to the borrower.
How does settling a Union Bank of India personal loan impact your CIBIL score and how can you rebuild it?
The loan status becomes 'Settled' with a ₹0 balance. This stops default growth but lowers your score initially. You can rebuild your credit score past 750 in 18 to 24 months with a secured credit card.