- Tier-Based Financial Powers: Branch Managers in Canara Bank have zero mandate for substantial principal waivers. Significant debt reductions (40% to 60%) require formal sanction from the Regional Head, Circle Office Credit Committee, or Head Office.
- SAMB Centralization: Defaulted retail loans past 90 days are escalated from Retail Asset Hubs (RAH) to Stressed Assets Management Branches (SAMB), where recovery officers evaluate Net Present Value (NPV) recovery versus court costs.
- 100% Penal Fee Waiver: Every sanctioned Canara Bank OTS unconditionally eliminates all accumulated penal interest, compounding late fees, and NACH bounce penalties, focusing negotiations strictly on principal balance recovery.
- National Lok Adalat Finality: Settlements executed through quarterly Lok Adalat benches carry the statutory weight of a non-appealable Civil Court Decree under Section 21 of the Legal Services Authorities Act, 1987.
- Enforceable 30-Day NDC Delivery: In compliance with RBI Circular RBI/2023-24/60, Canara Bank must issue an official stamped No Dues Certificate within 30 days of final payment, subject to a mandatory penalty of ₹5,000 per day for unlawful delays.
Navigating Retail Loan Default in Indias Third-Largest Public
Canara Bank represents one of the premier public sector financial institutions in India, significantly expanding its retail lending footprint following its mega-merger with Syndicate Bank. The bank oversees millions of retail credit facilities, including Canara Budget Personal Loans, Canara Payroll Packages for corporate and government employees, Canara Teachers Loans, and instant pre-approved digital credit lines disbursed through the Canara ai1 mobile banking platform. However, resolving a defaulted unsecured personal loan with Canara Bank involves procedural mechanisms entirely distinct from negotiating with private commercial lenders or digital fintech platforms.
As a Public Sector Undertaking (PSU) bank established under the Banking Companies (Acquisition and Transfer of Undertakings) Act, 1970, Canara Bank operates under strict regulatory scrutiny. Every banking officer and credit sanctioning authority is governed by oversight mechanisms established by the Central Vigilance Commission (CVC), the Comptroller and Auditor General (CAG) of India, and statutory provisions under the Prevention of Corruption Act, 1988 (POCA). Consequently, Canara Bank officials cannot offer discretionary or undocumented concessions. While private lenders frequently authorize collection agencies to make informal telephone settlement deals, public sector bankers require an irrefutable audit trail proving that a compromise settlement minimizes the bank's financial losses compared to years of expensive civil litigation.
Furthermore, Canara Bank structures its retail loan administration through specialized Retail Asset Hubs (RAH) and Centralized Processing Units. When default occurs, borrowers often face rigid procedural resistance at their local branch because local branch managers lack the administrative mandate to sacrifice loan principal. To achieve a favorable One-Time Settlement (OTS), distressed borrowers must understand Canara Bank's internal hierarchy, formulate an authenticated financial hardship dossier, and escalate the proposal to the appropriate administrative tier possessing statutory financial delegation.
The Non-Performing Asset (NPA) Lifecycle and Stressed Asset Management Division
When an equated monthly installment (EMI) on a Canara Bank personal loan is missed, the account enters a structured regulatory lifecycle governed by the Reserve Bank of India's Prudential Framework for Resolution of Stressed Assets. Delinquency is classified across progressive Special Mention Account (SMA) stages before reaching Non-Performing Asset (NPA) status:
Early-stage default. Managed by automated SMS reminders, Canara ai1 alerts, and tele-calling follow-ups from the base branch or Retail Asset Hub.
Critical credit stress. Collection calls escalate, field verification agents may visit residential addresses, and penal interest compounds on unpaid installments.
Account is officially classified as a Non-Performing Asset. Interest accrual is suspended, and the file is marked for transfer to specialized recovery branches.
The critical procedural turning point occurs once an account crosses the 90-day delinquency threshold and is designated as an NPA. In Canara Bank's administrative model, non-performing retail portfolios are transferred from local branches to specialized recovery divisions: the Stressed Assets Management Branch (SAMB) or the Circle Office Recovery Section.
This institutional transfer marks the ideal window for initiating compromise settlement discussions. While base branch managers are evaluated on branch profitability and audit compliance—making them highly hesitant to sanction principal waivers—SAMB recovery officers are tasked specifically with NPA reduction, bad debt write-downs, and capital recovery. They operate under formal Board-approved compromise policies and possess the administrative authority to recommend structured settlement terms to the Circle Credit Committee.
Moreover, under RBI provisioning norms, Canara Bank must allocate substantial capital provisions against aging NPAs. An unsecured Substandard loan (delinquent up to 12 months) requires a 15% provision. Once the debt transitions into Doubtful categories (D1: 25%, D2: 40%, D3: 100%) or Loss Asset status (100% written off), Canara Bank has already absorbed the loss on its balance sheet. Recovering 40% to 50% of the principal in immediate liquid funds allows the bank to reverse provisions and book a net profit recovery, creating powerful economic incentives for approving One-Time Settlements.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Banker's Right of General Lien, CIF-Linked Set-Offs, and Statutory Boundaries
A primary vulnerability for borrowers defaulting on a Canara Bank personal loan is the potential freezing or unauthorized debiting of their operational bank balances. This enforcement mechanism is executed under the legal doctrine of the Banker's Right of General Lien and Set-Off codified in Section 171 of the Indian Contract Act, 1872.
Under Section 171, in the absence of a contract to the contrary, a bank retains a statutory general lien over all monetary funds, deposits, and securities held by a customer against any outstanding debt due to the bank. Because Canara Bank operates a centralized Core Banking Solution (CBS) indexed by a unique Customer Information File (CIF) and Permanent Account Number (PAN), the bank's automated systems can automatically debit funds across accounts sharing the same CIF:
- Internal Canara Bank Accounts Vulnerable: Savings accounts, salary accounts, fixed deposits (FDs), recurring deposits (RDs), and credit balances across any Canara Bank branch nationwide can be lawfully attached or swept to offset delinquent personal loan dues.
- Third-Party Banks Are Legally Immune: Canara Bank possesses zero statutory authority to unilaterally attach, freeze, or sweep funds held in independent external banking institutions (such as State Bank of India, HDFC Bank, ICICI Bank, Punjab National Bank, or post office savings accounts).
- Mandatory Judicial Requirement: To attach funds maintained at external financial institutions, Canara Bank must file a formal civil recovery suit and secure an attachment before judgment under Order 38 Rule 5 of the Code of Civil Procedure, 1908 (CPC), which requires proving intentional fraudulent disposal of assets.
For individuals experiencing genuine financial hardship, protecting essential family living funds and medical liquidity is paramount. Borrowers must promptly redirect their salary credits and operational liquidity to an independent banking institution where no credit liabilities exist. This eliminates unauthorized automated sweeps and establishes financial stability while compromise negotiations are conducted with Canara Bank's recovery authorities.
Defending Against Section 25 PSSA, Section 138 NI Act, and SARFAESI Misconceptions
As a personal loan default persists beyond 90 to 120 days, Canara Bank initiates formal legal escalation through its panel of empanelled advocates by serving statutory legal demand notices. Understanding the precise legal scope of these notices empowers borrowers to respond effectively rather than reacting with undue anxiety:
Section 25 of the Payment and Settlement Systems Act, 2007 (PSSA)
When an automated National Automated Clearing House (NACH) mandate or electronic clearing mandate dishonours due to insufficient funds, Canara Bank issues a statutory demand notice under Section 25 PSSA. The statute provides a mandatory 15-day cure window from the date of receipt. While unaddressed notices may result in a complaint before a Judicial Magistrate, serving an advocate-drafted reply documenting genuine financial hardship, disputing penal calculations, and offering an amicable One-Time Settlement effectively halts magistrate court filings.
Section 138 of the Negotiable Instruments Act, 1881 (NI Act)
If security cheques provided during loan disbursement dishonour upon presentation, Canara Bank serves a statutory notice under Section 138 NI Act. Under Section 147 of the NI Act, cheque dishonour offenses are compoundable by law at any stage of proceedings. An advocate reply establishing absence of fraudulent intent and placing a compromise offer on record transitions the dispute from adversarial litigation into structured settlement negotiations.
Debunking SARFAESI Act Threats on Unsecured Personal Loans
Outsourced collection agents frequently issue unauthorized threats claiming Canara Bank will invoke Section 13(2) of the SARFAESI Act, 2002 to seal the borrower's home or seize household belongings. This is legally baseless. The SARFAESI Act applies strictly to secured credit facilities where an equitable or registered mortgage is created. For clean personal loans, Canara Bank has no collateral rights and cannot attach immovable property without filing a full civil recovery suit and obtaining a formal court decree over a multi-year judicial timeframe.
Borrowers must never leave statutory notices unanswered. Under the Indian Evidence Act, 1872, failure to reply to a formal legal notice can lead to an adverse judicial inference. A professional advocate reply sets out the borrower's bona fide defense on record, stops aggressive recovery agent harassment, and positions the file for fast-tracked compromise review at the Circle Office.
Canara Bank Personal Loan Settlement Process & Approval Hierarchy
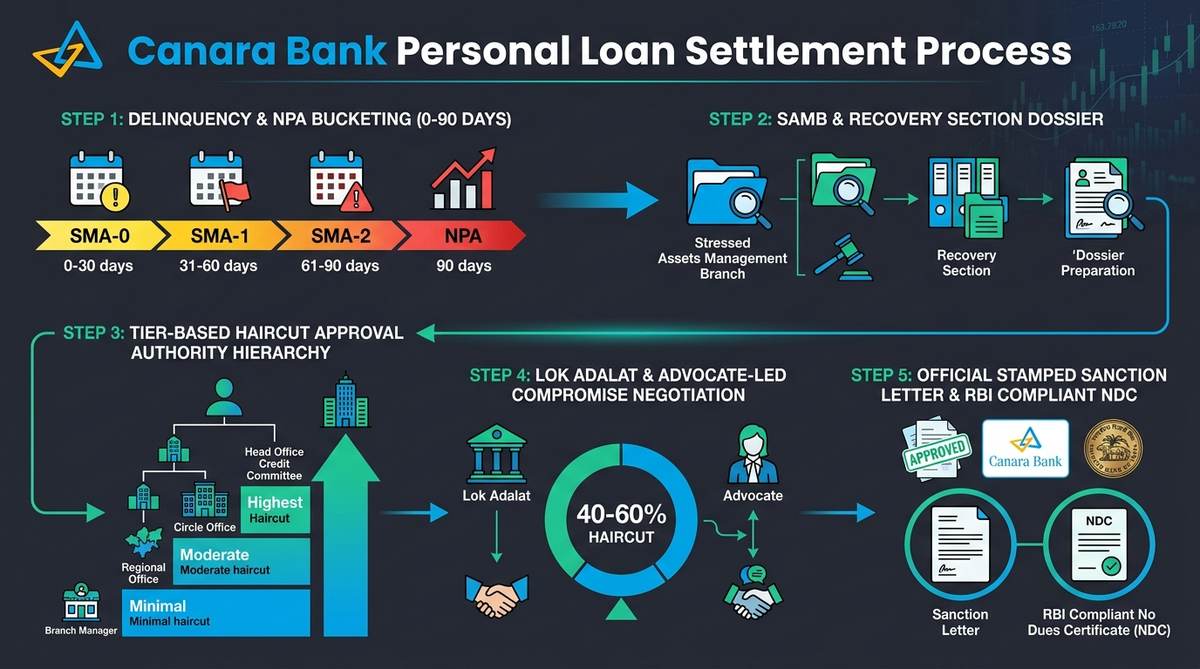
Canara Bank Compromise Policy Guidelines & Recovery Valuation
Canara Bank governs debt compromises under its Board-approved Policy on Compromise and Negotiated Settlement of NPAs, formulated in strict alignment with RBI Master Directions on Stressed Assets. The fundamental benchmark used by the bank to evaluate a compromise offer is the Net Present Value (NPV) Recovery Valuation.
When a recovery officer submits an OTS proposal to the Competent Authority, they must mathematically demonstrate that accepting an immediate lump-sum settlement or short-term installment plan yields a superior economic return compared to pursuing contested recovery through Civil Courts or Debt Recovery Tribunals (DRT). The valuation formula is expressed as:
Where C_t represents estimated recoveries over time, r is the discount rate (bank cost of capital), and deductions account for 3–5 years of judicial court friction, advocate fees, and locked capital provisioning.
Under this economic assessment, Canara Bank bifurcates debt concessions into two distinct categories:
Penal & Interest Waivers: 100% Elimination
All accumulated uncapitalized interest, compounding penal interest rates, late payment charges, NACH bounce penalties, and processing levies are 100% waived in all sanctioned settlements.
Principal Haircut: 40% to 60% Concession
Depending on NPA aging (Substandard, Doubtful, or Loss Asset) and authenticated insolvency documentation, borrowers qualify for a 40% to 60% principal write-off.
Delegation of Financial Powers (DOFP) and Fast-Track Settlement Roadmap
The most frequent obstacle borrowers encounter during Canara Bank loan negotiations is approaching the wrong administrative tier. Canara Bank enforces a rigid Delegation of Financial Powers (DOFP). Understanding which authority possesses the legal power to sanction your specific debt haircut is crucial for fast-tracking approval:
Canara Bank Financial Delegation Hierarchy for Personal Loan Compromises
Authority is restricted to waiving uncapitalized penal fees and granting short-term EMI restructuring. Branch Managers have zero mandate to grant substantial principal haircuts.
Empowered to sanction compromise settlements on personal loan exposures up to ₹15 Lakhs, with principal haircuts up to 35%–45% for seasoned Substandard and Doubtful accounts.
Sanction authority for retail exposures up to ₹50 Lakhs. Circle Heads can approve significant principal waivers (45% to 60%) based on comprehensive insolvency dossiers.
Supreme authority for high-value retail exposures and complex multi-facility NPA write-offs exceeding ₹50 Lakhs, approving deep haircuts under special recovery schemes.
Step-by-Step Advocate-Led Settlement Roadmap
Forensic Statement of Account (SOA) Audit
Extract complete loan account statements to segregate disbursed principal, total repayments made, true contractual balance, and unlawful compounding penal interest added post-default.
Insolvency Dossier Preparation & Sworn Affidavit
Assemble authenticated hardship documentation: medical records, job termination notices, salary reduction slips, GST surrender filings, or audited financial balance sheets showing business closure.
Direct Submission to Circle Office Recovery Section
Bypass base branch delays by formally submitting the OTS petition directly to the SAMB recovery officer and Circle Head, supported by legal precedent and NPV comparative models.
Sanction Letter Forensic Review & Secure Payment
Ensure Canara Bank issues a physical stamped OTS Sanction Letter on official bank letterhead. Remit funds strictly into your loan ledger and obtain immediate stamped bank deposit receipts.
Resolving Canara Bank Defaults via Statutory Lok Adalat Benches
For borrowers seeking absolute legal finality and maximum debt concessions, the National Lok Adalat represents the most secure resolution forum. Organized quarterly across India by the National Legal Services Authority (NALSA) and State Legal Services Authorities under the Legal Services Authorities Act, 1987, Lok Adalat benches provide an institutional platform for compromise settlements.
Canara Bank regularly refers non-performing retail portfolios to Lok Adalat pre-litigation benches to reduce gross NPA ratios ahead of statutory financial audits. During these sessions, Canara Bank authorizes attending recovery officers with pre-approved settlement grids, frequently enabling deeper haircuts (45% to 60% principal waivers) than individual branch discussions permit.
The primary benefit of a Lok Adalat compromise is its statutory legal enforceability:
Under Section 21 of the Legal Services Authorities Act, 1987, an award passed by a Lok Adalat is deemed to be a Decree of a Civil Court. The award is final and binding on both Canara Bank and the borrower. Crucially, under Section 21(2), no appeal shall lie to any court against the award of the Lok Adalat.
This statutory finality provides complete protection against future claims. Once the settlement amount specified in the Lok Adalat award is paid, Canara Bank is legally prohibited from reopening the loan account, selling residual balances to Asset Reconstruction Companies (ARCs), or pursuing pending Section 25 PSSA or Section 138 NI Act complaints.
Verifying Bank Letterhead Sanctions, ₹0 NDC Mandate, and Credit Repair
A loan settlement is only legally binding if supported by flawless documentation. Borrowers must perform rigorous legal forensics on any settlement letter provided by Canara Bank before making any payments:
Mandatory Clauses in an Authentic Canara Bank OTS Sanction Letter
- Official Letterhead & Bank Seal: Must be issued on authentic Canara Bank stationery bearing the SAMB/branch seal, official reference number, date, and signature of the authorized officer with their Employee Staff Code.
- Unambiguous Debt Extinguishment: Must explicitly state that the agreed settlement sum represents full and final settlement of all dues, and that all residual principal, interest, and penalties are unconditionally waived and extinguished.
- Mandatory Case Withdrawal Covenant: Must contain an explicit commitment that Canara Bank will unconditionally withdraw all pending legal notices, Section 25 PSSA complaints, Section 138 petitions, and civil suits upon clearance.
- Credit Bureau Reporting Commitment: Must state that Canara Bank will update credit bureaus (CIBIL, Experian, Equifax, CRIF High Mark) with the status 'Settled' or 'Post-Write-Off Settled' and an outstanding balance of ₹0.
Following complete payment, RBI Circular RBI/2023-24/60 imposes a binding statutory obligation: Canara Bank must issue a formal No Dues Certificate (NDC) / Loan Closure Certificate within 30 calendar days. If the bank fails to issue the NDC within 30 days without lawful reason, it is statutorily mandated to pay compensation of ₹5,000 for each day of delay directly to the borrower.
In terms of credit score trajectory, a 'Settled' remark leads to an immediate temporary credit score reduction of 75 to 150 points and a mandatory 12-month cooling window under RBI compromise frameworks. However, because the loan is marked closed with ₹0 outstanding balance, destructive ongoing DPD compounding ends immediately. By adopting a disciplined credit rebuilding strategy—securing a credit card backed by a fixed deposit, maintaining credit utilization below 30%, and ensuring prompt repayments—borrowers systematically restore their CIBIL score to 750+ within 18 to 24 months.
Comparing Resolution Pathways: Self-Negotiation vs. Collection Channels vs. Legal Advocacy
The strategic method selected by a distressed borrower determines whether their Canara Bank settlement succeeds or results in unfulfilled assurances. The following matrix highlights the operational differences across resolution approaches:
| Resolution Parameter | Unassisted Individual | Outsourced Recovery Agent | SettleLoans Legal Advocacy |
|---|---|---|---|
| Authority Level Engaged | Local Branch Officer (No Waiver Powers) | Third-Party Tele-Caller (No Authority) | SAMB Head / Circle Credit Committee |
| Average Haircut Achieved | 10% – 20% (Interest Waiver Only) | 0% – 15% (Often Misrepresented) | 40% – 60% Principal & Charge Waiver |
| Harassment Defense | None; persistent calls continue | Severe; aggressive field visits | Immediate Cease-and-Desist Notice |
| Notice Reply (Sec 25/138) | Ignored or unrepresented | Not provided | Formal Advocate Statutory Reply |
| Sanction Letter Integrity | Uncertain; often informal email | High risk of fake / unapproved text | Verified Stamped Bank Letterhead |
| NDC & CIBIL Closure | Frequent administrative delays | No post-payment follow-up | Enforced 30-Day RBI NDC Delivery |
Expert Legal Representation for Canara Bank Loan Resolution
Resolving a defaulted Canara Bank personal loan requires deep knowledge of public sector banking regulations, CVC compliance requirements, SAMB administrative hierarchies, and magistrate court litigation procedures. SettleLoans provides end-to-end legal and financial representation, shielding your family from recovery harassment and securing authentic, legally binding bank sanctions.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
Frequently Asked Questions on Canara Bank Personal Loan Settlement
What is the Canara Bank personal loan settlement process and how does it work?
The Canara Bank personal loan settlement process is a structured compromise resolution governed by Canara Bank's Board-approved Compromise Settlement Policy and RBI Prudential Regulations. When an unsecured personal loan defaults past 90 days and turns into a Non-Performing Asset (NPA), recovery jurisdiction shifts from the base branch or Retail Asset Hub (RAH) to the Stressed Assets Management Branch (SAMB) or Circle Office Recovery Section. The borrower submits a formal One-Time Settlement (OTS) proposal with documented financial hardship. The Competent Authority (Regional Manager, Circle Head, or General Manager) evaluates the proposal against Net Present Value (NPV) recovery benchmarks. Once sanctioned, Canara Bank issues a stamped OTS Sanction Letter, and settlement remittance into the loan account extinguishes all outstanding liabilities, culminating in a ₹0 No Dues Certificate.
Why can't local Canara Bank branch managers approve high loan settlement haircuts?
Under Canara Bank's internal Delegation of Financial Powers (DOFP) and public sector governance guidelines enforced by the Central Vigilance Commission (CVC), Scale-I to Scale-III Branch Managers possess minimal to zero discretionary authority to write off loan principal. Branch Managers are strictly audited on gross recoveries and can only waive minor delayed interest or penal fees. Substantial principal haircuts (40% to 60%) require the approval of the Assistant General Manager at the Regional Office, Deputy General Manager / Chief General Manager at the Circle Office, or the Head Office Credit Committee.
What percentage of debt haircut is typically approved in a Canara Bank personal loan settlement?
On unsecured personal loans and clean retail facilities, Canara Bank typically sanctions principal haircuts between 40% and 60% of the contractual ledger balance for seasoned NPAs. Furthermore, 100% of accrued uncapitalized interest, penal interest, late payment surcharges, and NACH dishonour penalties are completely waived. The exact percentage depends on the NPA classification age (Substandard, Doubtful D1/D2/D3, or Loss Asset), existing provisioning coverage, and authenticated insolvency evidence.
Can Canara Bank freeze or sweep money from my savings accounts under Section 171?
Under Section 171 of the Indian Contract Act, 1872 (Banker's General Lien and Right of Set-Off), Canara Bank possesses the legal power to freeze, hold, or sweep balances from any savings account, fixed deposit, recurring deposit, or current account maintained with Canara Bank under the same Customer Information File (CIF) or PAN. However, Canara Bank has zero statutory authority to unilaterally freeze or debit funds maintained in external banks (such as SBI, HDFC, ICICI, or PNB) without an explicit attachment order from a competent Civil Court or DRT.
How does settling a Canara Bank personal loan through National Lok Adalat provide judicial finality?
Under Section 21 of the Legal Services Authorities Act, 1987, an award passed by a National Lok Adalat is deemed to be a Decree of a Civil Court. It is final, binding, and completely non-appealable under Section 21(2). When a Canara Bank personal loan is settled in Lok Adalat, the compromised terms carry the force of law, ensuring that the bank is legally precluded from reopening the ledger, initiating fresh litigation, or assigning residual dues to third-party recovery agencies.
How should borrowers handle Section 25 PSSA and Section 138 notices from Canara Bank?
When NACH auto-debit mandates or repayment cheques bounce, Canara Bank's empanelled legal counsel serves statutory notices under Section 25 of the Payment and Settlement Systems Act, 2007 (PSSA) or Section 138 of the Negotiable Instruments Act, 1881. Borrowers must never ignore these notices. A formal advocate reply drafted within the mandatory 15-day cure window setting out genuine hardship, contesting erroneous penal charges, and placing an OTS compromise proposal on record halts magistrate court proceedings and accelerates settlement discussions.
Can Canara Bank seize residential property for an unsecured personal loan default?
No. The SARFAESI Act, 2002 applies exclusively to secured loans backed by registered or equitable mortgages. Unsecured personal loans carry no collateral charge. Canara Bank cannot seize, seal, or auction immovable property without first filing a protracted civil recovery suit, obtaining a money decree, and initiating execution proceedings—a process taking 3 to 7 years in Indian civil courts.
What is the statutory deadline for Canara Bank to issue the No Dues Certificate (NDC)?
Under RBI Circular RBI/2023-24/60, Canara Bank is legally required to issue an official stamped No Dues Certificate (NDC) / Loan Closure Certificate and update credit bureau records within 30 calendar days of receiving the final settlement installment. If the bank fails to issue the NDC within 30 days without lawful cause, it is statutorily liable to pay compensation of ₹5,000 per day of delay to the borrower.
How does a Canara Bank loan settlement affect CIBIL scores and future loan eligibility?
Upon full remittance of the compromised sum, Canara Bank reports the account to CIBIL, Experian, Equifax, and CRIF High Mark with the status 'Settled' and an outstanding balance of ₹0. While this causes a temporary 75–150 point credit score reduction and a mandatory 12-month cooling period under RBI directives, ongoing negative DPD reporting terminates immediately. Borrowers can rebuild their CIBIL score to 750+ within 18 to 24 months through disciplined secured credit usage.
What critical clauses must be verified in a Canara Bank OTS Sanction Letter before payment?
Before transferring any funds, borrowers must verify four essential components: (1) The letter must be on official Canara Bank letterhead with branch/SAMB seal, reference number, and signature with Officer Employee Code; (2) An unambiguous debt extinguishment clause confirming the agreed amount represents full and final discharge; (3) A mandatory commitment to withdraw all pending Section 25 PSSA or Section 138 legal proceedings; and (4) Clear terms stipulating payment directly into the borrower's loan account number.