- Civil Nature of Debt: Under AP High Court rulings, loan default is a civil dispute. Police cannot intervene, call you to stations, or threaten arrest.
- Port &. PSU Employee Defense: Workers at Vizag Port, RINL, HPCL, and Pharma City get legal shield against office visits and salary liens.
- Vizag District Court Notice Defense: Advocate replies to Section 138 and Section 25 notices stop summons and move cases to settlement.
- SARB Haircut Slabs (40%–65%): Direct talks with Stressed Asset desks in Dwaraka Nagar win 40% to 65% principal waivers and full fee write-offs.
- Binding DLSA Lok Adalat Award: Settlements passed before Visakhapatnam DLSA act as final civil court orders with no appeals.
Debt Landscape & Borrowers in Visakhapatnam
Visakhapatnam is a major trade hub in Andhra Pradesh. Many residents work at Vizag Port, Gangavaram Port, or RINL Steel Plant. Others work at HPCL and NTPC. Some work in Rushikonda IT SEZ or Parawada Pharma City.
Job cuts, slow client payments. And medical bills cause severe debt stress. Borrowers in Dwaraka Nagar, Siripuram, and Gajuwaka face missed EMIs. Debts often span multiple banks.
When loans default, collection agents use illegal pressure. Under Indian law, loan default is only a civil breach of contract. Clear legal paths exist to stop harassment and settle dues safely.
NPA Delinquency Aging in Visakhapatnam
Getting a good One-Time Settlement (OTS) depends on RBI IRACP norms. Banks offer large haircuts as overdue loans age on their books.
Overdue loans start as Special Mention Accounts (SMA-0 to SMA-2). This phase covers the first 90 days. After 90 days, they turn into defaulted Assets (NPAs). Mandatory provisions of 15% to 100% push banks to settle for cash.
| default Stage. | Overdue Duration. | Bank reserves Burden. | Recovery Strategy &. Haircut Viability. |
|---|---|---|---|
| SMA-0 &. SMA-1. | 1 – 60 Days Overdue. | Standard Capital Provision. | Automated reminders and call pressure. NACH bounce fees apply. Haircut settlements are not available. |
| SMA-2. | 61 – 90 Days Overdue. | Watchlist Provision. | Banks send pre-NPA notices. Collection calls rise. Loan restructuring or extra time may be possible. |
| Substandard NPA. | 91 – 365 Days Overdue. | 15% – 25% Regulatory Provision. | File moves to Zonal SARB desks in Dwaraka Nagar. A 35% to 50% principal waiver becomes viable. |
| Doubtful (D1 / D2). | 1 – 3 Years Overdue. | 40% – 100% Capital Provision. | Banks prefer fast cash over long court battles. Deep 50% to 65% principal waivers are achievable. |
| Loss Asset. | 3+ Years Overdue. | 100% Written-off Balance. | Fully written off on bank books. You can get maximum waivers up to 70% or settle in Lok Adalat. |
The Andhra Pradesh High Court has set clear rules for recovery. Lenders cannot use force or recovery goons to collect debts. All recovery must follow legal due process. Banks remain liable for any illegal acts by their recovery agents.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Defending Legal Notices in Visakhapatnam District
When auto-debits or cheques bounce, banks issue legal notices. They cite Section 25 PSSA or Section 138 NI Act. They threaten cases in Visakhapatnam Metropolitan Magistrate Courts at Jagadamba.
You have a 15-day legal window to send a lawyer-drafted reply. A prompt reply refutes fraud claims. It details genuine hardship, challenges extra charges. And offers a fair settlement.
This reply moves the matter away from court trials. It redirects the file to Dwaraka Nagar SARB desks. It can also go to District Lok Adalat for rapid closure.
Banker's General Lien in Visakhapatnam
Under Section 171 of the Indian Contract Act, 1872, banks hold a general lien. They can seize funds from accounts in that same bank under your PAN. If your salary lands in your loan bank, the lender may sweep your cash.
Lenders cannot touch accounts in other banks without a court order. If you face loan default, open a fresh salary account elsewhere. Use a bank where you have no loan dues. This keeps your household income safe.
Personal Loan Settlement Roadmap in Visakhapatnam
The chart below outlines each step of debt settlement in Visakhapatnam. It covers legal notice defense and SARB talks in Dwaraka Nagar. It also explains ₹0 No Dues Certificate delivery.
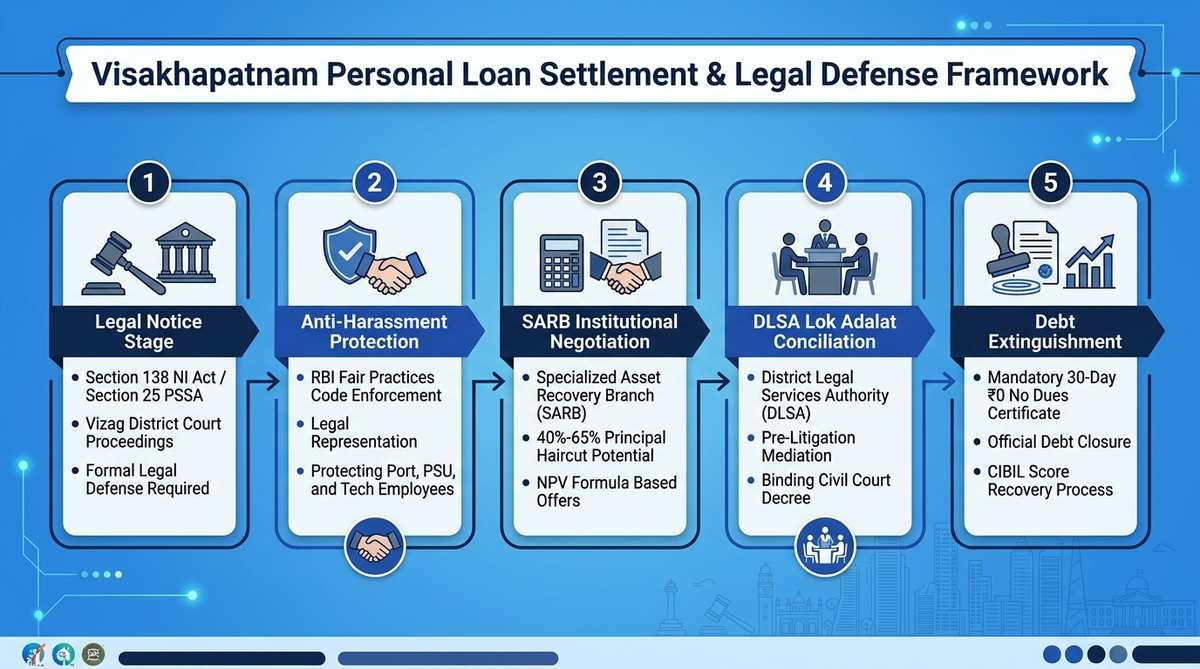
Figure 1.0: Visakhapatnam Personal Loan Settlement Framework, Court Notice Defense &. SARB Roadmap.
OTS Haircut Mechanics & NPV in Vizag
Bank credit committees in Dwaraka Nagar assess offers via Net Present Value (NPV). Civil suits take 4 to 7 years. They also create heavy legal costs. Banks prefer quick cash recovery today over risky court trials.
Here, C_t is estimated recovery and r is discount rate. Deductions cover court fees and blocked capital.
An advocate-led settlement saves legal costs for the bank. It frees up blocked capital. Borrowers secure 40% to 65% principal haircuts. Banks also waive 100% of penal fees.
Enforcing RBI Fair Practices in Vizag
Borrowers are protected under RBI Master Directions on Recovery Agents (2022). Recovery agents cannot call before 08:00 AM or after 07:00 PM. They cannot use abuse, enter workplaces, or visit homes without prior notice.
Visakhapatnam City Police cannot intervene in civil loan defaults. Police stations in Dwaraka Nagar, MVP Colony, and Gajuwaka have zero authority.
Our lawyers send cease-and-desist notices to bank Nodal Officers. We file complaints on the RBI Integrated Ombudsman Portal (CMS). This halts all illegal agent actions.
Vizag DLSA Lok Adalat Conciliation
The Visakhapatnam District Legal Services Authority (DLSA) at Nyayaseva Sadan holds Lok Adalats. Our lawyers win 40% to 65% waivers here. The final award is a binding decree under Section 21 of the Legal Services Authorities Act. It also provides a 100% court fee refund.
If a bank starts arbitration in Chennai or Mumbai, we challenge it. Under Section 12 of the Arbitration Act, we cite the Perkins Eastman ruling. We move the dispute back to Visakhapatnam.
Sanction Letter Audit & NDC in Vizag
Never pay on verbal promises. We review the bank's official OTS Sanction Letter. We check the bank letterhead and loan numbers. We verify settlement sums, payment dates. And waiver terms.
Under RBI Circular RBI/2023-24/60, lenders must issue the No Dues Certificate (NDC) within 30 calendar days of payment. If they delay, they must pay ₹5,000 per day to the borrower.
After settlement, credit reports show 'Settled&apos. with a ₹0 balance. This stops interest adding. Borrowers can rebuild CIBIL scores to 750+ within 18 to 24 months. Secured credit cards help speed up this recovery.
Debt Resolution Pathways in Visakhapatnam
Compare the debt resolution options available in Visakhapatnam:
| Resolution Pathway. | Principal Haircut Range. | Legal Binding Finality. | CIBIL Bureau Status. | Resolution Timeline. |
|---|---|---|---|---|
| Direct SARB Settlement (Dwaraka Nagar / Siripuram). | 40% – 65% Principal Haircut. | Complete (Bank NDC Issued). | 'Settled&apos. / ₹0 Dues. | 3 to 6 Weeks. |
| Visakhapatnam DLSA Lok Adalat (Nyayaseva Sadan). | 45% – 65% Principal Haircut. | Absolute (Civil Court Decree). | 'Settled&apos. / ₹0 Dues. | Quarterly Lok Adalat Cycles. |
| Bank Loan Restructuring. | 0% Haircut (Tenure Extension). | Conditional on Monthly EMI. | 'Restructured&apos. / Active Debt. | 2 to 4 Weeks. |
| Civil Court Litigation (Vizag District Court / HC). | Uncertain (Judicial Discretion). | Subject to Multi-Year Appeal. | 'Suit Filed&apos. / adding. | 4 to 7 Years. |
SettleLoans Legal Defense in Visakhapatnam
SettleLoans gives you advocate defense across Visakhapatnam. We stop agent harassment and reply to court notices. We shield salary accounts and negotiate debt relief under RBI rules.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Visakhapatnam
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Visakhapatnam can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Collectorate Junction, Maharani Peta, Visakhapatnam, Andhra Pradesh - 530002
Jurisdiction: Hears financial recovery summary suits, Sec 25 PSSA summons, and Section 138 complaints for port corridor MSMEs and professionals.
Address: Nyaya Seva Sadan, District Court Premises, Visakhapatnam - 530002
Lok Adalat Conciliation: Schedules quarterly Lok Adalats under AP SLSA for one-time settlement waivers, preventing coercive asset attachments.
FAQs: Personal Loan Settlement in Vizag
Why do port employees, PSU staff, and IT professionals in Vizag need specialized loan settlement lawyers?
Salaried staff in Vizag face heavy pressure during money crises. This includes workers at Vizag Port, RINL, HPCL, NTPC, and IT firms. Banks and NBFCs often send recovery agents who make threats. They may try to visit workplaces or freeze salary accounts. A skilled Vizag loan settlement lawyer stops this harassment under RBI rules. The lawyer protects your salary account from Section 171 banker's liens. They also negotiate 40% to 65% OTS debt waivers.
Which local courts in Visakhapatnam have jurisdiction over bank loan default cases?
Cheque bounce cases under Section 138 NI Act go to local courts. NACH bounce cases under Section 25 PSSA also go there. These are heard at the Metropolitan Magistrate Courts and the Visakhapatnam District Court Complex near Jagadamba. Debts over ₹20 Lakhs go to the Debts Recovery Tribunal (DRT Visakhapatnam). Friendly settlements are recorded before the District Legal Services Authority (DLSA Nyayaseva Sadan).
What legal steps should I take upon receiving a Section 138 or Section 25 notice in Visakhapatnam?
Do not ignore a legal notice. You must reply within 15 days of getting it. Your lawyer files a formal reply. They refute false claims of fraud and challenge extra charges. They also submit a clear settlement offer under RBI rules. If a court case starts, your lawyer files a Vakalatnama. They secure bail on the first date and request a transfer to Lok Adalat.
Can Visakhapatnam City Police arrest me for defaulting on an unsecured personal loan or credit card?
No. Loan default is purely a civil contract breach under the Indian Contract Act, 1872. Vizag City Police cannot arrest you for unpaid loans. Local police stations in Dwaraka Nagar, MVP Colony, or Gajuwaka cannot summon you. They cannot act as collection agents. False criminal complaints get dismissed under the Supreme Court ruling in Arnesh Kumar v. State of Bihar.
How does the District Legal Services Authority (DLSA) Lok Adalat in Visakhapatnam handle loan settlements?
The Visakhapatnam DLSA holds regular Lok Adalats at Nyayaseva Sadan. Your lawyer presents your case to the Lok Adalat bench. Both sides agree on a discounted one-time payment. The bench issues an award under Section 21 of the Legal Services Authorities Act, 1987. This order acts as a final civil court decree. It cannot be appealed, refunds court fees. And closes all bank claims permanently.
What percentage of debt waiver can borrowers in Visakhapatnam negotiate on personal loans?
Borrowers in Vizag can get 40% to 65% principal waivers. The waiver depends on loan age (90 to 180+ days overdue) and proven hardship. Valid reasons include job loss, business drops, or medical bills. Lenders also waive 100% of penal interest, late fees. And bounce charges.
How do Visakhapatnam lawyers prevent banks from seizing salary accounts under Section 171 Banker's Lien?
Under Section 171 of the Indian Contract Act, a bank can set off funds. It can deduct money from savings or salary accounts in that same bank under your PAN. To protect your income, open a new salary account in a different bank. Make sure you have no loans with this new bank. This step keeps your living funds safe from auto-debits.
What is the mandatory timeline for banks in Visakhapatnam to deliver a No Dues Certificate under RBI rules?
Under RBI Circular RBI/2023-24/60, banks and NBFCs must act fast. They must issue the ₹0 No Dues Certificate (NDC) within 30 days of full payment. They must also update credit bureaus like CIBIL and Experian. If the lender delays past 30 days without cause, it must pay ₹5,000 per day of delay to the borrower.