- Zero Machine Attachment: Unsecured loans create no statutory lien on factory equipment or residential properties under Section 60(1)(c) CPC.
- Workplace Harassment Shield: RBI rules strictly prohibit recovery visits to BHEL ancillary workshops, offices, or Navalpattu IT Park campuses.
- Judicial Summons Defense: Strategic advocate replies transform Section 138 NI Act and Section 25 PSSA summons into structured Lok Adalat settlements.
- 40% to 60% Principal Haircuts: Bank credit committees and SARB branches approve substantial debt haircuts based on verifiable commercial hardship.
- Mandatory Regulatory Closure: RBI circulars require lenders to issue stamped No Dues Certificates and clear credit bureau entries within 30 days.
Debt Realities in Trichy: Engineering & Salaried Stress
Tiruchirappalli is Central Tamil Nadu's industrial fabrication capital, driven by BHEL and Golden Rock Railway Workshop. Surrounding these anchors operates an extensive network of boiler component fabricators, machining units, and engineering contractors in Thuvakudi, Thiruverumbur, and Ariyamangalam. While driving manufacturing, enterprises face acute cash flow volatility. Staggered payments on public sector contracts, delayed receivables, and steel price spikes disrupt working capital. To sustain operations, proprietors often take unsecured credit lines and personal loans, which compound rapidly when contract cash flows stall.
Beyond manufacturing, debt distress affects transport operators and traders across the Trichy-Thanjavur delta belt. Simultaneously, salaried professionals in the Navalpattu ELCOT IT Park and educational hubs face debt stress from emergency expenses and instant loans. When accounts turn overdue past 90 days, lenders deploy aggressive recovery agencies in Cantonment and Thillai Nagar. Engaging professional debt settlement services in Trichy Tiruchirappalli enables borrowers to invoke RBI compromise policies, stop harassment, and secure binding debt reductions.
Unsecured vs Secured Debt Protections in Central TN
Borrowers in Tiruchirappalli must distinguish between secured credit and unsecured debt. Secured loans, such as industrial mortgages, fall under the SARFAESI Act, 2002. Secured lenders can issue Section 13(2) notices and assume physical property possession without court sanction. Conversely, unsecured personal loans, credit cards, and clean business credit carry no pledged assets. Creditors have no summary seizure powers and must rely on standard civil suits under the Indian Contract Act, 1872.
| Debt Category. | Underlying Security. | Governing Statutory Law. | Lender Legal Enforcement. | Target Settlement Haircut. |
|---|---|---|---|---|
| Personal Loans. | None (No asset pledged). | Indian Contract Act, 1872 & CPC, 1908. | Civil suit only (No seizure). | 40% to 60% Principal Waiver |
| Credit Card Debt. | None (Unsecured revolving limit). | Indian Contract Act, 1872 & RBI rules. | Civil suit only (No attachment). | 50% to 70% Total Waiver |
| MSME Business Loans. | None (Clean business line). | RBI Compromise Framework & MSME Act. | Commercial suit (No seal). | 40% to 55% Principal Waiver |
| Secured LAP / Loans. | Factory sheds, plots or homes. | SARFAESI Act, 2002 (Sec 13(2), Sec 13(4)). | Direct physical asset auction. | 15% to 25% (Requires asset sale). |
For fabricators in Thuvakudi and Thiruverumbur, Section 60(1)(c) of the Civil Procedure Code protects artisan tools, livelihood machinery, and basic personal necessities from court attachment. Because unsecured lenders cannot seize workshop machinery, banks prefer negotiated cash settlements over futile civil trials.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Halting Recovery Agent Harassment in Tiruchirappalli
Aggressive recovery agent conduct creates severe hardship for distressed borrowers across Trichy and Thanjavur. Unregulated collection agents make unauthorized visits to fabrication units in Thuvakudi or homes in KK Nagar, contact relatives, and use abusive tactics. These actions violate explicit directives issued by the Reserve Bank of India and binding rulings from the Supreme Court and Madras High Court:
- Workplace Visits Barred: Recovery agents cannot enter commercial workshops, factories, or corporate offices without prior written consent.
- Third-Party Secrecy: Contacting family members, neighbors, or workplace associates violates constitutional privacy rights.
- Restricted Calling Hours: Collection calls are legally permissible only between 08:00 AM and 07:00 PM.
- Mandatory Verification: Agents must display bank identity badges and hold IIBF debt recovery certification.
When lenders breach these rules, SettleLoans serves formal cease-and-desist notices to bank Nodal Officers. These notices demand all communications proceed exclusively through legal counsel, stopping harassment under threat of RBI Ombudsman complaints.
Defending Section 138 & Arbitration in Trichy Courts
When defaults persist, lenders issue legal notices under Section 138 of the Negotiable Instruments Act, 1881, for bounced cheques, or Section 25 of the Payment and Settlement Systems Act, 2007, for dishonored e-NACH auto-debits. While these notices carry quasi-criminal implications, they do not lead to immediate arrest. Lenders must prove in court that the instrument was drawn against an active legally enforceable liability rather than retained as undated security.
Legal advocates file formal defense replies before the Chief Judicial Magistrate Court in Trichy. Our counsel demonstrates genuine commercial hardship, challenges unverified penal interest, and contests unilateral arbitration initiated in distant cities under Section 12(5) of the Arbitration Act, 1996. Citing Supreme Court precedents like Perkins Eastman, we force lenders to transfer disputes to local Trichy jurisdiction.
Once court appearances are filed, advocates redirect disputes into the District Legal Services Authority (DLSA) at the Trichy District Court complex. In National Lok Adalats, judicial officers facilitate structured compromise settlements, permanently extinguishing pending Section 138 complaints with total legal immunity.
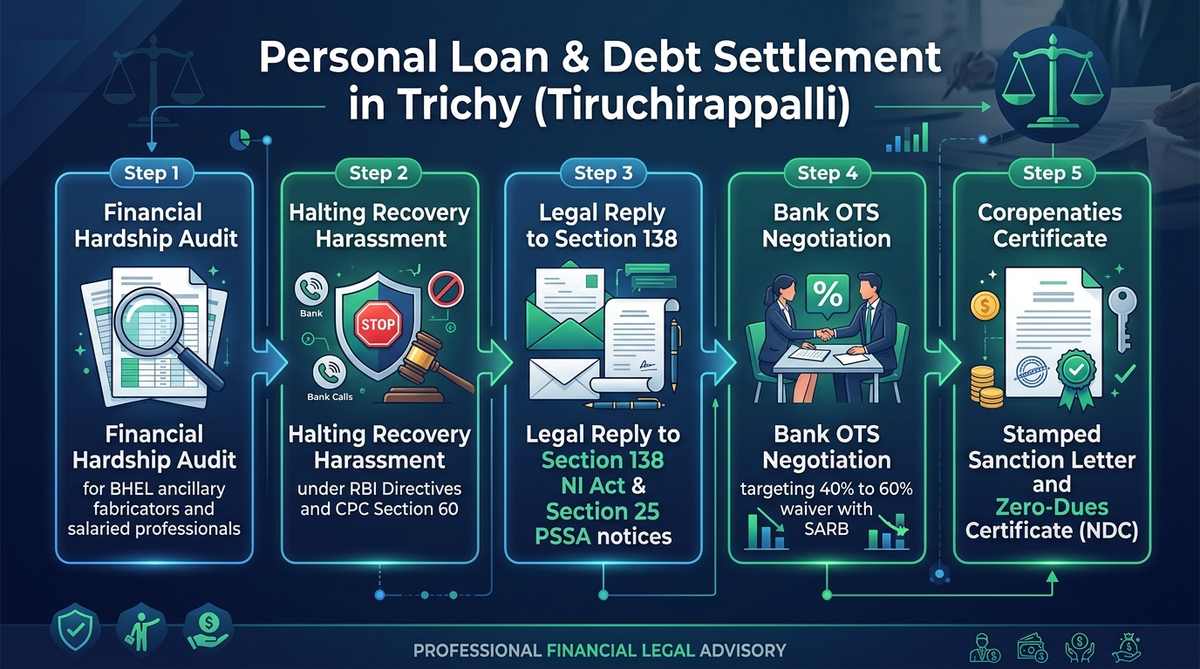
5-Step Loan Settlement & Debt Compromise Framework
NPV Valuation & Bank Math in Central Tamil Nadu
Lenders approve substantial debt write-offs due to financial accounting rules under the RBI Compromise Settlement Framework. Under Ind AS 109 and IRAC prudential norms, an unsecured credit facility overdue for ninety days enters NPA classification. Banks must make mandatory cash provisions from balance sheet profits, escalating from 25% up to a 100% write-off over subsequent reporting quarters.
Where C_t represents estimated recoveries, r is the discount rate, and deductions account for 3–5 years of court friction and capital locked in NPA provisions.
Under Net Present Value (NPV) modeling, civil litigation in Trichy courts is uneconomical for lenders. Contested lawsuits require heavy court fees and take 3 to 6 years without guarantee of finding attachable assets. In contrast, an advocate-negotiated cash settlement of 40% to 55% provides immediate capital recovery, releases blocked NPA reserves, and eliminates legal overhead. Bank credit committees routinely approve compromise settlements that maximize net recovery.
Step-by-Step OTS Protocol in Tiruchirappalli
Resolving delinquent personal and business loans through an advocate-led One-Time Settlement involves five strategic phases designed to protect borrower rights and optimize savings:
1Hardship Dossier Compilation
Our legal team compiles balance sheets, GST records, and client delay notices to document genuine financial hardship.
2Revocation of Mandates & Legal Shield
Revoking e-NACH mandates through banks stops bounce fees, while formal legal notices direct all communications to our advocates.
3Stressed Asset Desk Submissions
Bypassing field tele-callers to submit formal settlement petitions directly to bank Zonal Stressed Assets Recovery Branches (SARB).
4Principal Haircut Negotiation
Enforcing complete waivers on penal interest and late fees under RBI fair practices codes, while securing 40% to 60% principal write-offs.
5Forensic Sanction Audit & NDC Delivery
Forensic audit of the stamped bank sanction letter prior to payment, followed by securing the official No Dues Certificate within 30 days.
Sanction Letter Audit & NDC in Tiruchirappalli
Forensic verification of the bank sanction letter is critical to ensure permanent debt relief. Rogue collection agents often promise verbal settlements or issue forged letters to divert payments into unauthorized accounts. SettleLoans audits every settlement letter, verifying official bank letterheads, authorized officer signatures, loan account numbers, exact compromise amounts, and explicit clauses confirming full debt extinguishment.
After settlement funds are deposited directly into the borrower loan account, RBI Circular RBI/2023-24/60 requires lenders to issue the official No Dues Certificate (NDC) and return all security cheques within thirty calendar days. Failure to deliver the NDC within this statutory window entitles the borrower to mandatory compensation of ₹5,000 for each day of delay.
CIBIL Score Rehabilitation in Central Tamil Nadu
Following an OTS settlement, the lender updates credit rating bureaus, including CIBIL, Experian, and Equifax. The loan status transitions from delinquent default to 'Settled', with outstanding dues recorded as ₹0. While a settled status causes an initial drop in credit score, it halts monthly default reporting, eliminates penal fee growth, and ends all civil litigation threats.
Borrowers in Trichy can rebuild their credit profile to 750+ within 18 to 24 months. By securing a small fixed-deposit-backed credit card, keeping credit usage below thirty percent, and making timely utility and card payments, positive credit history accumulates steadily, restoring eligibility for institutional loans.
Debt Resolution Matrix in Central Tamil Nadu
Compare debt resolution avenues available to borrowers across Trichy, Thanjavur, and Pudukkottai:
| Resolution Pathway. | Legal Forum. | Waiver Range. | Borrower Risk. | Statutory Outcome. |
|---|---|---|---|---|
| Advocate Bank OTS. | Bank Stressed Asset Committee. | 40% to 60% Principal Waiver | Zero (Advocate managed). | Binding settlement with ₹0 NDC. |
| National Lok Adalat. | Trichy DLSA Judicial Committee. | 45% to 60% Debt Haircut | Minimal (Single hearing). | Civil Court Decree (Final order). |
| Contested Court Trial. | Magistrate or Civil Court. | 0% (Full claim + legal fees). | High (Warrants & decrees). | Lengthy litigation lasting 3 to 6 years. |
| Loan Restructuring. | Bank tenure extension. | 0% (No reduction). | Moderate (Higher total interest). | Lengthens debt burden without reduction. |
Why Central TN Borrowers Rely on SettleLoans
SettleLoans delivers advocate-led debt resolution for fabricators, engineering contractors, and salaried employees across Tiruchirappalli and Thanjavur. Our banking advocates neutralize recovery harassment under RBI regulations, defend court summons, safeguard essential workshop machinery under CPC Section 60(1)(c), and secure 40% to 60% debt haircuts through formal One-Time Settlements backed by stamped No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: Debt Settlement in Tiruchirappalli
How do debt settlement services in Trichy protect engineering fabricators?
Debt settlement services provide advocate representation under RBI compromise rules. Legal counsel compiles verified business hardship documentation, halts collection calls, defends court summons, and negotiates 40% to 60% principal waivers directly with bank credit committees.
Can recovery agents visit BHEL ancillary workshops in Thuvakudi or Thiruverumbur?
No. Under the Reserve Bank of India Fair Practices Code, recovery agents are strictly prohibited from entering commercial workshops, factories, or offices without prior written consent. SettleLoans issues formal legal notices to bank nodal officers to halt unauthorized visits immediately.
What percentage of loan waiver can borrowers in Trichy expect through an OTS?
Borrowers with delinquent unsecured loans past 90 days can typically secure a 40% to 60% waiver on principal debt. Banks also waive 100% of accumulated penal interest and late fees under the RBI Compromise Settlement Framework.
How does SettleLoans defend Section 138 cheque bounce notices in Trichy courts?
Our legal team files detailed replies before the Chief Judicial Magistrate Court in Trichy. We establish genuine financial hardship, contest arbitrary interest additions, and guide the dispute into National Lok Adalats to achieve binding compoundable settlements.
Are unsecured business loans and overdrafts eligible for compromise settlement?
Yes. Clean business loans, personal overdrafts, and fintech loans qualify under the RBI Master Direction on Compromise Settlements (2023). Borrowers can settle overdue liabilities without risking industrial equipment or commercial property.
Why do banks in Tamil Nadu agree to write off substantial unsecured debt?
Under Ind AS 109 accounting rules, banks must set aside heavy cash provisions for non-performing loans. Civil recovery suits take 3 to 6 years in local courts. An upfront cash compromise delivers higher Net Present Value than prolonged litigation.
What documents are required to initiate an advocate-led loan settlement in Trichy?
Borrowers must furnish recent loan account statements, income tax returns or audited balance sheets, proof of delayed client receivables or medical hardship, copies of bank legal notices, and signed legal vakalatnama or authorization forms.
What is the mandatory timeline for banks to issue the No Dues Certificate in Tamil Nadu?
Under RBI Circular RBI/2023-24/60, lenders must deliver the official No Dues Certificate and return security cheques within 30 days of settlement payment. Unjustified delays obligate the lender to pay compensation of ₹5,000 per day.
How can a borrower rebuild credit scores after settling a personal loan in Trichy?
Following settlement, the loan balance updates to ₹0 across CIBIL and Experian. Borrowers can restore their credit score above 750 within 18 to 24 months by using a secured fixed-deposit credit card and maintaining disciplined on-time payments.
Official Statutory & Regulatory References
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Master Circular: Fair Practices Code for Lenders, Recovery Agent Conduct & Penal Charge Caps
- Madras High Court: Judicial Directives on Fair Debt Recovery, Prohibition of Third-Party Harassment & Due Process
- Reserve Bank - Integrated Ombudsman Scheme: Grievance Redressal Mechanism for Unlawful Recovery Harassment & NDC Delays
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987, Pre-Litigation Lok Adalat Compromise Framework