- Senior Advocate Representation: Direct negotiation with bank Zonal Desks, completely bypassing recovery agencies.
- Workplace Privacy & Career Protection: Statutory notices bar recovery agents from visiting IT campuses or contacting HR.
- 40% to 65% Principal Waivers: Verified financial hardship dossiers unlock substantial legal debt reductions under RBI rules.
- Mysuru & Mandya Court Defense: Expert legal defense against Section 138 & 25 PSSA summons with binding Lok Adalat decrees.
- Guaranteed ₹0 NDC Delivery: Stamped settlement letter, credit bureau update, and final NDC delivered within 30 days.
Navigating Debt Default Dynamics in Mysore: The Southern Tech
Mysore (Mysuru) serves as Karnataka's second-largest software exporter and a premier satellite technology hub connected to Bengaluru via the NH 275 expressway. The city hosts major software development centers across the Hebbal Electronic City corridor alongside traditional commerce: silk weaving houses, sandalwood oil and handicraft manufacturing, heritage tourism, and trading establishments throughout Sayyaji Rao Road and Mandi Mohalla. Neighboring Mandya adds an agro-processing and manufacturing belt centered on sugar mills, jaggery production, and allied engineering units.
Rapid digital credit expansion led commercial banks and fintech NBFCs to disburse high-ticket personal loans (₹10 Lakhs to ₹40 Lakhs) and revolving cards to tech employees, alongside unsecured credit lines to regional merchants. However, software restructuring, project deferrals, and local market slowdowns left many borrowers unable to sustain EMIs exceeding 60% of take-home income. Defaulting on an unsecured personal loan is strictly a civil breach of contract under the Indian Contract Act, 1872—never a criminal act.
In close-knit residential areas like Vijayanagar, Saraswathipuram, Gokulam, and Kuvempunagar, debt recovery incursions create severe social distress. SettleLoans delivers advocate-led legal representation that halts third-party collection harassment, protects workplace dignity, and negotiates lawful debt waivers under Reserve Bank of India compromise settlement guidelines.
Karnataka Judicial Architecture: Mysuru District Courts, DRT Bengaluru & High Court Oversight
Resolving debt recovery disputes in southern Karnataka requires understanding local court jurisdictions. In Mysuru district, Section 138 NI Act cheque bounce complaints, Section 25 PSSA NACH bounce cases, and Order 37 CPC summary suits are adjudicated before Judicial Magistrates at the District & Sessions Court Complex at Malalavadi, Jayanagar. Mandya matters fall under the Principal District and Sessions Court Complex at Mandya.
For bank recovery claims exceeding ₹20 Lakhs, lenders file applications before Debts Recovery Tribunals (DRT-1 and DRT-2 Bengaluru) covering Mysuru and Mandya. Constitutional writ petitions under Article 226 and quashing petitions under Section 482 CrPC / Section 528 BNSS fall under the High Court of Karnataka (Principal Bench, Bengaluru).
| Jurisdiction | Court Complex | Primary Litigation Handled | Governing Statute | Advocate Defense Strategy |
|---|---|---|---|---|
| Mysuru District | Malalavadi Court Complex, Jayanagar, Mysuru | Section 138 NI Act, Section 25 PSSA, Order 37 CPC summary suits | NI Act 1881, PSSA 2007, CPC 1908 | Mandatory 15-day notice reply, bail securing, hardship filing, and conciliation transfer to DLSA Lok Adalat. |
| Mandya District | Principal District & Sessions Courts, Mandya | Agro-processing debt claims, trader loan recall suits, cheque bounce | Indian Contract Act, NI Act 1881 | Financial hardship affidavit submission, balance sheet forensic audit, and structured compromise sanction. |
| DRT Bengaluru (DRT-1 & DRT-2) | Gandhinagar / Resettlement Road, Bengaluru | High-value bank recovery applications exceeding ₹20 Lakhs | RDB Act 1993, SARFAESI Act 2002 | Challenging unlawful penal compounding, obtaining interim protection, and negotiating Stressed Assets Desk OTS. |
| DLSA Mysuru & Mandya | District Legal Services Authorities | Pre-litigation and pending bank loan compromise conciliation | Legal Services Authorities Act 1987 | Formal bilateral settlement resulting in a final, non-appealable civil court decree with zero stamp duty costs. |
| High Court of Karnataka | Principal Bench, Bengaluru | Writ petitions (Art 226/227), Sec 482 CrPC / Sec 528 BNSS quashing | Constitution of India, CrPC 1973 | Restraining coercive third-party recovery harassment, quashing vexatious complaints, and enforcing personal liberty. |
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Bank Accounting Mechanics: How NPA Provisioning Unlocks Substantial Debt Waivers
Commercial banks and NBFCs operate under RBI Prudential Norms on Income Recognition, Asset Classification and Provisioning (IRACP) and Ind AS 109 Expected Credit Loss rules. When a borrower misses three consecutive EMIs (exceeding 90 days past due), the loan is reclassified as a Non-Performing Asset (NPA). The lender must immediately stop accruing interest as income and set aside mandatory provisioning reserves from operating profits.
As an NPA matures from Sub-Standard to Doubtful and Loss stages, mandatory provisioning escalates to 100%, freezing institutional capital. Bank Stressed Assets Committees evaluate settlement offers using a quantitative Net Present Value (NPV) benchmark:
Where C_t represents estimated recoveries over year t, r is the discount rate, and deductions account for 3–5 years of court delays in Karnataka alongside 100% locked NPA capital reserves.
Because prosecuting civil recovery suits in district courts takes four to seven years with uncertain execution, an immediate settlement offers higher net value. An authorized OTS allows the lender to write back locked provisions directly into profits, justifying a 40% to 65% principal waiver.
Halting Recovery Harassment & Workplace Incursions Under Strict RBI Guidelines
Borrowers in Mysore and Mandya often face coercive collection tactics from third-party recovery agencies. Agents routinely breach statutory norms by making repeated calls outside allowed hours, contacting family members, or threatening office visits in Hebbal or retail markets.
The RBI Master Direction on Recovery Agents and Fair Practices Code sets strict rules: agents cannot call before 08:00 AM or after 07:00 PM, cannot contact employers or coworkers, must hold IIBF certification, and cannot visit workplaces unannounced. In ICICI Bank Ltd. v. Prakash Kaur, the Supreme Court barred banks from using extrajudicial force. In K.S. Puttaswamy v. Union of India, the apex court affirmed the fundamental right to privacy under Article 21.
SettleLoans issues formal statutory cease-and-desist notices to the lender's Principal Nodal Officer. Once an advocate represents the borrower, all lender contact must route exclusively through counsel. Violations are escalated to DLSA Mysuru, Karnataka Police Cyber Cell, and the RBI Integrated Ombudsman.
Personal Loan Settlement & Legal Conciliation Roadmap in Karnataka
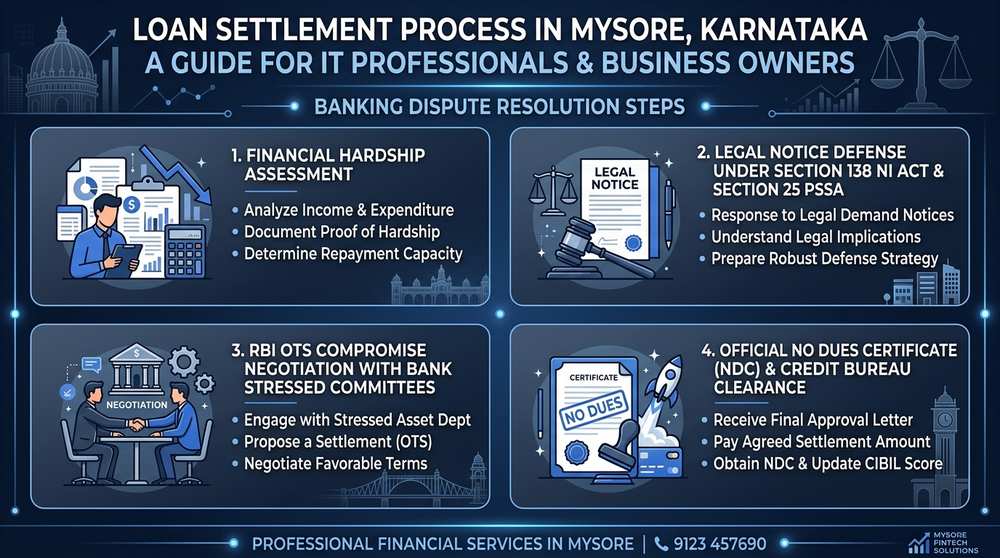
Tailored Legal Settlement Strategies: Tech Professionals, Merchants & Mandya MSMEs
Because Mysore and Mandya feature distinct borrower profiles, SettleLoans applies targeted legal defense and negotiation frameworks tailored to specific employment and business categories:
1. IT Software Engineers, Tech Leads & Remote Consultants
Tech specialists in Hebbal IT parks or remote consultants in Vijayanagar, Gokulam, and Kuvempunagar often carry multiple unsecured personal loans and credit cards. When restructuring or compensation freezes strike, servicing high EMIs becomes unsustainable. SettleLoans negotiates discreetly with bank Zonal Desks, invokes Section 60(1)(i) CPC salary exemptions, and resolves liabilities through heavily discounted settlements without workplace exposure.
2. Heritage Silk Merchants, Sandalwood Artisans & Tourism Operators
Traders along Sayyaji Rao Road, Mandi Mohalla, and tourist zones face sharp seasonal revenue drops. Many rely on unsecured commercial loans for inventory. When receivables stall, repayments collapse. Our advocates compile GST records and audited statements into a verified hardship dossier, securing 45% to 60% principal waivers from bank Credit Committees.
3. Agro-Processing Founders, Sugar Unit Suppliers & Mandya MSMEs
Industrial units in Mandya and Belagola/Nanjangud face liquidity crunches from long corporate credit cycles and raw material swings. Borrowers often face Section 138 notices on machinery top-up loans. SettleLoans audits debt accounts for improper penal charges and negotiates structured compromise packages through bank Stressed Assets Committees.
Defending Section 138 NI Act, Section 25 PSSA & Enforcing Lok Adalat Decrees
When defaults exceed 90 to 180 days, lenders frequently initiate complaints under Section 138 NI Act for bounced cheques or Section 25 PSSA for failed NACH auto-debits before Judicial Magistrates in Mysuru or Mandya. These represent bailable, compoundable proceedings arising from civil contracts.
Serving a structured legal reply within the statutory 15-day window establishes bona fide financial hardship and sets up compromise settlement pathways. When lenders initiate distant arbitration, our advocates challenge sole arbitrator appointments under Sections 12 and 14 of the Arbitration Act, citing Supreme Court rulings in TRF Ltd. and Perkins Eastman to prevent ex-parte awards.
The optimal forum for settlement is the National Lok Adalat, organized quarterly by KSLSA and DLSA Mysuru/Mandya. A compromise recorded before the Lok Adalat carries the force of a final Civil Court Decree under Section 21 of the Legal Services Authorities Act, 1987. It is binding, non-appealable, and mandates the lender to withdraw all pending complaints and close the debt permanently.
Sanction Letter Forensics: Verifying Legitimate OTS Documents & ₹0 NDC Delivery
Verifying settlement documentation before remitting funds is vital to protect against recovery agency fraud. Disreputable agencies often issue fake letters or verbal promises, diverting payments into suspense accounts while leaving the debt active. SettleLoans audits every settlement document before authorizing client disbursement.
Our advocates verify official bank letterheads, authorized signatory credentials, explicit full-and-final discharge clauses, and case withdrawal terms. Settlement payments are transferred directly to the lender's loan account via RTGS/NEFT.
Under RBI Circular RBI/2023-24/60, lenders must issue an official ₹0 No Dues Certificate (NDC) and update credit bureaus within 30 days of receiving settlement remittance. Unjustified delays make the bank statutorily liable to compensate the borrower at ₹5,000 per day of delay.
CIBIL Score Trajectory Post-Settlement & Systematic Credit Restoration Strategy
Following an OTS, the lender reports the account to credit bureaus (CIBIL, Experian, Equifax, CRIF High Mark) as 'Settled' with a ₹0 balance. While this results in an initial 75–150 point score reduction and a 12-to-18-month cooling period, it permanently halts active default compounding and litigation risk.
Borrowers can systematically rebuild their score to 750+ within 18 to 24 months by using a secured fixed-deposit credit card, keeping credit utilization below 25%, and maintaining punctual repayments.
| Parameter | Active Unresolved Default | Advocate-Led OTS Compromise | Post-Settlement Credit Rehabilitation |
|---|---|---|---|
| Credit Bureau Status | Default / Written Off / Suit Filed | Settled (₹0 Outstanding Balance) | Rebuilt Prime Credit History |
| Total Financial Liability | Compounds monthly at 24%–42% penal rates | Extinguished with 40%–65% debt haircut | Zero remaining liability or debt claim |
| Legal & Court Exposure | Active Sec 138, Sec 25 PSSA summons | Withdrawn via Lok Adalat decree | Complete, irrevocable legal immunity |
| Workplace & Social Standing | Severe recovery calls, office visits, social stigma | Permanently halted via Cease-and-Desist | Zero agency interference or contact |
| CIBIL Score Trajectory | Persistently suppressed below 550 | Stabilizes within 6–12 months | Rebuilt to 750+ within 18–24 months |
Why Distressed Borrowers Across Mysore & Mandya Trust SettleLoans
Resolving unsecured personal loan defaults, multi-bank credit card balances, and distressed business credit lines across Mysore and Mandya requires specialized banking jurisprudence, rigorous financial forensic accounting, and direct institutional engagement with bank Stressed Assets Committees. SettleLoans delivers total anti-harassment protection, robust legal defense in local district courts, maximized debt haircuts, and authentic ₹0 No Dues Certificates delivered with complete transparency and confidentiality.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
Frequently Asked Questions About Loan Settlement in Mysore & Karnataka
How does personal loan settlement work in Mysore and Mandya?
Personal loan settlement is a formal conciliation governed by RBI Master Directions (DOR.STR.REC.20/21.04.048/2023-24). When an unsecured loan crosses 90 days past due into NPA status, advocates represent the borrower before the lender's Stressed Assets Desk. Counsel presents hardship documentation, waives penal interest, and negotiates an authorized 40% to 65% debt reduction concluded via a stamped OTS letter and ₹0 No Dues Certificate.
Why is advocate-led loan settlement critical for IT professionals in Mysore?
IT professionals working in Mysore's Hebbal corridor require complete privacy. Third-party collection agencies often jeopardize careers by contacting HR or team members. Senior advocates serve statutory cease-and-desist notices citing Supreme Court precedents in ICICI Bank v. Prakash Kaur, compelling banks to halt third-party interference and communicate solely through legal counsel.
Can banks contact my HR or visit my tech office in Hebbal or Belagola?
No. Under RBI Master Directions on Recovery Agents, collection personnel are strictly barred from visiting workplaces without consent, calling corporate receptionists, or discussing debt with coworkers. Doing so violates banking regulations and borrower privacy rights, leading to immediate escalation to the RBI Ombudsman.
Which local courts have jurisdiction over loan default cases in Mysore and Mandya?
In Mysuru, Section 138 NI Act cheque bounce complaints, Section 25 PSSA auto-debit cases, and Order 37 CPC suits are heard at the Malalavadi Court Complex, Jayanagar. Mandya cases fall under the Principal District Courts Complex at Mandya. Claims exceeding ₹20 Lakhs fall under DRT-1 and DRT-2 Bengaluru, while writ petitions fall under the High Court of Karnataka.
What percentage of debt waiver can borrowers in Mysore realistically achieve?
On unsecured personal loans and credit cards past 90 to 180 days default, banks typically approve principal waivers of 40% to 65% of outstanding ledger dues. In addition, advocate negotiation ensures a 100% complete waiver of accrued penal interest, late fees, and repeated NACH return charges under RBI Fair Lending Directives.
How do advocates defend against Section 138 NI Act and Section 25 PSSA notices in Mysuru?
When served with demand notices for bounced cheques or failed NACH mandates, advocates submit formal legal replies within the 15-day statutory window. Counsel establishes bona fide hardship, challenges improper penal interest, secures bail upon court appearance, and refers the matter to the National Lok Adalat for an amicable settlement.
How can local merchants and MSME owners in Mysore and Mandya settle unsecured business debts?
Merchants and MSME owners experiencing cash flow contraction submit GST filings, audited accounts, and bank records to demonstrate commercial downturn to bank Credit Committees. Applying Net Present Value recovery principles, advocates secure structured 45% to 60% principal haircuts.
How does settling a loan impact CIBIL scores, and how can credit be rebuilt?
Post-settlement, bureaus report the account as 'Settled' with a ₹0 balance. While this results in an initial 75–150 point score reduction and a 12-to-18-month cooling period, it permanently terminates compounding default marks. Scores can be systematically restored to 750+ within 18 to 24 months through secured credit cards.
What is the statutory timeline for receiving the No Dues Certificate (NDC) under RBI rules?
Under RBI Circular RBI/2023-24/60, lenders must issue an official ₹0 No Dues Certificate and update credit bureaus within 30 calendar days of receiving the settlement remittance. Delayed issuance makes the lender statutorily liable to compensate the borrower at ₹5,000 per day of delay.
Official Regulatory References & Statutory Portals
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- High Court of Karnataka (Principal Bench Bengaluru): Official Case Status, Cause Lists & Judicial Directives on Banking Litigation
- Karnataka State Legal Services Authority (KSLSA): National & State Lok Adalat Conciliation Guidelines and Schedules
- Debts Recovery Tribunal (DRT Bengaluru): Territorial Jurisdiction, Case Filings & Securitization Procedures
- Reserve Bank - Integrated Ombudsman Scheme (CMS Portal): Online Portal for Banking Harassment & Penalty Waiver Escalation