- Southern Tamil Nadu Protection. Legal help for traders and salaried staff in Madurai, Dindigul, and Virudhunagar facing loan default.
- SARB &. Loan App Defense. Stop recovery agent harassment, bank demand notices. And loan app threats with formal legal replies.
- Lok Adalat Settlement. Resolve Section 138 NI Act and Section 25 PSSA summons at Madurai District Court through binding civil compromise awards.
- 40% to 60% Debt Waivers. Use RBI compromise rules and NPA bad loan rules to negotiate the lowest settlement amount.
- Official No Dues Certificate. Enforce RBI rules to get your physical NDC in 30 days and update CIBIL to a zero balance.
1. Debt Settlement Landscape in Madurai
Madurai is the trade hub of Southern Tamil Nadu. It links textile markets in South Masi Street, agro-units in Dindigul. And printing firms in Virudhunagar. Rising costs and slow business have forced many local traders and workers to take high-interest personal loans and credit cards.
When monthly income drops, paying 18% to 36% interest becomes very hard. Missed payments lead to calls from bank recovery branches (SARBs), third-party agents. And microfinance staff. But unsecured loan default is strictly a civil dispute under the Indian Contract Act, 1872. Legal advocates in Madurai step in to stop harassment and negotiate a formal One-Time Settlement (OTS) with up to 60% debt waiver under RBI rules.
2. Southern Tamil Nadu Debt Landscape & Realities
Trade in Southern Tamil Nadu runs on seasonal cash flows. When banks set up automated NACH debits, missed payments trigger fast recovery action across four main areas:
Banks send 90-day overdue accounts to recovery branches in Madurai and Chennai. These units issue loan recall notices and file Section 138 cheque bounce cases.
Lenders in Dindigul and Virudhunagar often send field agents during shop hours. This practice violates RBI fair practice codes.
Many workers face illegal loan apps that charge high fees and send messages to contact lists.
Local credit societies often add high penal interest on overdue loans without proper notice.
Paying small token amounts to agents does not clear your loan. It only goes toward extra fees. Legal representation protects your rights and moves banks directly into formal OTS talks.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Statutory Protections in Madurai
Borrowers in Southern Tamil Nadu enjoy strong legal rights. The Madurai Bench of the Madras High Court has ruled that banks cannot use private muscle men or police to collect loans. Pure loan default is strictly a civil matter.
Defaulting on a personal loan is not a crime under the Indian Penal Code or Bharatiya Nyaya Sanhita. Lenders cannot file an FIR or arrest you for genuine financial distress.
Defending Section 138 NI Act & Section 25 PSSA Summons
When NACH auto-debits or cheques bounce, lenders file complaints under Section 138 of the Negotiable Instruments Act or Section 25 of the PSSA in Madurai courts. Defense advocates represent you, challenge false interest claims. And move the matter to the National Lok Adalat. Under Section 147 of the NI Act, all court cases are closed permanently once you settle.
RBI Anti-Harassment Rules
Under RBI Fair Practice Codes, recovery agents can only call between 8:00 AM and 7:00 PM. They cannot call your relatives or friends. They cannot visit your workplace or use harsh words.
4. NPA Accounting & NPV Models in Madurai
Debt waivers are built on RBI accounting rules. When an unsecured personal loan stays unpaid past 90 days, it becomes a Non-Performing Asset (NPA). For doubtful loans, banks must set aside 100% of the loan amount as capital provision from their profits.
| Asset Class. | Overdue Days. | Bank Provision. | Target OTS Waiver. |
|---|---|---|---|
| Standard (SMA-0 to 2). | 1 to 90 Days. | 0.40% to 5.0% Buffer. | Penal fee waiver only. |
| Sub-Standard Asset. | 91 Days to 12 Months. | 25% Capital Provision. | 25% to 40% Waiver. |
| Doubtful-1 Asset. | 12 to 24 Months. | 100% Capital Provision. | 40% to 50% Waiver. |
| Doubtful-2 / Doubtful-3. | 24 to 48+ Months. | 100% Full Provision. | 50% to 60% Waiver. |
| Loss / Written-Off. | Bad Debt / Unpaid. | 100% Book Write-off. | 55% to 65% Waiver. |
Civil suits and DRT Madurai cases take 4 to 7 years to finish. Banks spend huge legal fees on slow court cases. Because of this, bank credit committees use the Net Present Value (NPV) recovery rule to approve cash settlements:
Where C_t is expected cash, r is the bank cost of funds. And deductions include court delay and locked NPA reserves.
An immediate cash settlement of 40% to 50% releases 100% of the locked capital back into bank profits. This gives banks a strong reason to grant large debt discounts.
5. Loan Settlement Roadmap in Madurai
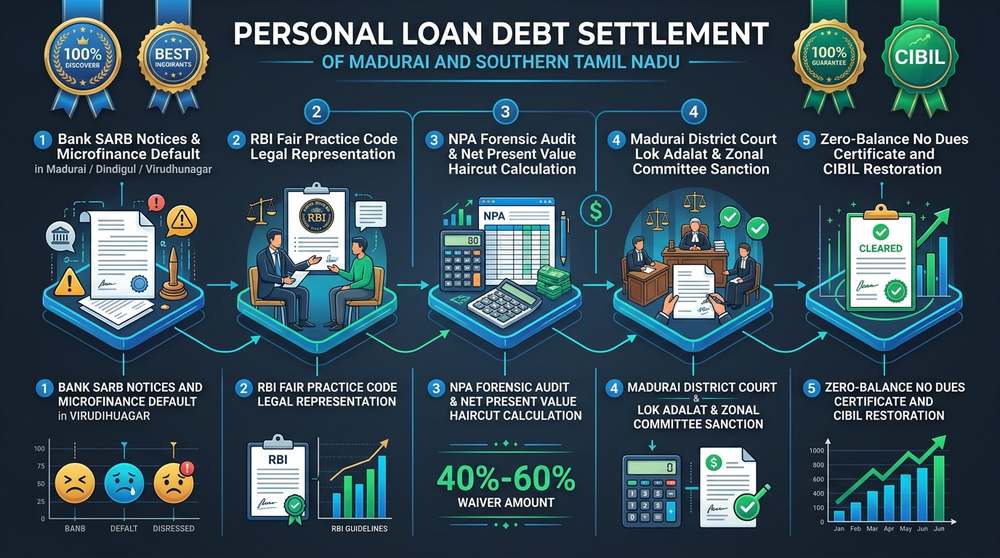
This simple roadmap explains the 5 key stages to settle delinquent personal loans, stop SARB notices. And get your No Dues Certificate across Southern Tamil Nadu.
6. Legal Settlement Protocol in Madurai
Settling defaulted personal loans with major banks (HDFC, ICICI, Axis, Kotak, SBI) or NBFCs follows five proven steps:
Phase 1: Loan Statement Audit
Advocates audit your loan statement. We remove unfair late fees, bounce charges. And penal interest that violate RBI guidelines.
Phase 2: Legal Representation Notice
We serve formal legal notices on the bank nodal officer and SARB manager. This directs all calls to counsel and stops visits to your workplace.
Phase 3: Financial Hardship Dossier
We assemble verified proof of income loss, medical bills, or business setbacks. This proves your reduced capacity to pay under RBI rules.
Phase 4: Credit Committee Negotiations
Counsel negotiates directly with bank credit committees. We secure a 40% to 60% principal waiver paid in easy parts.
Phase 5: Lok Adalat Case Closure
If Section 138 or Section 25 court cases exist, counsel presents the settlement before the National Lok Adalat to dismiss all cases for good.
7. Sanction Letter Checklist in Madurai
Borrowers must watch out for fake settlement letters issued by rogue recovery agents. Before paying any money, our advocates check four vital points on your OTS letter:
The letter must have the bank logo, branch address, reference code. And official signature.
The letter must state total dues, the exact waiver amount. And the final net payment.
The letter must state that this payment closes the loan account in full with zero balance remaining.
The bank must promise in writing to withdraw all Section 138 NI Act and Section 25 PSSA cases.
Never pay settlement funds in cash or to personal accounts. Always pay directly into your loan account via RTGS, NEFT, or Demand Draft drawn in favor of the lending bank.
8. Settlement Remittance & NDC in Madurai
Under RBI Circular RBI/2023-24/60, lenders must issue your official No Dues Certificate (NDC), return security cheques. And update credit records within 30 days of full payment. If the bank delays without reason, it must pay you a penalty of ₹5,000 per day of delay.
After payment, the bank updates credit bureaus (CIBIL, Experian, CRIF) to mark the loan as "Settled" with an outstanding balance of ₹0. This stops active default notices. You can rebuild your credit score above 750 within 12 to 18 months using a small secured card with prompt monthly payments.
9. Debt Resolution Matrix in Madurai
Compare debt options for Madurai, Dindigul, and Virudhunagar borrowers to pick the best path forward:
| Resolution Path. | Legal Forum. | Target Waiver. | Time Taken. | Legal Result. |
|---|---|---|---|---|
| Advocate Bank OTS. | Bank Committee &. RBI Rules. | 40% to 60% Waiver. | 45 to 90 Days. | Full legal immunity. Closes Section 138 cases. Official ₹0 NDC issued. |
| National Lok Adalat. | Madurai DLSA Legal Forum. | 35% to 55% Waiver. | Single Hearing Day. | Final court decree. Zero court fees. Permanent closure of disputes. |
| Contested Court Trial. | Trial under Section 138 NI Act. | 0% (Full Dues + Fees). | 3 to 6 Years. | High legal stress. Risk of warrants and money decrees. |
| Informal Deals with Agents. | Verbal deals with field staff. | No legal proof. | Uncertain. | Risk of fraud. Harassment continues unabated. |
| Loan Restructuring. | Tenure elongation. | 0% (No reduction). | 30 to 60 Days. | No principal cut. Increases total interest over time. |
10. SettleLoans Legal Relief in Southern Tamil Nadu
SettleLoans provides full debt defense across Madurai, Dindigul, and Virudhunagar. We issue legal cease-and-desist notices, defend Section 138 court summons, remove unfair penal fees. And negotiate directly with bank credit committees for maximum OTS waivers backed by stamped ₹0 No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Madurai
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Madurai can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Melur Main Road, K.K. Nagar, Madurai, Tamil Nadu - 625020
Jurisdiction: Benches handle Section 138 complaints for textile merchants, MSMEs, and salaried borrowers across Madurai and surrounding southern districts.
Address: ADR Centre, Combined Court Complex, Melur Road, Madurai - 625020
Lok Adalat Conciliation: Convenes quarterly Lok Adalats granting unconditional settlement settlements, preventing bank SARFAESI and money suit litigation.
11. FAQs: Loan Settlement in Madurai
Clear answers to common questions about personal loan settlements, SARB notices, Lok Adalat hearings. And borrower rights across Southern Tamil Nadu.
What is the legal process for personal loan settlement in Madurai and Southern Tamil Nadu?
Loan settlement in Madurai follows the RBI Master Direction on Compromise Settlements (June 8, 2023). When an unsecured loan is unpaid past 90 days, it becomes an NPA. Debt advocates submit a hardship file to the bank SARB or Zonal Committee. The bank reviews your case and issues an OTS letter with a 40% to 60% waiver. You pay directly into your loan account and get an official No Dues Certificate.
How do debt settlement advocates in Madurai handle private bank SARB notices and loan recall demands?
When a bank's Stressed Assets Recovery Branch (SARB) sends a demand notice, advocates send a formal legal reply. This reply challenges illegal penal interest under RBI rules. It documents your financial hardship and directs all bank calls to your lawyer. This stops recovery agent visits at once.
What percentage of debt waiver or haircut can borrowers in Madurai expect on personal loans?
Waivers depend on loan delay and verified financial hardship. Banks and NBFCs in Tamil Nadu routinely approve 40% to 65% waivers on total dues. Lenders waive 100% of penal charges and late fees, along with a large discount on the core principal.
How are microfinance loan disputes and fintech app harassment legally resolved in Tamil Nadu?
Microfinance lenders and loan apps in Tamil Nadu must follow RBI digital lending rules. If agents harass you, advocates file complaints with the District Magistrate under the Tamil Nadu Money Lenders Act. We also file grievances with the RBI Integrated Ombudsman to stop abuse and reach a fair settlement.
Can private banks file police complaints or arrest borrowers for personal loan default in Madurai?
No. Loan default is strictly a civil contract matter under the Indian Contract Act, 1872. The Madurai Bench of the Madras High Court has ruled that police cannot intervene in civil loan disputes. Cheque bounce cases under Section 138 NI Act or Section 25 PSSA are bailable matters that can be settled in Lok Adalat.
How does the National Lok Adalat at the Madurai District Court handle loan settlements?
The National Lok Adalat at Madurai District Court offers a safe space for settlement. Bank officers attend with pre-approved discount powers. The Lok Adalat award acts as a final civil court decree. It closes all Section 138 cases with zero court fees.
What is the role of the Madurai Bench of the Madras High Court in protecting loan defaulters?
The Madurai Bench has jurisdiction across southern Tamil Nadu. The court has ruled against recovery agent harassment and police interference in loan defaults. It strictly enforces RBI Fair Practice Codes.
Can a bank in Madurai freeze my salary account or attach property for unsecured personal loans?
Under Section 171 of the Indian Contract Act, 1872 (Banker's General Lien), a bank can only set off funds from accounts in its own branches under the same CIF. It cannot freeze accounts in other banks or seize property for unsecured loans without a court decree.
What forensic checks must be conducted on an OTS sanction letter before making payment?
Check that the OTS letter is on official bank letterhead with a reference number. It must list the exact settlement amount and waiver details. It must state that the loan is closed in full and that all court cases will be withdrawn.
What is the statutory timeline for receiving the No Dues Certificate (NDC) under RBI rules?
Under RBI Circular RBI/2023-24/60, lenders must issue a No Dues Certificate within 30 days of full settlement payment. If the bank delays without cause, it must pay the borrower ₹5,000 for each day of delay.