- Industrial Debt Relief: Factory owners can settle unsecured debt with 40% to 65% OTS waivers.
- Factory Gate Defense: Legal notices stop agent visits under RBI rules.
- Court Protection: Advocates appear in Ludhiana Courts. We challenge arbitration and close cheque bounce cases.
- legal Asset Immunity: Section 60 CPC protects machines and homes from seizure.
- Legal Closure: Settlements end with official NDCs under RBI rules.
1. The Industrial & Salaried Debt Crisis in Ludhiana
Ludhiana is a major manufacturing hub in Northern India. It has textile mills in Focal Point. It has hosiery units in Sundar Nagar. It has bicycle units in Industrial Area B. It has auto parts foundries along GT Road. Local manufacturers face cash flow issues. Long buyer credit cycles and raw material price swings cause cash deficits.
When credit limits max out, owners take unsecured loans. Over time, debt servicing exceeds profits. Borrowers get stuck taking fresh loans to pay older EMIs.
Most loan defaults in Punjab stem from client payment delays. Taking new loans worsens the problem. Engaging debt settlement advocates enables legal compromise under RBI rules.
Salaried workers face pressure from medical bills or job loss. When defaults occur, recovery agents call and visit. Loan default is a civil matter. Strong laws protect you from agent harassment.
2. Statutory Protections & Punjab Indebtedness Laws
Borrowers in Punjab have legal protections under state and central laws. The Punjab Relief of Indebtedness Act, 1934 limits high interest rates. It stops lenders from adding arbitrary fines.
Under the Banking Regulation Act, the RBI enforces fair collection rules. These directives prohibit abusive collection tactics:
Key Statutory Safeguards Enforceable in Punjab
1. Doorstep Visit Restrictions
Agents cannot visit factories or homes without prior notice. Calls must happen between 8:00 AM and 7:00 PM.
2. Penal Protections under Bharatiya Nyaya Sanhita, 2023 (BNS)
Trespassing into commercial sheds or homes violates Section 329 BNS. Threats of arrest or abuse violate Section 351 BNS. Coercive cash demands violate Section 308 BNS.
3. Asset Exemptions under Section 60 CPC
Under Section 60 CPC, tools of trade cannot be seized. Essential factory machines and primary homes stay safe from unsecured debt.
4. Supreme Court Rulings on Recovery Decency
In ICICI Bank Ltd. v. Prakash Kaur (2007), the Supreme Court banned musclemen in loan recovery.
If agencies break rules, we file complaints with the Banking Ombudsman and local magistrates.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Judicial Architecture in Ludhiana
Lenders in Punjab must choose courts based on debt amount.
For unsecured personal loans, banks file in Judicial Courts Complex in Ludhiana:
- Summary Suits under Order 37 CPC: Lenders file suits in Civil Court. Our advocates file Leave to Defend. We dispute extra charges and move cases to regular trials.
- Section 138 NI Act: Banks deposit security cheques to file court complaints. Advocates secure bail. We compound cases under Section 147 NI Act upon settlement.
- DRT Chandigarh: Claims over ₹20 Lakhs go to DRT Chandigarh. Unsecured claims need detailed trial scrutiny.
Fintech lenders often issue arbitration notices in distant cities. Under Supreme Court rulings in Perkins Eastman (2020) and TRF Ltd. (2017), one-sided arbitrator appointments are void. Our advocates invalidate these claims.
4. Bank NPA Accounting in Ludhiana
Banks agree to OTS waivers due to mandatory RBI reserves rules. Under RBI rules, loans become NPAs after 90 days of non-payment.
Once an account becomes an NPA, lenders face strict capital reserves:
- Substandard NPA (Up to 12 Months): 15% mandatory reserves on unsecured exposure.
- Doubtful NPA (12 to 24 Months): 100% reserves on unsecured balances.
- Loss Assets: 100% write-off against reserves.
Civil suits in Ludhiana take 3 to 5 years. They also cost high legal fees. Banks have no assets to seize. Bank committees evaluate settlement offers using Net Present Value math:
Here, C_t is expected recovery and r is discount rate. Deductions cover court delays and locked cash.
An upfront OTS payment gives the bank faster cash value. It beats multi-year court trials. It also releases locked provisions back to profits.
6. Tactical Settlement Protocol in Ludhiana
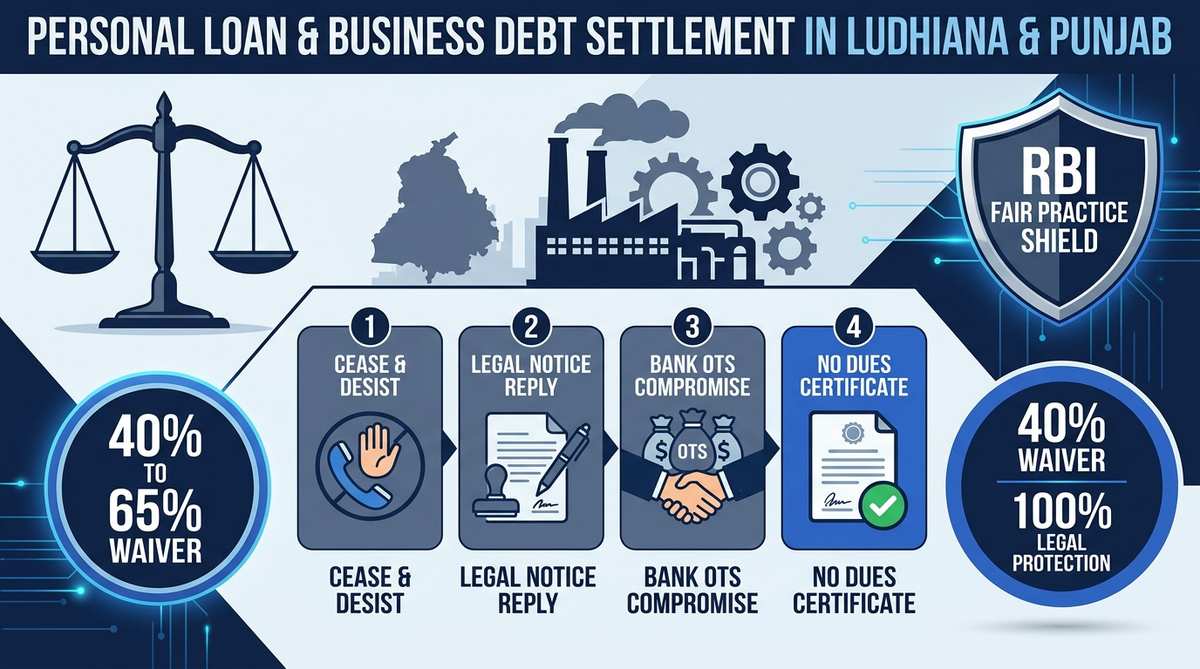
Direct agent payments often go to penal fees instead of principal. SettleLoans follows a 5-step legal process:
Stage 1: Financial Audit
We review sanction letters and statements to find true principal debt.
Stage 2: Cease-and-Desist Notices
We send legal notices to bank Nodal Officers. Lenders must route calls to our lawyers.
Stage 3: Court Protection
We appear in court for Section 138 NI Act cases. We secure bail and prevent ex-parte orders.
Stage 4: Hardship Submission
We submit hardship files to bank committees to win 40% to 65% waivers.
Stage 5: Sanction Verification &. Closure
We verify bank sanction letters. You pay directly to the bank and receive your NDC.
7. Sanction Letter Forensics in Ludhiana
Some recovery agents make fake settlement letters. Paying on fake receipts leaves your loan active.
Our advocates check every settlement letter before you pay:
Checklist for Authentic Bank OTS Sanction Letters
1. Official Bank Letterhead
The letter must come from the bank with a valid reference number.
2. Account Details
The letter must list your PAN and loan numbers.
3. Clear Waiver Terms
The letter must state the agreed sum and waiver terms.
4. NDC &. Case Closure
The letter must promise an NDC and close all court cases.
Pay settlement funds directly to the bank. Never pay cash to recovery agents.
8. ₹0 NDC & Credit Rebuilding in Ludhiana
Under RBI Circular RBI/2023-24/60, lenders must issue an NDC within 30 days of payment.
The bank marks the account as "Settled". with ₹0 dues in credit bureaus. This ends civil liability and stops recovery actions. You can rebuild your credit score step by step:
- Secured Credit Cards: Use secured credit cards. Keep usage under 30%.
- On-Time Payments: Pay monthly utility bills on time.
- Credit Audits: Check CIBIL reports every 3 months. Dispute false overdue remarks.
Within 18 to 24 months, borrowers rebuild scores to 750+.
9. Comparative Protection Matrix for Punjab Borrowers
Here is a comparison of legal rights and settlement options in Punjab:
| Debt Type. | Court Forum. | Lender Action. | Legal Shield. | Settlement &. Timeline. |
|---|---|---|---|---|
| Personal Loans. | Ludhiana Civil Courts. | Order 37 suit or Section 138 notice. | Section 60 CPC asset protection, RBI rules. | 45% to 65% Waiver 2 to 5 Months |
| MSME Business Loans. | Ludhiana Courts / Chandigarh DRT. | Civil suit or DRT claim. | Section 60 CPC protection, MSME rules. | 40% to 60% Waiver 3 to 6 Months |
| Cash Credit / Overdraft Shortfalls. | Chandigarh DRT / District Courts. | Civil suit for balance dues. | Punjab Indebtedness Act protection. | 35% to 55% Waiver 4 to 8 Months |
| Fintech &. NBFC Digital App Loans. | Distant Arbitration / Local Courts. | One-sided arbitration notices. | Supreme Court ruling in Perkins Eastman. | 50% to 70% Waiver 1 to 3 Months |
| Credit Card Balances. | District Courts / Lok Adalat. | Civil suit or Lok Adalat notice. | High interest waiver under RBI rules. | 50% to 65% Waiver 1 to 4 Months |
10. SettleLoans Legal Defense in Ludhiana
Running a factory with high debt needs legal help. SettleLoans provides full debt defense in Punjab. We stop recovery harassment with legal notices. We defend court cases in Ludhiana. We represent you in DRT Chandigarh. We negotiate 40% to 65% OTS waivers with bank desks. We secure authentic NDCs for every client.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Ludhiana
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Ludhiana can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Mini Secretariat, Ferozepur Road, Ludhiana, Punjab - 141001
Jurisdiction: Adjudicates commercial debt recovery notices and Section 138 matters for hosiery, auto components, and trading MSMEs.
Address: ADR Centre, New Judicial Courts Complex, Mini Secretariat, Ludhiana - 141001
Lok Adalat Conciliation: Under Punjab Legal Services Authority (PULSA), operates fast-track compromise settlement benches with enforceable Lok Adalat decrees.
11. FAQs: Ludhiana & Punjab
Clear answers on loan settlement, borrower rights. And court rules across Punjab.
Why should industrial manufacturers in Ludhiana choose legal debt settlement over rolling credit?
Textile and hosiery manufacturers in Ludhiana often take fresh loans to cover cash shortfalls. This increases overall debt. A legal One-Time Settlement (OTS) stops penal interest. It halts factory visits by recovery agents. Borrowers can settle unsecured debt at a 40% to 65% waiver based on audited cash flows.
Can banks in Ludhiana seize factory machinery or ancestral land for an unsecured personal loan?
No. Unsecured personal and business loans have no mortgage on machines or land. Under Section 60 CPC, tools of artisans, machinery, and primary homes cannot be seized without a civil decree.
What legal protection does the Punjab Relief of Indebtedness Act offer distressed borrowers?
The Punjab Relief of Indebtedness Act, 1934 protects borrowers from high interest rates. It limits harsh recovery methods. Combined with RBI rules, our advocates use this law to remove inflated penal charges during settlement talks.
How do debt settlement advocates handle Section 138 NI Act summons at Ludhiana Courts?
When security cheques bounce, banks file Section 138 NI Act cases in Ludhiana Courts. Our advocates appear in court and secure bail. Under Section 147 NI Act, we compound and close the case once the OTS is paid.
How does a debt settlement advocate stop recovery agents from visiting factory premises in Focal Point or Sundar Nagar?
After signing a Vakalatnama, our advocates send legal notices to bank Nodal Officers. Under RBI rules, lenders must direct all calls to your lawyer. This stops doorstep factory visits immediately.
What is the typical waiver percentage achievable in Ludhiana bank loan settlements?
Borrowers in Punjab typically secure 40% to 60% waivers on unsecured personal loans, business loans, and credit cards. Banks also grant a 100% waiver on penal interest and late fees.
How does Chandigarh DRT jurisdiction apply to loan disputes for Ludhiana business owners?
Debts Recovery Tribunals in Chandigarh handle Punjab bank recovery claims above ₹20 Lakhs. For loans under ₹20 Lakhs, banks file in Ludhiana Civil Courts. Long court timelines encourage banks to accept out-of-court OTS settlements.
What happens to CIBIL and Commercial CMR scores after completing a settlement in Punjab?
After you pay the agreed settlement, the lender issues a No Dues Certificate (NDC) within 30 days under RBI rules. The bank marks the account as 'Settled' with ₹0 dues in credit bureaus. You can rebuild your credit score over 12 to 24 months.
Can private fintech apps or NBFCs initiate arbitration in Mumbai or Delhi against Ludhiana residents?
Digital lenders often send arbitration notices in distant cities. Our advocates challenge these notices under Supreme Court rulings in Perkins Eastman and TRF Ltd. We move negotiations back to local Punjab courts.