- Civil Character of Loan Default in Rajasthan: Under the Indian Contract Act, 1872 and established Rajasthan High Court rulings, unsecured loan default is strictly a civil dispute. Local police stations in Jaipur have zero statutory authority to issue call letters, summon borrowers, or register criminal FIRs for debt default.
- Salary Account & Banker's Lien Protections: Under Section 60(1) of the Code of Civil Procedure (CPC) and Section 171 Contract Act doctrines, salaried professionals and government employees are protected against unauthorized sweeps when salary is maintained in a separate unlinked bank.
- Bani Park District Court & Section 138 Defense: Filing a timely legal reply within 15 days of receiving cheque or NACH bounce notices neutralizes criminal exposure in Jaipur Metropolitan Magistrate Courts and compels banks to enter formal OTS conciliation.
- Zonal SARB Haircut Slabs (40%–70%): Negotiating directly with bank Zonal Stressed Assets Recovery Branches located in C-Scheme, MI Road, and Tonk Road unlocks 40% to 70% principal waivers alongside 100% penal interest write-offs.
- Mandatory ₹0 NDC within 30 Days: Under RBI Circular RBI/2023-24/60, lenders must issue the official zero-balance No Dues Certificate within 30 days of settlement payment or pay statutory compensation of ₹5,000 per day of delay.
The Unsecured Debt Dilemma for Salaried Professionals, MSMEs
As the administrative, industrial, and commercial powerhouse of Rajasthan, Jaipur represents a dynamic socio-economic ecosystem. The city is home to major government administrative complexes around the Rajasthan Government Secretariat, Vidhan Sabha, state public sector undertakings such as Rajasthan Rajya Vidyut Utpadan Nigam Limited (RRVUNL) and RSRTC, premier healthcare institutions including SMS Hospital and Fortis Escorts, educational clusters in Jagatpura, bustling IT and business process hubs across Sitapura Industrial Area and Mahindra World City, alongside massive wholesale and retail trade networks in Johari Bazaar, Bapu Bazaar, Mansarovar, Vaishali Nagar, and Vidyadhar Nagar.
Over the past five years, aggressive retail credit expansion by major Public Sector Undertaking (PSU) banks (such as State Bank of India, Punjab National Bank, Bank of Baroda, and Canara Bank) and premier private lenders (including HDFC Bank, ICICI Bank, Axis Bank, and Kotak Mahindra Bank), supplemented by non-banking financial companies (NBFCs) like Bajaj Finance and Tata Capital, resulted in unprecedented disbursement of unsecured personal loans, instant mobile app credit lines, and revolving credit card facilities.
However, sudden involuntary financial crises—arising from commercial supply-chain shocks across Jaipur's gem and jewellery trading sectors, textile export contractions in Sanganer and Sitapura, corporate workforce restructuring in IT corridors, or debilitating family medical emergencies—have severely crippled the monthly debt-servicing capacity of thousands of borrowers. When liquidity evaporates, borrowers face multiple simultaneous equated monthly installment (EMI) defaults. In response, financial institutions assign delinquent loan accounts to aggressive third-party collection agencies operating across C-Scheme, Tonk Road, and Ajmer Road.
These outsourced recovery agencies frequently engage in coercive and unlawful collection tactics: incessant phone calls outside permitted hours, threats of workplace defamation at corporate parks and government offices, unannounced visits to residential colonies in Malviya Nagar, Vaishali Nagar, and Mansarovar, and false claims of imminent arrest by local police. Borrowers must recognize that such intimidatory tactics directly violate Reserve Bank of India directives, and robust legal avenues exist to halt harassment permanently while securing substantial debt waivers through structured compromise settlements.
NPA Classification Aging & Rajasthan High Court Debt Protections
Successfully securing an optimal personal loan settlement in Jaipur requires an in-depth understanding of the Reserve Bank of India's Prudential Norms on Income Recognition, Asset Classification and Provisioning (IRACP). Commercial banks and NBFCs do not entertain deep compromise negotiations during the initial weeks of default. Substantive One-Time Settlement (OTS) opportunities materialize as the delinquent account progresses through standardized statutory aging brackets.
During the first 90 days of non-payment, the loan account is categorized as a Special Mention Account (SMA-0 for 1–30 days, SMA-1 for 31–60 days, and SMA-2 for 61–90 days). When default surpasses the 90-day mark, the lending institution is mandated under RBI regulations to categorize the debt as a Non-Performing Asset (NPA). Upon NPA classification, the bank must transfer mandatory capital provisions from its operational profits (ranging from 15% to 25% for Substandard assets, 40% to 100% for Doubtful assets, and 100% for Loss assets).
| Delinquency Stage | Aging Threshold | Mandatory Provisioning | Institutional Strategy & OTS Haircut Scope |
|---|---|---|---|
| SMA-0 & SMA-1 | 1 – 60 Days Overdue | Standard Capital Buffer | Automated reminder notices, collection calls, NACH bounce fees. Substantive debt waivers unavailable. |
| SMA-2 | 61 – 90 Days Overdue | Pre-NPA Watchlist | Pre-NPA demand notices issued, recovery agency escalation. Loan restructuring or tenure extension possible. |
| Substandard NPA | 91 – 365 Days Overdue | 15% – 25% Profit Provision | Account transferred to Zonal SARB desks in C-Scheme/Tonk Road. 35%–50% principal haircuts become viable. |
| Doubtful (D1 / D2) | 1 – 3 Years Overdue | 40% – 100% Capital Lock | Lenders prioritize balance sheet cleanup over legal friction. 50%–65% principal haircuts achievable. |
| Loss Asset | 3+ Years Overdue | 100% Written-off Balance | Account fully written off in institutional books. Deep One-Time Settlements (up to 70% haircut) via Lok Adalat. |
The Hon'ble Rajasthan High Court (Jaipur Bench) has established across multiple authoritative judgments that financial institutions and recovery agencies cannot adopt strong-arm, coercive, or extra-judicial recovery measures. The court has repeatedly affirmed that commercial lenders are vicariously liable for unlawful harassment committed by recovery agents, holding that all debt recovery must strictly follow established civil due process.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Defending Statutory Notices in Jaipur District Courts (Bani Park) & CJM Courts
When electronic National Automated Clearing House (NACH) mandates or physical cheques bounce due to insufficient funds, bank legal departments issue statutory legal notices. These notices are dispatched under Section 25 of the Payment and Settlement Systems Act, 2007 (PSSA) or Section 138 of the Negotiable Instruments Act, 1881, warning of criminal complaint proceedings across Jaipur's judicial magistrate courts seated at the District Court Complex in Bani Park, Jaipur Metro-I, and Jaipur Metro-II.
Receiving a statutory legal notice demands prompt, professional advocate intervention. Under the law, a borrower is entitled to a mandatory 15-day statutory response window from the date of receipt. Ignoring a statutory demand notice allows the lender to file a formal complaint under Section 142 of the NI Act, resulting in judicial summons and potential bailable warrants if left unrepresented.
A seasoned debt defense advocate drafts a comprehensive legal reply within the 15-day window. The reply formally places on record: (a) The total absence of fraudulent intent or mens rea at loan inception; (b) Documented proof of involuntary financial hardship (such as medical records, salary reductions, corporate layoff documentation, or certified business balance sheets); (c) Substantive legal objections challenging inflated compound interest, unnotified penalty levies, and unlawful bounce charges; (d) A bona fide proposal for amicable compromise resolution under RBI master guidelines.
Placing an assertive legal defense on record fundamentally alters the bank's recovery calculus. Because prosecuting a complaint through crowded magistrate courts in Bani Park involves years of procedural hearings, advocate fees, and witness testimonies, bank legal officers routinely prefer directing accounts with structured advocate replies toward the Zonal Stressed Assets Recovery Branch or the National Lok Adalat for an expedited compromise settlement.
Banker's Right of General Lien (Section 171) & Salary Account Protection
A critical operational risk for salaried professionals and government employees in Jaipur is the Banker's Right of General Lien and Set-Off under Section 171 of the Indian Contract Act, 1872. This statutory provision enables a lending bank to unilaterally debit funds, freeze balances, or appropriate credits from any savings account, fixed deposit, or salary account maintained within that exact same banking institution under the matching Customer Information File (CIF) or PAN.
For example, if a borrower defaults on an unsecured personal loan with State Bank of India, Punjab National Bank, or HDFC Bank while maintaining their active Rajasthan State Government IFMS salary account or corporate savings with the same institution, the bank's core banking system can automatically sweep incoming salary credits upon an EMI default. This sudden appropriation can leave a family without essential funds for food, rent, utility bills, or emergency medical care.
However, this right of set-off possesses definitive legal boundaries: a lending bank cannot attach, freeze, or appropriate monies deposited in separate, independent banking institutions without obtaining a formal decree or interim attachment warrant from a competent Civil Court. Moreover, under Section 60(1)(i) and 60(1)(l) of the Code of Civil Procedure (CPC), 1908, statutory salary attachment exemptions strictly protect subsistence income, mandatory allowances, and provident fund accumulations from civil execution.
Borrowers facing imminent default must immediately ring-fence their monthly subsistence by updating their employer payroll records to an independent bank where they have no existing credit liabilities and revoking standing NACH electronic mandates.
Personal Loan Settlement Roadmap in Jaipur & Rajasthan
The visual roadmap below details the complete stage-by-stage debt resolution lifecycle in Jaipur—from financial distress audit and Bani Park court notice defense to RBI anti-harassment shielding, Zonal SARB negotiations, and final ₹0 No Dues Certificate delivery.
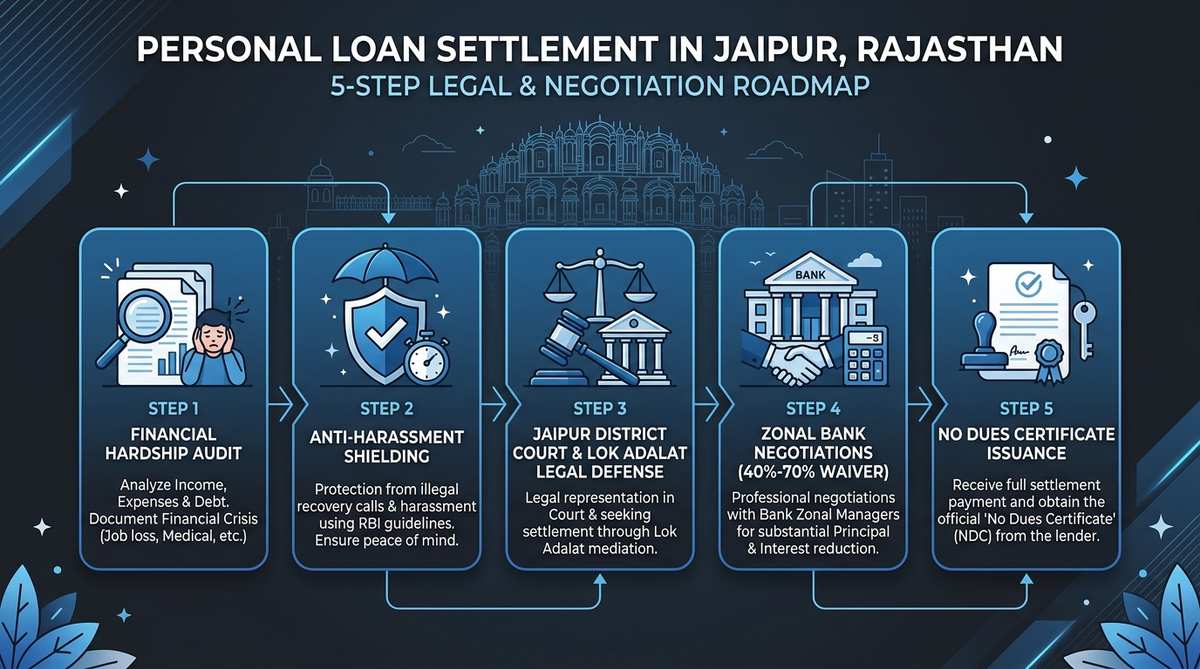
Figure 1.0: End-to-End Jaipur Debt Settlement Framework, Court Notice Defense & Zonal SARB Resolution Protocol.
OTS Haircut Mechanics & The Net Present Value (NPV) Recovery Benchmark
Under the Reserve Bank of India's Master Directions on Resolution of Stressed Assets and board-approved compromise policies, financial institutions assess One-Time Settlement proposals through rigorous financial economics rather than discretionary sympathy. While outsourced recovery agents often claim that banks never reduce outstanding dues, Zonal Settlement Committees located in C-Scheme, MI Road, and Tonk Road evaluate every non-performing asset against an institutional Net Present Value (NPV) Recovery Valuation Benchmark.
When an unsecured personal loan defaults, the lending bank faces substantial ongoing legal and financial friction. If the bank initiates civil recovery proceedings through an Order 37 summary suit in a Jaipur Civil Court or approaches a Debt Recovery Tribunal (DRT for debts exceeding ₹20 Lakhs), it must remit ad-valorem court fees, retain standing counsel, and navigate 4 to 7 years of court delays. Furthermore, because unsecured loans lack hypothecated collateral, the final probability of cash recovery through asset attachment remains minimal.
Where C_t represents estimated recoveries, r is the discount rate, and deductions account for 3–5 years of court friction and capital locked in NPA provisions.
When a borrower presents an immediate lump-sum or structured compromise proposal through qualified legal advocates, the bank avoids protracted litigation expenses, recovers liquid capital, and immediately writes back 100% of its locked regulatory provisions into its quarterly profit ledger. Due to this financial calculation, bank credit committees routinely sanction compromise settlements offering 40% to 70% principal waivers, alongside a complete 100% write-off of accumulated penal interest, overdue charges, and administrative levies.
Enforcing the RBI Fair Practices Code & Restricting Police Interference in Jaipur
Borrowers facing coercive debt collection in Jaipur and Rajasthan are protected by comprehensive statutory regulations established by the central banking regulator. The Reserve Bank of India Master Directions on Recovery Agents (2022) strictly prescribe recovery conduct and impose substantial penalties on non-compliant institutions.
Under the RBI Fair Practices Code: (1) Recovery agents are strictly barred from contacting borrowers prior to 08:00 AM or after 07:00 PM; (2) Agents cannot use abusive language, intimidation, or harassment; (3) Agents are strictly prohibited from contacting government department heads, HR managers, workplace colleagues, or family relatives; (4) Recovery personnel conducting home visits must carry formal bank authorization letters, display official employee identification, and maintain privacy; (5) Continuous, repetitive calling designed to disturb peace of mind constitutes an actionable regulatory offense.
Furthermore, recovery agents frequently threaten to lodge criminal complaints with local police stations in Mansarovar, Vaishali Nagar, or Bani Park. Under Supreme Court rulings in Arnesh Kumar v. State of Bihar and Lalita Kumari v. Government of UP, police officers cannot entertain commercial debt complaints or issue informal police station call letters for civil loan defaults.
When collection agencies breach these mandatory norms, our legal team dispatches formal cease-and-desist notices to the lending institution's Principal Nodal Officer and Board of Directors, while simultaneously filing complaints with the Jaipur Police Commissionerate, the Cyber Crime Police Station, and the RBI Integrated Ombudsman Portal (CMS). Faced with regulatory exposure, lenders promptly order collection agencies to cease all direct contact.
5-Step Legal Protocol for Settling Personal Loans with Jaipur Zonal Desks
Achieving a legally binding One-Time Settlement with PSU and private commercial banks in Jaipur requires executing a structured, advocate-led five-stage roadmap that bypasses outsourced tele-callers and negotiates directly with authorized zonal credit desks:
Financial Hardship Dossier Compilation & Liability Audit
Our legal advocates conduct an exhaustive forensic audit of your total loan liability across all lending institutions. We construct an unassailable financial hardship dossier—incorporating corporate termination letters, medical treatment records, bank statements demonstrating cash exhaustion, and GST returns showing business downturns—documenting genuine incapacity to sustain regular EMIs.
Cease-and-Desist Notice & Harassment Shielding
We serve formal legal notices invoking the RBI Master Directions on Recovery Agents to the bank's Principal Nodal Officer and collection departments. This immediately shields your government office or private workplace, family members, and residence from unauthorized visits and intimidatory phone calls.
Statutory Notice Reply in Bani Park & CJM Courts
If the lender dispatches Section 25 PSSA or Section 138 NI Act demand notices returnable to Jaipur magistrate courts, our advocates draft and serve comprehensive legal replies within the statutory 15-day window, preventing magistrate escalations and directing the lender toward compromise conciliation.
Direct Negotiations with C-Scheme & Tonk Road Zonal SARB Desks
We bypass third-party collection agencies entirely and submit structured One-Time Settlement proposals directly to the bank's Stressed Assets Recovery Branch (SARB) and Zonal Settlement Committees located in C-Scheme, MI Road, and Tonk Road, securing maximum principal waivers (40% to 70%).
Sanction Letter Forensic Audit, Direct Payment & NDC Issuance
We audit the bank's official stamped OTS Sanction Letter to ensure unambiguous debt extinguishment clauses. You remit the agreed settlement amount strictly into your loan account via RTGS/NEFT, followed by our enforcement of the mandatory zero-balance No Dues Certificate under RBI directives.
Sanction Letter Forensics, Mandatory ₹0 NDC & 24-Month CIBIL Repair
A critical danger for distressed borrowers in Jaipur is releasing money based on verbal assurances, unofficial SMS messages, or unauthorized WhatsApp letters shared by recovery agents. Unauthorized collection callers frequently persuade borrowers to deposit partial token amounts, only for those funds to be credited against accrued penal charges while the loan remains active and compounding.
Before any settlement funds are released, our legal advocates verify five essential forensic criteria in the bank's OTS Sanction Letter: (1) It must be printed on official bank letterhead bearing authentic branch seals and officer employee codes; (2) It must clearly state the exact loan account number and compromised settlement amount; (3) It must specify an achievable payment schedule; (4) It must contain an explicit debt extinguishment clause confirming that upon payment, all remaining balance dues stand permanently waived with full withdrawal of legal actions; (5) It must mandate the issuance of a formal zero-balance No Dues Certificate.
Under RBI Circular RBI/2023-24/60, all regulated lenders are legally required to deliver the official No Dues Certificate (NDC) / Loan Closure Certificate and update credit bureau records within 30 calendar days of receiving full settlement payment. If the lender fails to provide the NDC within 30 days due to operational delays, it is statutorily mandated to pay compensation of ₹5,000 for each day of delay directly to the borrower.
Following settlement, the bank reports the account status across all four credit bureaus (CIBIL, Experian, Equifax, CRIF High Mark) as 'Settled' or 'Post-Write-off Settled' with an outstanding balance of ₹0. While this closure permanently terminates active delinquency reporting, it results in a temporary credit score drop and triggers an RBI-mandated 12-month cooling period. Borrowers can systematically rebuild their CIBIL score back to 750+ within 18 to 24 months through disciplined credit rehabilitation, such as utilizing secured fixed-deposit credit cards and maintaining credit utilization below 30%.
Comparing Debt Resolution Pathways for Borrowers in Rajasthan
Evaluating all available legal and financial debt resolution avenues in Rajasthan helps borrowers select the optimal strategy based on debt quantum, financial capacity, and speed of execution:
| Resolution Pathway | Principal Haircut Range | Legal Binding Finality | CIBIL Bureau Status | Resolution Timeline |
|---|---|---|---|---|
| Direct Zonal SARB Settlement (Jaipur) | 40% – 70% Principal Haircut | Complete (Bank NDC Issued) | 'Settled' / ₹0 Dues | 3 to 6 Weeks |
| Rajasthan State Lok Adalat (RSLSA Bani Park) | 45% – 70% Principal Haircut | Absolute (Civil Court Decree) | 'Settled' / ₹0 Dues | Quarterly Lok Adalat Cycles |
| Bank Loan Restructuring | 0% Haircut (Tenure Extension) | Conditional on Monthly EMI | 'Restructured' / Active Debt | 2 to 4 Weeks |
| Civil Court Litigation (Bani Park / HC) | Uncertain (Judicial Discretion) | Subject to Multi-Year Appeal | 'Suit Filed' / Compounding | 4 to 7 Years |
Premier Loan Settlement & Legal Defense Services in Jaipur
Navigating unpayable unsecured debt across Jaipur, Mansarovar, and Vaishali Nagar requires decisive legal representation to stop collection agency harassment, defend statutory notices in Bani Park courts, and negotiate directly with bank Zonal Credit Committees for maximum debt relief. SettleLoans provides end-to-end legal and financial advocacy to help borrowers across Rajasthan reclaim their financial freedom.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
Frequently Asked Questions on Debt Settlement in Jaipur
Why do borrowers in Jaipur require specialized debt settlement advocates?
Salaried executives in Sitapura and Malviya Nagar, state government personnel, and MSME business owners across Mansarovar, Vaishali Nagar, and Johari Bazaar encounter aggressive recovery tactics during unexpected financial distress. Outsourced recovery agencies frequently use threats of police intervention, workplace disclosure, and unauthorized home visits. Specialized Jaipur debt settlement advocates assert RBI Fair Practices protections, enforce Code of Civil Procedure salary exemptions, issue formal cease-and-desist notices to bank zonal offices in C-Scheme and MI Road, and negotiate structured One-Time Settlements (OTS) with 40% to 70% waivers.
Can a bank freeze my salary or savings account under Banker's Lien in Jaipur?
Under Section 171 of the Indian Contract Act, 1872, a bank possesses a general right of lien only over funds deposited within branches of that identical banking institution under the same Customer Information File (CIF). Lenders cannot freeze, debit, or attach salary accounts held at separate, unlinked banks without an explicit decree or attachment order from a competent Civil Court. Under Section 60(1) of the Code of Civil Procedure (CPC), statutory salary attachment exemptions strictly safeguard essential subsistence earnings.
Can Jaipur Police arrest or summon me for defaulting on an unsecured personal loan?
No. Unsecured personal loan and credit card default is strictly a civil contractual breach governed by the Indian Contract Act, 1872. The Jaipur Police Commissionerate, local police stations in Mansarovar, Vaishali Nagar, Vidhyadhar Nagar, or Sanganer have no statutory jurisdiction to register criminal FIRs, issue summons, or detain borrowers for financial default. Under Supreme Court precedents in Arnesh Kumar and Lalita Kumari, police authorities are strictly barred from interfering in civil commercial recovery matters.
How should I respond to a Section 138 NI Act or Section 25 PSSA notice from Jaipur District Courts?
Upon receiving a statutory demand notice for an electronic NACH bounce (Section 25 PSSA) or cheque bounce (Section 138 NI Act), you have a mandatory 15-day statutory window to respond. Empanelled Jaipur advocates draft a comprehensive legal reply establishing involuntary financial hardship, disputing unlawful penal charges, and proposing amicable compromise terms. If a complaint is filed at the Bani Park District Court or CJM Metro Court, our advocates enter appearance under Vakalatnama, secure bail, and direct the case to the National Lok Adalat for an agreed OTS compromise decree.
How does the Rajasthan State Legal Services Authority (RSLSA) Lok Adalat facilitate loan settlement in Jaipur?
The Rajasthan State Legal Services Authority (RSLSA) and District Legal Services Authority (DLSA) conduct National Lok Adalats quarterly across the Bani Park District Court Complex and Rajasthan High Court Jaipur Bench premises. Pre-litigation and pending recovery matters placed before the Lok Adalat bench are settled through mutually agreed compromise. Under Section 21 of the Legal Services Authorities Act, 1987, the Lok Adalat award carries the force of a final Civil Court decree with zero appeal, full refund of court fees, and permanent immunity from future litigation.
Can the complete loan settlement process in Jaipur be executed digitally?
Yes. SettleLoans operates a fully remote, legally protected advisory infrastructure. From financial hardship docket compilation, drafting legal replies, coordinating with Zonal Stressed Assets Recovery Branches (SARB) across C-Scheme, Tonk Road, and MI Road, to auditing official bank sanction letters, every step is conducted securely online. When physical court representation is required in Bani Park or CJM courts, our empanelled Jaipur advocates represent you under Vakalatnama.
What percentage of debt waiver is achievable through bank OTS in Jaipur?
Depending on delinquency aging (90 to 180+ days past due), asset classification (Substandard, Doubtful, or Loss Asset), and documented financial distress (business revenue loss, job layoff, medical emergencies), Jaipur debt settlement advocates routinely secure 40% to 70% waivers on total book outstanding, alongside a complete 100% waiver of accumulated penal interest, compounding levies, and late fees.
How do advocates protect Jaipur borrowers from aggressive recovery agent visits?
Advocates issue formal Cease-and-Desist notices citing RBI Master Directions on Recovery Agents and Section 35A of the Banking Regulation Act. The notice bars third-party recovery agencies from visiting corporate IT offices in Sitapura or Malviya Nagar, government departments, or private residences. Any violation triggers immediate statutory complaints to the bank's Principal Nodal Officer, the RBI Banking Ombudsman (CMS Portal), and the Jaipur Police Commissionerate.
What is the mandatory timeline for banks to issue a No Dues Certificate (NDC) after loan settlement?
Under RBI Circular RBI/2023-24/60, all regulated commercial banks and NBFCs must deliver the official No Dues Certificate (NDC) / Loan Closure Certificate and update credit bureau records within 30 calendar days of receiving full settlement payment. Failure to provide closure documents within 30 days makes the lender liable to pay mandatory compensation of ₹5,000 per day of delay directly to the borrower.