- Zero Collateral Vulnerability: Unsecured loans carry no legal claim against agricultural land, APMC trading stock, or homes.
- Workplace & Commercial Shield: RBI Fair Practices Code explicitly forbids agents from visiting mandi shops, plants, or offices.
- Judicial Notice Defense: Advocate representation before Hubli JMFC courts converts Section 138 NI Act summons into compoundable settlements.
- 40% to 60% Principal Haircuts: Banks execute substantial write-offs under the RBI Compromise Framework to avoid protracted civil trials.
- Statutory ₹0 NDC Delivery: Lenders are legally bound under RBI Circular RBI/2023-24/60 to deliver formal closure certificates within 30 days.
Commercial Debt Realities in Hubli-Dharwad & Belgaum
The twin cities of Hubli and Dharwad represent the commercial spine of North Karnataka. The local economy combines large-scale agricultural trade through the Hubli APMC Market Yard, precision engineering and fabrication units across Tarihal, Gokul, and Belur Industrial Estates, and an expanding IT workforce centered at Aryabhata Tech Park and Deshpande Startups. While this economic mix drives significant commerce, it also exposes local traders, manufacturers, and professionals to severe cyclical liquidity disruptions.
Cotton and agricultural commodity traders in Hubli operate on extended informal credit cycles, frequently waiting months for receivables from textile mills across Maharashtra and Tamil Nadu. When harvest yields suffer or mill payments stall, working capital evaporates. To maintain daily trade operations, proprietors often access unsecured personal credit lines and high-interest digital facilities. Compounding interest rapidly turns manageable business lines into critical debt traps.
Similarly, engineering ancillary units in Tarihal face elongated payment cycles from automotive manufacturers, while transport operators along NH-48 navigate fuel inflation. In the tech sector, salaried software engineers in Hubballi IT Park face contract terminations or family emergencies, triggering personal loan and credit card spirals. Recognizing that default arises from genuine commercial volatility enables borrowers to pursue structured advocate-led compromise settlements under Reserve Bank of India directions.
Unsecured Debt Rights & Civil Asset Protection in Karnataka
When borrowers default on unsecured personal loans, institutional recovery channels often deploy aggressive psychological threats, claiming bank officers can seize commercial premises or auction residential homes. Under Indian jurisprudence, these assertions are completely baseless. Unsecured loans are governed strictly by the Indian Contract Act, 1872. Lenders hold zero mortgage, deed deposit, or hypothecation lien over any asset. Consequently, banks cannot invoke the SARFAESI Act, 2002, or obtain executive eviction orders.
To enforce an unsecured debt, a lender must file an ordinary summary suit under Order XXXVII of the Code of Civil Procedure (CPC) in local civil courts. Even if a money decree is granted after years of litigation, Section 60(1) of the CPC strictly exempts tools of artisans, agricultural implements, and residential premises from judicial attachment. This statutory immunity protects borrowers from asset loss and provides our banking advocates powerful legal leverage during compromise negotiations.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Anti-Harassment Shields & RBI Recovery Regulations
Borrowers across Hubli, Dharwad, and Belgaum frequently encounter coercive collection tactics from outsourced agencies. Agents often stage disruptive visits at APMC shops, trespass into Tarihal factories, or contact colleagues and relatives. These actions violate Reserve Bank of India Master Directions and the Fair Practices Code (RBI/2022-23/108), which prohibit calls outside 08:00 AM to 07:00 PM, abusive conduct, third-party debt disclosure, and unannounced workplace visits.
The High Court of Karnataka Dharwad Bench has consistently affirmed that debt recovery must follow due process rather than coercive intimidation. When harassment occurs, our advocates issue formal cease-and-desist notices to bank Principal Nodal Officers. If violations continue, we register complaints with the Hubli-Dharwad Police Commissionerate under the Bharatiya Nyaya Sanhita (BNS) for criminal intimidation and criminal trespass, while filing regulatory complaints with the RBI Ombudsman.
Defending Section 138 & Arbitration in Dharwad Courts
Beyond 90 days of default, financial institutions typically issue legal notices under Section 138 of the Negotiable Instruments Act, 1881, for security cheques, or Section 25 of the Payment and Settlement Systems Act (PSSA), 2007, for failed NACH debits. While a summons from the Hubli or Dharwad JMFC court causes anxiety, it represents manageable civil litigation. Our advocates file comprehensive replies establishing documented commercial distress, secure prompt bail, and guide proceedings toward Lok Adalat settlement.
Lenders also initiate unilateral arbitration seated in distant metros like Delhi or Mumbai without mutual consent. Under Section 12(5) of the Arbitration and Conciliation Act and the Supreme Court ruling in Perkins Eastman, unilateral arbitrator appointments are void ab initio. We challenge the arbitrator's jurisdiction, halt arbitrary proceedings, and compel lenders to resolve disputes through the National Lok Adalat in Dharwad, securing binding compromise decrees.
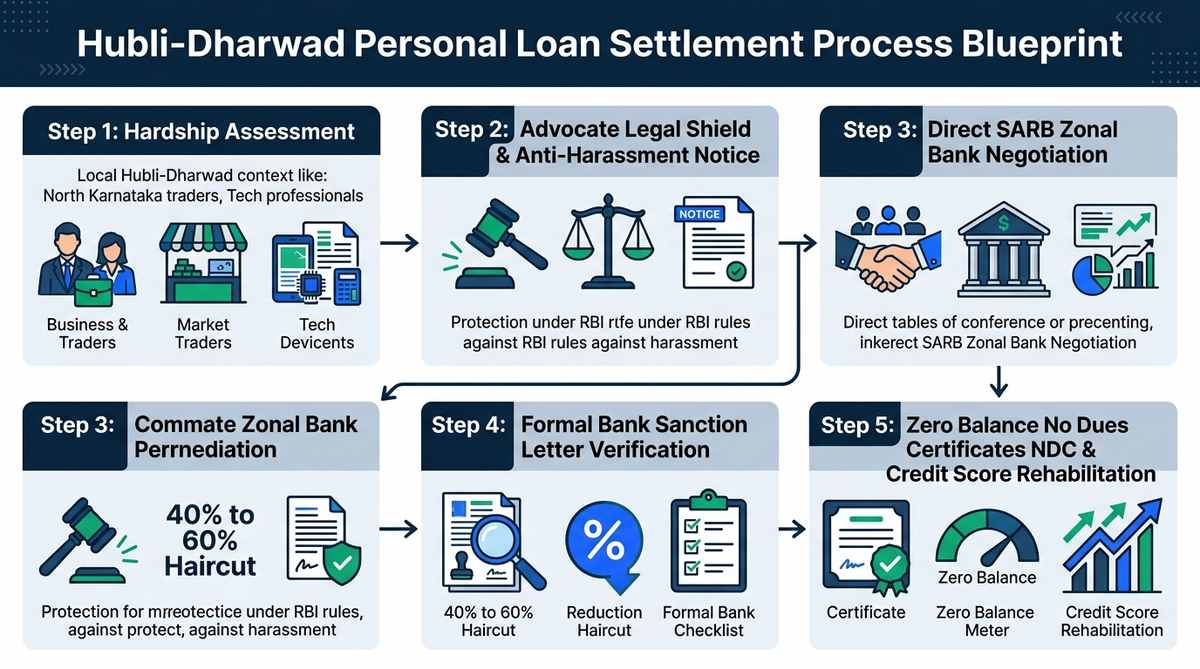
5-Step Loan Settlement & Debt Compromise Framework
NPV Recovery Math & Bank Provisioning in North Karnataka
Financial institutions agree to waive 40% to 60% of an unsecured loan balance because of mandatory Reserve Bank of India accounting rules. Overdue accounts progress through Special Mention Account stages (SMA-0, SMA-1, SMA-2). Once non-payment crosses 90 days, the loan becomes a Non-Performing Asset (NPA). Under Ind AS 109 Expected Credit Loss norms, banks must allocate 15% to 100% in capital provisions, locking operational liquidity that could otherwise generate profitable credit.
Where C_t represents estimated recoveries, r is the discount rate, and deductions account for 3–5 years of court friction and capital locked in NPA provisions.
During settlement evaluations, bank Zonal SARB desks in Hubli apply Net Present Value (NPV) recovery models. Pursuing contested litigation over 3 to 6 years incurs high legal fees and court friction with uncertain returns. An upfront cash settlement of 40% to 55% releases locked capital provisions and cleans bad debt from bank balance sheets immediately. Our advocates utilize this financial calculation to secure optimal terms for borrowers.
Step-by-Step OTS Negotiation Protocol in Hubli-Dharwad
Securing a legally sound loan compromise requires disciplined procedural execution. Our banking advocates manage the resolution process through five established stages:
1Hardship Dossier Compilation & Financial Forensics
We audit loan statements, interest calculations, and bank fee levies. We compile supporting records—such as APMC receipts, reduced GST filings, or medical reports—to establish verified financial hardship.
2e-NACH Mandate Revocation & Legal Shield Activation
We formally cancel active e-NACH mandates under NPCI guidelines to prevent continuous bounce charges. We issue statutory representation notices requiring lenders to direct all communication solely to our advocates.
3Direct Escalation to Hubli Zonal SARB Leadership
We bypass recovery agencies completely. We submit formal OTS proposals under the RBI Compromise Framework directly to Zonal SARB authorities in Hubli or Belgaum holding authentic sanctioning powers.
4Multi-Round Haircut Negotiation & 100% Fee Elimination
We secure complete waivers on 100% of accumulated penal interest, late fees, and processing charges under RBI lending directives, while negotiating a 40% to 60% haircut on the legitimate principal balance.
5Sanction Letter Forensic Audit & ₹0 NDC Delivery
Our advocates verify the bank sanction letter before payment. Funds are remitted directly to the designated loan account, and we enforce delivery of the formal No Dues Certificate within thirty days.
Sanction Letter Forensic Audit & RBI NDC Mandate
A major hazard for borrowers involves fraudulent settlement receipts issued by rogue recovery agents seeking to meet monthly targets. Agents often forge compromise letters and divert payments into third-party accounts, leaving the debt unpaid. SettleLoans conducts a strict forensic audit of every sanction letter, verifying official letterhead, branch seals, employee codes, unique CBS reference numbers, and non-liability closure clauses.
Under RBI Circular RBI/2023-24/60, all regulated commercial banks and NBFCs are legally mandated to release documentation and issue a formal No Dues Certificate within thirty calendar days of settlement. If lenders delay unjustifiably, they must pay statutory compensation of ₹5,000 for each day of default. Our legal team guarantees complete compliance with this protection.
CIBIL Score Rehabilitation for North Karnataka Borrowers
Following a successful compromise settlement, lenders report the loan as 'Settled' across CIBIL, Experian, Equifax, and CRIF High Mark. While 'Settled' reflects an agreed discount, it permanently closes the account, establishes an active ₹0 outstanding balance, and halts damaging monthly delinquency reporting. This is far better than leaving an account in ongoing NPA default.
Once the ₹0 balance updates in credit files, borrowers can rebuild their CIBIL score back above 750 within 18 to 24 months. Our advisors guide clients to obtain a small fixed-deposit-backed credit card, maintain utilization under 30%, and automate complete billing clearances, steadily restoring credit eligibility for future commercial or home financing.
Comparative Matrix of Debt Resolution Legal Routes
Borrowers facing severe loan defaults in Hubli-Dharwad have multiple legal resolution avenues. The matrix below summarizes key options, expected haircuts, client effort, and legal outcomes:
| Resolution Route | Statutory Mechanism | Haircut Potential | Client Stress Level | Legal Finality |
|---|---|---|---|---|
| Advocate-Led Bank OTS | RBI Compromise Settlement Framework (2023) | 40% – 60% Principal Haircut | Minimal (Handled by banking advocates) | Complete legal discharge with ₹0 NDC |
| National Lok Adalat | Legal Services Authorities Act, 1987 (Conciliation) | 45% – 60% Debt Reduction | Low (Single appearance with legal counsel) | Non-appealable Civil Court Decree |
| Arbitration Defense | Section 12(5) Arbitration Act & Perkins Eastman Plea | Converts proceedings into OTS negotiations | Moderate (Managed through formal legal replies) | Quashing of one-sided awards or local transfer |
| Section 138 / 25 PSSA Defense | Magistrate Court Defense on Bounced Auto-Debits | 35% – 50% Settlement Compromise | Moderate (Advocate court appearance and bail) | Compoundable criminal dismissal with full release |
Why Borrowers in Hubli-Dharwad Trust SettleLoans
SettleLoans provides advocate-led debt resolution built for North Karnataka. We represent agricultural traders, industrial proprietors, transport operators, and corporate personnel across Hubli, Dharwad, and Belgaum. Our banking lawyers halt collection harassment, defend court summons, invoke CPC asset protections, and negotiate 40% to 60% waivers directly with bank Zonal SARB desks.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
Frequently Asked Questions: Hubli-Dharwad Debt Relief
How does advocate-led loan settlement work in Hubli-Dharwad?
Our advocates submit a documented hardship dossier to bank Zonal Stressed Assets Recovery Branches (SARB). We negotiate complete penal fee waivers and a 40% to 60% principal reduction, concluding with an audited sanction letter and ₹0 NDC.
Can recovery agents visit my shop in APMC Yard or factory in Tarihal?
No. Under the RBI Fair Practices Code, agents cannot visit shops, factories, or offices without prior permission. Our advocates issue formal cease-and-desist notices to bank nodal officers to stop workplace visits.
Can banks seize my machinery, agricultural produce, or home for personal loans?
No. Unsecured loans hold no mortgage or hypothecation. Section 60(1) of the Code of Civil Procedure explicitly protects artisan tools, agricultural implements, and residential premises from attachment under money decrees.
How do your advocates handle Section 138 NI Act notices in Dharwad courts?
We file structured legal replies establishing absence of criminal intent and genuine commercial distress. Our advocates appear before the JMFC court and redirect the dispute to National Lok Adalat for an out-of-court compromise decree.
What percentage of loan waiver can borrowers in North Karnataka expect?
Borrowers with unsecured debts overdue past 90 to 180 days typically secure 40% to 60% principal write-offs during an OTS. Accumulated penal interest and late payment charges are completely waived.
Why do commercial banks in Hubli agree to substantial OTS haircuts?
Under Ind AS 109 rules, NPA accounts require up to 100% capital provisioning. Because civil recovery suits take 3 to 6 years of legal costs, immediate OTS lump sums yield banks superior Net Present Value (NPV).
Can banks initiate arbitration in Mumbai or Delhi for loans taken in Hubli?
No. Under Section 12(5) of the Arbitration Act and the Supreme Court Perkins Eastman precedent, unilateral appointments are void. We challenge jurisdiction and enforce dispute resolution locally in Karnataka.
How long does it take to obtain the No Dues Certificate (NDC)?
Under RBI Circular RBI/2023-24/60, banks must issue the No Dues Certificate within 30 days of payment. Unjustified delays make the lender liable to pay ₹5,000 per day in statutory compensation.
How can I restore my credit score after a personal loan settlement?
Settlement updates bureau balances to ₹0. You can rebuild your CIBIL score to 750+ within 18 to 24 months by maintaining disciplined payments on a fixed-deposit-backed secured card with utilization under 30%.
What documentation is required to initiate loan settlement in Hubli-Dharwad?
You need loan sanction letters, latest statements, income proofs or GST filings showing reduced revenue, medical documents where applicable, and copies of notices received from lenders.
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Master Circular: Fair Practices Code for Lenders, Recovery Agent Directives & Mandatory Calling Caps
- High Court of Karnataka (Dharwad Bench): Judicial Precedents on Banking Due Process, Criminal Quashing & Fair Debt Recovery
- Reserve Bank - Integrated Ombudsman Scheme: Statutory Redressal Mechanism for Unlawful Recovery Intimidation & NDC Delay
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987 • Pre-Litigation Lok Adalat Compromise Decrees