- Civil Nature of Default: Unsecured loan default is a civil contractual breach. Police stations across Gwalior, Morena, and Bhind possess zero authority to register FIRs or summon borrowers.
- Salary & Account Shielding: Under Section 60(1) CPC and Section 171 Contract Act rules, banks cannot attach salaries or touch deposits held in unlinked external banks.
- MP High Court Safeguards: The MP High Court Bench at Gwalior enforces strict adherence to due process, prohibiting recovery musclemen tactics under Article 226 of the Constitution.
- Zonal SARB Waivers (40%–70%): Negotiating directly with bank Zonal Stressed Assets branches in City Centre secures 40% to 70% principal waivers and 100% penal write-offs.
- Mandatory ₹0 NDC within 30 Days: Under RBI Circular RBI/2023-24/60, lenders must deliver an authentic zero-balance No Dues Certificate within thirty days, subject to ₹5,000 daily delay fines.
Economic Dynamics & Debt Pressures in Gwalior & Chambal
Gwalior serves as the judicial and economic hub of northern Madhya Pradesh. The region hosts an extensive workforce across Morar Cantonment defense units, North Central Railway, Jiwaji University, ABV-IIITM, and government departments. Alongside public employment, commercial markets thrive across Maharaj Bada, Sarafa Bazar, Daulat Ganj, Topi Bazar, Thatipur, and Hazira, linking with agro-processing in Morena and transport mandis in Bhind.
Aggressive lending by banks like SBI and PNB, alongside NBFCs like Bajaj Finance, Fullerton, and Aditya Birla Capital, created heavy unsecured debt. Inflation, business downturns, and medical emergencies frequently trigger defaults past ninety days. Lenders promptly assign delinquent files to third-party recovery agencies operating across City Centre and Lashkar.
In Gwalior, Morena, and Bhind, recovery agents frequently resort to coercive tactics, visiting workplaces, contacting relatives, and threatening police summons. Personal loan settlement advocates in Gwalior establish an immediate legal shield under RBI directions, halting harassment and directing disputes into lawful One-Time Settlement conciliation.
NPA Delinquency Aging & MP High Court Bench Safeguards
Under the Reserve Bank of India's Prudential Norms (IRACP), overdue credit facilities transition through defined delinquency stages. During the initial ninety days, overdue loans are classified as Special Mention Accounts (SMA-0 to SMA-2), triggering reminder alerts and penal levies. Once an account exceeds ninety days of continuous non-payment, it is classified as a Non-Performing Asset (NPA), obligating the bank to lock mandatory capital reserves against the unpaid balance.
| Asset Classification | Aging Duration | Mandatory Provisioning | Recovery Strategy & OTS Scope |
|---|---|---|---|
| SMA-0 & SMA-1 | 1 – 60 Days Overdue | Standard Capital Buffer (0.40%) | Automated tele-calling and late fees; formal OTS write-offs are not permitted. |
| SMA-2 | 61 – 90 Days Overdue | Pre-NPA Watchlist Reserve | Lenders issue pre-NPA demand notices; borrowers may apply for loan restructuring. |
| Substandard NPA | 91 – 365 Days Overdue | 15% Secured / 25% Unsecured | File transferred to Zonal SARB in City Centre; opening window for 35% to 50% waivers. |
| Doubtful (D1 / D2) | 1 – 3 Years Overdue | 40% – 100% Capital Lock | Substantial provisioning motivates banks; advocate negotiations secure 50% to 65% haircuts. |
| Loss Asset | 3+ Years Overdue | 100% Full Balance Write-Off | Account fully provisioned; optimal framework for Lok Adalat settlement up to 70% waiver. |
The permanent bench of the High Court of Madhya Pradesh at Gwalior exercises jurisdiction over Gwalior, Morena, and Bhind. Following the Supreme Court benchmark in ICICI Bank Ltd. v. Shanti Devi Sharma, the MP High Court prohibits lenders from deploying recovery musclemen or coercive pressure. Under Article 226 of the Constitution, borrowers facing unlawful harassment can petition the High Court for injunctive relief and enforce due process.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Defending Statutory Legal Notices in Gwalior & Chambal CJM Courts
When loan default persists, lenders initiate proceedings under Section 138 of the Negotiable Instruments Act, 1881 for bounced cheques, or Section 25 of the Payment and Settlement Systems Act, 2007 (PSSA) for failed NACH debits. Creditors file complaints before Chief Judicial Magistrate (CJM) Courts in Gwalior (Morar / City Centre), Morena, and Bhind.
Borrowers receive a mandatory fifteen-day window to reply to legal notices. Ignoring summons can prompt courts to issue bailable warrants. Personal loan settlement advocates in Gwalior submit structured legal replies establishing financial hardship, disputing penalty fees, and refuting criminal intent. This legal response shifts the dispute into conciliation, facilitating an amicable referral to the DLSA National Lok Adalat.
Banker's Lien & Salary Account Shielding in Gwalior
Under Section 171 of the Indian Contract Act, 1872, a bank holds a general lien only over accounts within its own institution. A creditor bank cannot freeze or debit deposits in separate, external banks without an explicit court order. Furthermore, Section 60(1) of the Code of Civil Procedure (CPC), 1908 strictly exempts government salaries, basic living allowances, and pensions from judicial attachment.
To protect household funds, borrowers across Gwalior, Morena, and Bhind must transition salary credits and liquidity to an unlinked bank. Borrowers should also cancel active NACH and e-mandates under NPCI guidelines, eliminating sweeps and recurring bounce charges.
Personal Loan Settlement Roadmap in Gwalior, Morena & Bhind
The visual roadmap below details the five-step legal debt resolution framework across Gwalior and the Chambal division, illustrating the transition from hardship notice defense to bank Zonal SARB negotiations and binding Lok Adalat compromise awards.
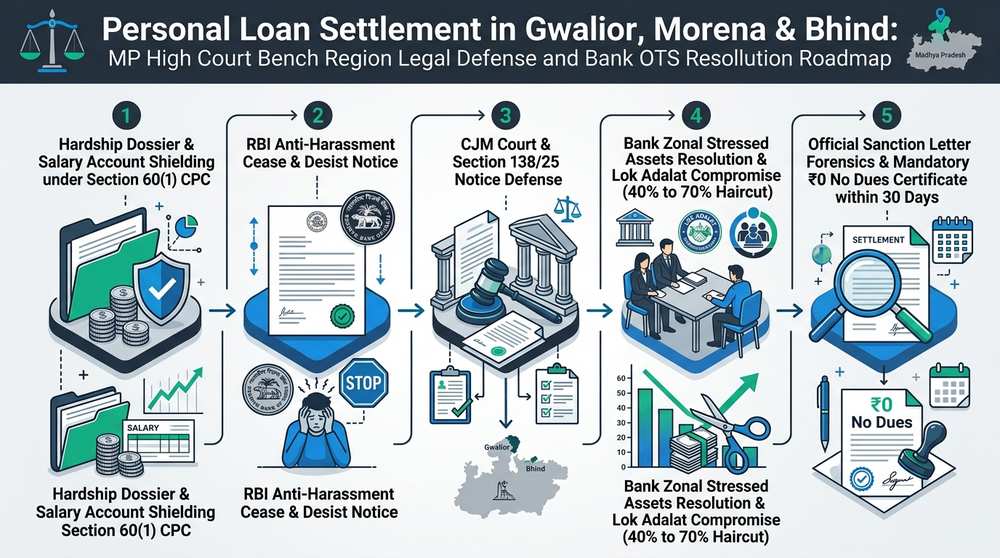
Figure 1.0: Comprehensive Gwalior & Chambal Debt Settlement Protocol, CJM Notice Defense & Bank OTS Roadmap.
OTS Haircut Mechanics & Institutional Valuation Formula
Bank compromise decisions depend on financial recovery mathematics. When evaluating One-Time Settlement offers, bank Zonal Settlement Committees in City Centre, Gwalior utilize a standardized Net Present Value (NPV) recovery valuation model. Because unsecured personal loans carry no collateral, pursuing civil court litigation requires upfront fees, legal costs, and years of process.
Where C_t represents estimated recoveries, r is the discount rate, and deductions account for 3–5 years of court friction and capital locked in NPA provisions.
When a borrower presents an upfront lump-sum offer through legal counsel, the bank releases provisioned capital and eliminates legal overhead. Because protracted litigation yields lower net recovery, bank credit committees routinely approve 40% to 70% principal waivers and write off 100% of accumulated penal charges.
Enforcing RBI Anti-Harassment Directives & Police Limits
The RBI's Master Direction on Recovery Agents (2022) establishes strict operational boundaries for lenders. Calls are permitted only between 8:00 AM and 7:00 PM. Agents cannot call outside these hours, use intimidating language, contact relatives, or visit workplaces without consent.
Under Supreme Court rulings in Arnesh Kumar and Lalita Kumari, police authorities cannot intervene in civil loan defaults. Police stations across Gwalior—including Morar, Inderganj, Padav, Thatipur, and Madhav Ganj—as well as stations in Morena and Bhind, cannot summon borrowers or register FIRs for debt non-payment.
When agents violate statutory directives, our advocates issue Cease-and-Desist notices to the bank Principal Nodal Officer and file grievances on the RBI Integrated Ombudsman Portal (CMS), compelling lenders to halt harassment and negotiate lawfully.
5-Step Legal Settlement Protocol in Gwalior & Chambal
Achieving a binding debt compromise across Gwalior, Morena, and Bhind follows an advocate-led protocol across five strategic stages:
Financial Hardship Dossier Compilation
We compile verified hardship records—including salary slips, medical bills, trade ledgers, and tax returns—proving bona fide inability to service original loan terms.
Cease-and-Desist Anti-Harassment Notice
Our advocates serve statutory notices on the bank Principal Nodal Officer and Zonal Heads in City Centre, halting recovery calls and prohibiting workplace or home visits.
CJM Court Legal Notice Defense
Counsel prepares and files comprehensive replies to Section 138 NI Act and Section 25 PSSA notices in CJM Courts, shielding borrowers from judicial warrants.
Direct Zonal SARB & Lok Adalat Conciliation
Bypassing collection agencies, our negotiators interface directly with bank Stressed Assets branches in City Centre and DLSA Lok Adalat benches to secure 40% to 70% waivers.
Sanction Letter Audit & Mandatory NDC Delivery
We audit the official bank sanction letter for legal accuracy prior to payment via RTGS, ensuring delivery of the zero-balance No Dues Certificate within thirty calendar days.
Sanction Letter Forensics & Mandatory ₹0 NDC Enforcement
Borrowers must never make settlement payments on verbal assurances. A valid OTS Sanction Letter must arrive on official bank letterhead, displaying emblems, officer codes, waiver terms, and payment schedules remitted solely to the loan account. Counsel audits every sanction letter before advising clients to remit funds via RTGS.
Under RBI Circular RBI/2023-24/60, lenders must deliver a zero-balance No Dues Certificate within thirty calendar days of settlement completion. If the bank fails to issue the certificate within this timeframe, it must pay ₹5,000 per day of delay to the borrower.
Post-settlement, credit bureaus record the account as 'Settled' with zero balance. While credit scores drop initially, borrowers in Gwalior can rebuild their CIBIL score back above 750 within eighteen to twenty-four months through disciplined financial habits and secured credit facilities.
Comparative Debt Resolution Pathways for Gwalior Borrowers
Compare the principal debt resolution avenues across Gwalior, Morena, and Bhind to evaluate which legal strategy best protects your financial recovery:
| Resolution Pathway | Principal Haircut Range | Legal Binding Finality | CIBIL Bureau Status | Resolution Timeline |
|---|---|---|---|---|
| Direct Zonal SARB Settlement (Gwalior) | 40% – 70% Principal Haircut | Complete (Official Bank NDC Issued) | 'Settled' / ₹0 Outstanding Dues | 3 to 6 Weeks |
| DLSA Lok Adalat (Gwalior, Morena & Bhind) | 45% – 70% Principal Haircut | Absolute (Civil Court Decree, Non-Appealable) | 'Settled' / ₹0 Outstanding Dues | Quarterly Lok Adalat Cycles |
| Institutional Loan Restructuring | 0% Haircut (Tenure Extension Only) | Conditional on Monthly Service | 'Restructured' / Active Debt Liability | 2 to 4 Weeks |
| Contested Court Litigation (CJM / HC) | Uncertain (Judicial Determination) | Subject to Protracted Appeals | 'Suit Filed' / Compounding Arrears | 4 to 7 Years |
Premier Loan Settlement & Legal Defense Services in Gwalior
Overcoming debt distress across Gwalior, Morena, and Bhind requires dedicated advocate representation. Our legal team halts recovery harassment, defends CJM notices, and negotiates directly with bank committees to secure maximum debt waivers and legal closure.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
Frequently Asked Questions on Personal Loan Settlement in Gwalior
Why do salaried employees and traders in Gwalior need specialized debt settlement advocates?
Borrowers across Gwalior, Morena, and Bhind frequently face aggressive recovery agencies and coercive legal notices. Dedicated advocates invoke RBI Fair Practices Codes, halt harassment at home or workplace, shield salary accounts under Section 60(1) CPC, and negotiate 40% to 70% OTS waivers directly with bank Zonal Stressed Assets desks in City Centre.
Can the MP High Court Bench at Gwalior intervene against aggressive NBFC recovery tactics?
Yes. Under Article 226 of the Constitution of India, the High Court of Madhya Pradesh Bench at Gwalior exercises jurisdiction over Gwalior and the Chambal division. The High Court enforces the Supreme Court mandate in ICICI Bank v. Shanti Devi Sharma, prohibiting recovery musclemen and granting injunctive relief against extra-judicial coercion.
Can a bank freeze or attach my salary account for personal loan default in Gwalior?
Under Section 171 of the Indian Contract Act, 1872, a bank general lien applies strictly to accounts within its own institution. An external bank account cannot be frozen without a civil court order. Furthermore, Section 60(1) of the Code of Civil Procedure, 1908 exempts government and private salaries, basic wages, and pensions from judicial attachment.
Can Gwalior, Morena, or Bhind police register an FIR or arrest me for unpaid personal loans?
No. Unsecured loan default is purely a civil breach of contract under the Indian Contract Act, 1872. Following Supreme Court directives in Arnesh Kumar and Lalita Kumari, police stations in Morar, Inderganj, Padav, Thatipur, or Maharaj Bada have no legal authority to intervene, summon borrowers, or file FIRs for non-payment.
How should borrowers respond to Section 138 NI Act or Section 25 PSSA court notices in Gwalior?
Borrowers must file a structured legal reply through counsel within the statutory fifteen-day window. Our advocates establish bona fide financial hardship, challenge inflated compound penalties, and propose conciliation. This timely defense prevents issuance of bailable warrants and directs the dispute to the DLSA National Lok Adalat.
How does DLSA Gwalior Lok Adalat resolve delinquent personal loans?
The District Legal Services Authority (DLSA) Gwalior organizes quarterly National Lok Adalats at the District Court campus in Morar / City Centre. Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat compromise decree is conclusive, non-appealable, and formalizes 40% to 70% principal waivers with complete legal immunity.
Are borrowers in Morena and Bhind eligible for Gwalior advocate representation and bank OTS?
Yes. Lenders operating in Morena and Bhind process stressed debt files through regional and zonal recovery committees seated in Gwalior. Our legal team provides unified representation across CJM Courts in Morena, Bhind, and Gwalior, securing formal bank sanction letters and binding Lok Adalat compromise awards.
What percentage of debt waiver can borrowers in Gwalior realistically negotiate?
Depending on default aging beyond 90 to 180 days and verified documentation of insolvency, our advocates routinely secure 40% to 70% principal waivers on unsecured personal loans and credit cards. Additionally, we negotiate a 100% waiver of accumulated penal interest, late fees, and legal charges.
What is the legal timeline for banks to issue a No Dues Certificate post-settlement?
Under RBI Circular RBI/2023-24/60, lenders must issue an authentic zero-balance No Dues Certificate and update credit bureaus within thirty calendar days of settlement payment. If the lender delays beyond thirty days, it is legally obligated to compensate the borrower ₹5,000 per day of delay.