- Gauhati High Court Civil Precedents. Loan default is a civil dispute. Police and banks cannot make criminal arrests for unpaid debt.
- Direct PSU SARB Talks. Defaulted SBI, UCO, and PNB loans move to SARB branches. Bank OTS policies offer 40% to 70% waivers.
- Kamrup Metro CJM Court Defense. Advocates handle Section 138/25 notices in Panbazar. They secure bail and resolve debt in Lok Adalats.
- Assam Microfinance Legal Shield. State laws and RBI rules ban abusive recovery calls and doorstep harassment.
- RBI No Dues Certificate in 30 Days. Final settlement grants a ₹0 NDC within 30 days and updates credit bureaus to ₹0 balance.
1. Guwahati Debt Landscape & Realities
Guwahati is the main trade and office hub of North-East India. Major markets operate in Fancy Bazar, Panbazar, Paltan Bazar, and GS Road. The city also houses government and office hubs in Dispur, Christian Basti, Bhangagarh, and Six Mile. These hubs employ thousands of salaried staff, executives. And doctors.
Recent business slowdowns, cash flow crunches. And rising living costs have hurt borrowers in Kamrup Metro. When EMIs remain unpaid for 90 days, banks tag loans as NPAs. Borrowers then face harsh calls and home visits across Zoo Road, Beltola, and Kahilipara.
Working with a skilled debt settlement team in Guwahati brings peace of mind. Our advocates stop agent harassment and audit loan contracts. We negotiate directly with bank committees to secure 40% to 70% OTS waivers.
2. Statutory Protections for Assam Borrowers
Debt resolution in Assam follows central laws, RBI rules, and Gauhati High Court orders. Under Section 73 of the Indian Contract Act, 1872, loans are civil agreements. Default due to distress or medical trouble is a civil matter. The Gauhati High Court has ruled that police cannot file FIRs or step into civil loan disputes.
Under Article 226 of the Constitution of India, the High Court bans harsh recovery acts that harm personal dignity under Article 21.
This state law stops lenders from using abusive recovery agents, threats, or unfair interest compounding.
For employees in Dispur and Guwahati, Section 60(1)(i) CPC exempts basic pay and two-thirds of salary from court attachment.
RBI rules ban collection calls outside 8:00 AM to 7:00 PM, family harassment, abusive words. And uninvited visits.
Under Section 13(2) of the SARFAESI Act, 2002, asset seizure applies only to secured mortgage loans. For personal loans and credit cards, banks cannot seize property or seal homes without a civil court trial.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. PSU Bank SARB Mechanics in Guwahati
Guwahati hosts large PSU bank hubs. These include State Bank of India (LHO and SARB at Dispur), UCO Bank (Panbazar), and Punjab National Bank (GS Road). It also hosts Canara Bank, AGVB, HDFC, ICICI, and NBFCs like Bajaj Finance.
When an unsecured loan crosses 90 to 180 days unpaid, banks move files to Stressed Assets Recovery Branches (SARB). Branch managers have limited powers. In contrast, SARB committees use board-approved OTS policies to settle bad debt.
When advocates submit verified hardship records, SARB teams can approve major waivers. They waive 100% of penal interest and reduce principal by 40% to 70% for full closure.
4. Bank Economics & The Stressed Asset NPV Recovery Equation
Under RBI IRAC norms, defaulted loans require mandatory NPA provisions. These range from 15% to 100%. Locked capital hurts bank profits. This encourages lenders to approve settlement offers.
| Distressed Debt Category. | Original Claim. | Bank Provisioning. | Target OTS Compromise. |
|---|---|---|---|
| Salaried Personal Loan (PSU Bank). | ₹12.0 Lakhs. | 100% Loss Provisioned. | Target OTS. ₹4.5L to ₹5.5L (54%–62% Haircut). |
| Fancy Bazar MSME Credit Facility. | ₹25.0 Lakhs. | 100% Capital Locked. | Target OTS. ₹8.0L to ₹10.5L (58%–68% Haircut). |
| Private Bank Credit Card Pool. | ₹6.5 Lakhs. | 100% Written Off in P&L. | Target OTS. ₹1.8L to ₹2.5L (61%–72% Haircut). |
| Digital Fintech App Loan Pool. | ₹4.0 Lakhs. | 100% Capital Impairment. | Target OTS. ₹1.2L to ₹1.6L (60%–70% Haircut). |
When reviewing an OTS proposal, bank committees use the Net Present Value (NPV) recovery formula:
Here C_t is estimated recovery. The letter r is the discount rate. Deductions cover court fees and locked capital funds.
Long court trials in Kamrup Metro bring high fees and slow returns. An upfront cash settlement yields much better value for the lender.
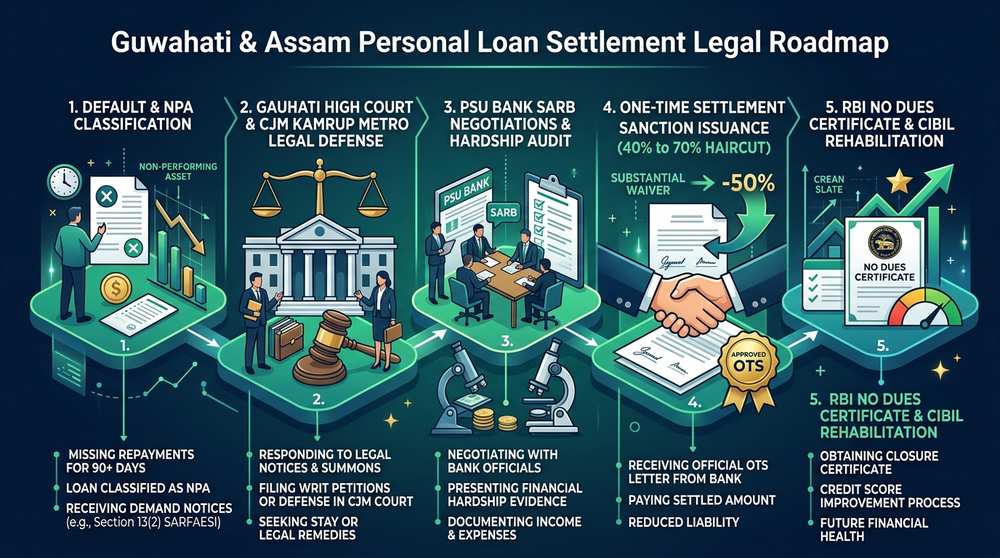
5. Guwahati & Assam Loan Settlement Legal Roadmap
The chart below shows the 5-step legal journey from loan default to SARB talks, OTS sanction. And full credit recovery.
6. Legal Defense: Countering Kamrup Metro Summons
When NACH debits or cheques bounce, banks file cases under Section 138 NI Act or Section 25 PSSA. These cases go to the Panbazar CJM Court.
Our advocates protect borrowers through a four-tier defense plan:
Tier 1: Notice of Legal Representation
Advocates serve legal notices citing RBI rules. This routes all bank calls through counsel.
Tier 2: Representation in Kamrup Metro Courts
Counsel files a Vakalatnama at Panbazar Court. They secure bail and contest notice defects.
Tier 3: Verified Hardship Dossier Submission
Lawyers present proof of income loss, business decline, or illness to bank committees.
Tier 4: National Lok Adalat Consent Decree
Under Section 147 NI Act, we take the dispute to ASLSA Lok Adalat for final disposal.
7. Forensic Audit of Settlement Letters in Assam
Avoid fake settlement letters from agents. Every genuine OTS sanction letter must meet four key checkpoints:
Must be on official bank letterhead with authorized officer signatures and seal.
Must state loan number, PAN, exact settlement sum. And payment dates.
Must confirm that full payment closes all balance, interest. And fees.
Must state that the bank will withdraw all court cases within 30 days.
Never pay cash or send funds to personal UPI IDs. Pay directly into your loan account via RTGS, NEFT, or Demand Draft.
8. Settlement Remittance & ₹0 NDC in Assam
Under RBI Circular RBI/2023-24/60, banks must issue the No Dues Certificate (NDC) in 30 days. Lenders must pay ₹5,000 per day of delay if they fail to issue it on time.
Banks must return all pledged documents and deliver closure letters in 30 days.
Credit Bureau Rehabilitation Overview
After settlement, banks update credit bureaus to "Settled" with a ₹0 balance. This stops negative marks. You can restore your score to 750+ within 18 to 24 months.
9. Guwahati Banking Settlement vs. Court Litigation Matrix
Comparing bank OTS and court trials shows why settlement is the smarter choice:
| Resolution Parameter. | Advocate-Negotiated Bank OTS. | Contested Court Litigation (Panbazar Courts). |
|---|---|---|
| Financial Liability. | Huge Savings. 40%–70% Principal Waiver. 100% Penal Waiver. | Full Cost. Full Claim + 18%–24% Interest + Court Fees. |
| Resolution Time. | Fast. 45 to 120 Days for Full Closure. | Slow. 3 to 7 Years of Protracted Trials. |
| Harassment Protection. | Protected. Complete Safety via Legal Notice. | Exposed. Summons, Calls, and Court Friction. |
| Legal Finality. | Final. Bank NDC and Lok Adalat Order. | Uncertain. Warrants and Salary Attachment Risk. |
| CIBIL Status. | Rebuilt. ₹0 Balance. Rebuild in 18–24 Months. | Damaged. Long Default Record. |
10. SettleLoans Legal Defense & Advisory in Guwahati
SettleLoans provides expert debt defense in Guwahati and Assam. We stop agent harassment and defend court cases in Kamrup Metro. We negotiate with bank SARBs to secure 40% to 70% OTS debt waivers with formal No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Guwahati
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Guwahati can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Panbazar, MG Road, Guwahati, Assam - 781001
Jurisdiction: Primary trial court for loan default litigation across Kamrup Metro and Guwahati, with appellate jurisdiction resting with Gauhati High Court.
Address: ADR Centre, Panbazar Court Campus, Guwahati - 781001
Lok Adalat Conciliation: Offers pre-litigation dispute resolution for commercial loans and personal debt under Assam State Legal Services Authority mandates.
11. FAQs: Guwahati Assam
Find clear legal answers about loan defaults, recovery rules, court notices, and OTS steps in Guwahati and Assam.
Why do borrowers in Guwahati and Assam require specialized loan settlement advocates?
Guwahati is the financial hub of North-East India. It hosts Zonal Offices and SARB branches for SBI, UCO Bank, and PNB. Loan settlement requires local legal knowledge of Gauhati High Court and Kamrup Metro Court. Advocates stop agent harassment and negotiate 40% to 70% OTS waivers.
Can Guwahati Police or Assam Police arrest me for defaulting on an unsecured personal loan?
No. Loan default is a civil breach of contract under the Indian Contract Act, 1872. The Gauhati High Court has affirmed this. Police have no legal authority to file FIRs or arrest debtors for genuine loan defaults.
How does SettleLoans handle recovery agent harassment in residential areas of Guwahati?
We send a formal Notice of Representation under RBI rules and the Assam Micro Finance Institutions Act, 2020. This directs all bank talks through legal counsel. It bans doorstep visits, abusive calls. And third-party contact.
What legal steps are taken if I receive a Section 138 NI Act notice from Kamrup Metro Court?
Empanelled Guwahati advocates send a formal legal reply challenging illegal interest and fines. If a case is filed in Panbazar CJM Court, our counsel appears under a Vakalatnama. They secure bail and move the matter to National Lok Adalat for OTS.
How does SBI SARB Guwahati process One-Time Settlements for unsecured personal loans?
When an unsecured loan crosses 90 to 180 days overdue, SBI shifts the file to SARB Guwahati. SARB committees hold board powers to grant 40% to 70% waivers. Approvals depend on verified financial distress and asset status.
Can a bank freeze or attach my salary account in Assam for personal loan non-payment?
Banks cannot freeze salary accounts without a Civil Court order under Order XXI CPC. also, Section 60(1)(i) CPC protects basic allowances and two-thirds of salary from court execution.
What essential clauses must be verified in a Guwahati bank OTS sanction letter?
A valid OTS letter must be on official bank letterhead with an authorized manager's signature. It must state the loan account number, exact settlement sum, payment dates, full debt discharge, and 30-day NDC delivery.
How does personal loan settlement in Assam affect credit bureau reporting across CIBIL and CRIF?
Once you pay the settlement, the bank updates CIBIL, Experian, and CRIF to 'Settled' with a ₹0 balance. This stops monthly negative reporting. You can rebuild your credit score above 750 within 18 to 24 months.
How long does the personal loan settlement process take in Guwahati?
The settlement process usually takes 45 to 120 days. This covers liability audit, legal notices, hardship filing, SARB talks. And final sanction issuance.
Are microfinance loans and fintech app debts covered under debt settlement protections in Assam?
Yes. The Assam Micro Finance Institutions Act, 2020, and RBI Digital Lending Guidelines protect borrowers. They ban harsh recovery tactics and hidden fees, giving strong grounds for an OTS compromise.