- Zero Collateral Risk: Unsecured loans carry no claim on factory machinery or homes.
- Workplace Legal Shield: RBI rules ban agent visits to factories and offices.
- Court Notice Defense: Legal replies convert Section 138 and Section 25 notices into settlements.
- 40% to 60% Haircuts: Banks write off debt to avoid long court suits.
- Mandatory ₹0 NDC: Banks must deliver closure letters within 30 days under RBI rules.
The Economic Reality of Debt in Coimbatore, Tirupur & Salem
Coimbatore is a key industrial hub in Tamil Nadu. It links Tirupur textile mills and Salem factories. Many residents run foundries or work in textile units. Others work in IT along Avinashi Road.
Yarn price swings and slow client payments cause cash stress. Borrowers often struggle to pay monthly EMIs. Debts can quickly pile up across multiple banks.
Hiring a debt settlement lawyer gives you a legal shield. You do not have to face agent harassment. We use RBI rules to win 40% to 60% waivers from bank committees.
Unsecured vs Secured Debt in Coimbatore
Secured loans fall under the SARFAESI Act, 2002. Lenders can auction mortgaged assets. In contrast, unsecured loans carry no claim on machines or homes. Lenders cannot seize assets without a court trial.
| Debt Type. | Security. | Governing Law. | Lender Power. | Settlement Range. |
|---|---|---|---|---|
| Personal Loans. | None (No asset pledged). | Indian Contract Act, 1872 &. CPC, 1908. | Low (Needs civil court suit). | 40% – 60% Principal Waiver |
| Credit Card Debt. | None (Unsecured line). | Indian Contract Act, 1872 &. RBI rules. | Low (Civil suit only). | 50% – 70% Total Waiver |
| MSME Business Loans. | None (Clean business line). | RBI Compromise Framework &. MSME Act. | Low (Civil suit only). | 40% – 55% Principal Waiver |
| Secured LAP / Mortgage. | Factory sheds, commercial or home property. | SARFAESI Act, 2002 (Sec 13(2), Sec 13(4)). | High (Asset auction). | 15% – 25% (Needs asset sale). |
Under Section 60(1)(c) CPC, livelihood tools cannot be seized in court cases. This protects workshop tools and textile looms across Western Tamil Nadu.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Halting Recovery Harassment in Coimbatore
Recovery agents often use harsh methods. They may visit factories in Peelamedu or Kurichi. Such actions violate RBI rules and court orders:
- Workplace Visits Prohibited: Agents cannot enter factories or offices without prior consent.
- Zero Third-Party Contact: Calling relatives or coworkers about your debt is illegal.
- Strict Calling Hours: Agents can call only between 08:00 AM and 07:00 PM.
- Mandatory Certification: Agents must carry bank ID cards and IIBF certificates.
Our lawyers send formal cease-and-desist notices to bank Nodal Officers. This stops workplace visits immediately.
Defending Sec 138 & 25 PSSA in Coimbatore
Banks send notices when cheques or auto-debits bounce. They cite Section 138 NI Act or Section 25 PSSA. Our advocates file replies proving genuine hardship. We guide disputes toward out-of-court settlements.
If a bank starts arbitration in distant cities, we challenge it. Under Section 12 of the Arbitration Act, we cite the Perkins Eastman ruling. We bring disputes back to local Lok Adalats or bank desks.
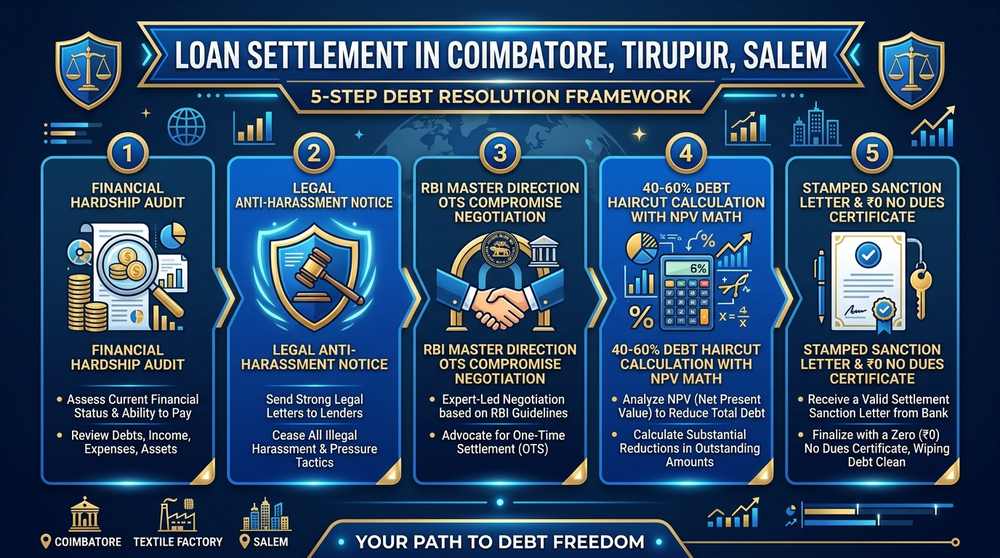
5-Step Loan Settlement & Debt Compromise Framework
NPV Valuation & Bank Math in Coimbatore
Under the RBI Compromise Framework (2023), banks evaluate offers using Net Present Value (NPV). When a loan passes 90 days overdue, Ind AS 109 forces banks to set aside cash reserves.
Here, C_t is estimated recovery and r is discount rate. Deductions cover court fees and blocked capital.
Civil suits in Coimbatore take 3 to 6 years. They also create high legal costs. A fast cash settlement of 40% to 55% gives the bank higher Net Present Value than long litigation.
Step-by-Step OTS Protocol in Coimbatore
Settling an unsecured loan follows five clear stages:
1Hardship Dossier Compilation
We gather financial records, GST returns. And loss accounts. These prove genuine business hardship.
2e-NACH Revocation & Legal Shield Activation
We stop NACH auto-debits under NPCI rules to stop bounce fees. We also send formal legal notices to lenders.
3Submitting Settlement Proposal to Stressed Asset Desks
We submit settlement files directly to Zonal SARB desks.
4Principal Haircut Negotiation & 100% Fee Waiver
We waive 100% of penal fees under RBI fair lending codes. We negotiate a 40% to 60% principal cut.
5Sanction Letter Forensic Audit & ₹0 NDC Delivery
We check the bank's stamped sanction letter before payment. We ensure NDC delivery within 30 days.
Sanction Letter Audit & NDC in Coimbatore
Some recovery agents issue fake settlement letters to take cash. SettleLoans audits every sanction letter. We confirm official bank letterheads, authorized signatures. And complete waiver clauses.
Under RBI Circular RBI/2023-24/60, lenders must issue the No Dues Certificate within 30 days. If they delay, they must pay ₹5,000 per day to the borrower.
CIBIL Rehabilitation in Coimbatore
After settlement, the bank marks the account as 'Settled&apos. with ₹0 dues across CIBIL, Experian, and CRIF. This stops interest adding and ends legal risks.
You can rebuild your CIBIL score to 750+ within 18 to 24 months. Use an FD-backed credit card, keep credit use under 30%. And pay balances on time.
Debt Resolution Matrix in Coimbatore
Compare legal options for resolving overdue loans in Coimbatore:
| Resolution Route. | Legal Tool. | Waiver Range. | Impact. | Legal Status. |
|---|---|---|---|---|
| Advocate-Led Bank OTS. | settlement under RBI rules. | 40% – 60% Principal Waiver | Zero (Handled by lawyers). | Binding settlement with ₹0 NDC. |
| National Lok Adalat. | Judicial settlement before judge panel. | 45% – 60% Debt Haircut | Minimal (Single hearing). | Civil Court Decree (Final order). |
| Arbitration Defense. | Challenge to one-sided arbitrator. | Converts to OTS. | Low (Handled via legal replies). | Court stay or transfer. |
| Sec 138 / 25 PSSA Defense. | Magistrate Court defense on bounced auto-debits. | 35% – 50% Debt Haircut | Low (Advocate appearance). | Legal compoundable settlement. |
Why Borrowers in Coimbatore & Kongu Region Trust SettleLoans
SettleLoans gives you legal debt resolution across Coimbatore, Tirupur, and Salem. We stop agent harassment. We defend court summons. We protect assets under CPC Section 60(1)(c). We negotiate 40% to 60% debt waivers under RBI rules.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Coimbatore
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Coimbatore can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Gopalapuram, Arts College Road, Coimbatore, Tamil Nadu - 641018
Jurisdiction: Major trial center for Section 138 NI Act prosecutions and commercial debt recovery suits impacting textile and pump industrial units.
Address: ADR Building, Combined Court Campus, Gopalapuram, Coimbatore - 641018
Lok Adalat Conciliation: Provides effective legal aid conciliation for unsecured personal debt and credit card defaults, securing finality without court penalties.
FAQs: Coimbatore & Tamil Nadu
How does personal loan settlement work in Coimbatore and Western Tamil Nadu?
Personal loan settlement is a legal compromise under RBI rules. Distressed borrowers submit hardship files to bank SARB units. Banks waive penal fees. They approve a 40% to 60% lump-sum payment. Borrowers then receive a formal sanction letter and NDC.
Can recovery agents visit my textile unit, factory, or office in Coimbatore?
No. RBI rules and court rulings ban workplace visits. Recovery agents cannot enter factories or offices. They cannot talk to coworkers. Our lawyers issue formal notices to halt agent visits.
What percentage of loan waiver can borrowers in Coimbatore expect during a One-Time Settlement (OTS)?
Borrowers can secure a 40% to 60% waiver on unsecured loans. Accounts must be overdue past 90 days. Banks also waive 100% of penal interest and late fees.
How does SettleLoans defend against Section 138 NI Act and Section 25 PSSA summons in Coimbatore courts?
Bounced cheques or auto-debits bring legal notices. Our lawyers file court replies in Coimbatore. We prove genuine hardship. We redirect cases to Lok Adalat for quick settlement.
Is loan settlement legally valid for MSME and textile business owners in Tirupur and Salem?
Yes. Unsecured MSME loans and overdrafts qualify. They fall under the RBI Compromise Framework. Owners settle debt without losing factory machines.
Why do banks in Coimbatore agree to write off 40% to 60% of an unsecured loan?
Ind AS 109 rules force banks to set aside cash for bad loans. Civil suits take up to 6 years. Upfront cash settlement gives banks faster value than long court trials.
What documents are required to initiate an advocate-led loan settlement in Coimbatore?
You need loan statements and income proofs. Businesses need GST returns and P&L sheets. You also need bank notice copies and signed authorization.
How long does a bank take to issue the No Dues Certificate (NDC) in Tamil Nadu?
Under RBI Circular RBI/2023-24/60, banks must issue NDCs within 30 days. Unjustified delays cost banks ₹5,000 per day in compensation.
How can I rebuild my CIBIL score after settling a loan in Coimbatore?
Settled loans show a ₹0 balance in credit bureaus. You can rebuild your score to 750+ within 24 months. Use secured credit cards and pay bills on time.
Official Statutory & Regulatory References
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Master Circular: Fair Practices Code for Lenders, Recovery Agent Conduct &. Penal Charge Caps
- Madras High Court: Judicial Precedents on Fair Debt Recovery, Prohibition of Third-Party Coercion &. Due Process
- Reserve Bank - Integrated Ombudsman Scheme: Grievance Redressal Mechanism for Unlawful Recovery harassment &. NDC Non-Delivery
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987. Pre-Litigation Lok Adalat settlement