- Civil Character of Default: Loan default is a civil contract dispute. Local police cannot summon debtors or register FIRs for unpaid bank debt.
- Statutory Salary Protection: Section 60(1) CPC and Section 171 Contract Act protect corporate salary accounts from unauthorized banker liens.
- Adalat Road Court Defense: Prompt replies to Section 138 NI Act and Section 25 PSSA notices halt criminal claims and move cases to Lok Adalat.
- Zonal SARB Waivers (40% to 70%): Direct talks with Jalna Road SARB desks yield 40% to 70% principal cuts and 100% penal interest write-offs.
- Mandatory NDC within 30 Days: Under RBI Circular RBI/2023-24/60, lenders must issue closure certificates within 30 days or pay ₹5,000 daily penalty.
Debt Landscape for Auto & Pharma Workers in Aurangabad
The Marathwada industrial corridor, centered in Chhatrapati Sambhajinagar (Aurangabad) and Jalna, is Maharashtra's manufacturing heartland. Key hubs across Waluj MIDC, Shendra AURIC, and Chikalthana host major auto-component suppliers like Bajaj Auto, Varroc, and Endurance, alongside pharma leaders Wockhardt, Ajanta Pharma, and Lupin. Eastward, Jalna drives steel re-rolling and wholesale agro-trading.
Automotive supply shifts, EV transitions, and inflation have triggered corporate slowdowns and shift reductions. To manage cash shortages, engineers and traders accessed multiple unsecured personal loans from private banks and fintech apps. Compounding interest and penalties rapidly pushed manageable debts into unserviceable delinquency.
Collection agencies operating from CIDCO and Kranti Chowk often deploy coercive tactics, calling workplace desks or visiting Waluj plants. Borrowers must know that involuntary loan default is strictly a civil dispute under Indian law, granting complete legal protection against harassment and unlawful recovery.
NPA Delinquency Aging & Bank Provisioning Norms
Under RBI Prudential Norms (IRACP), overdue accounts move through Special Mention Account stages (SMA-0 to SMA-2) in the first 90 days. After 90 days of missed payments, the bank marks the account as a Non-Performing Asset (NPA). The bank must then set aside capital reserves between 15% and 100% for the unpaid balance.
| Default Stage | Aging Threshold | Mandatory Provisioning | Institutional Strategy & OTS Scope |
|---|---|---|---|
| SMA-0 & SMA-1 | 1 – 60 Days Overdue | Standard Capital Reserve | Automated reminders and branch collection outreach. Debt restructuring possible; OTS waivers unavailable. |
| SMA-2 | 61 – 90 Days Overdue | Pre-NPA Heightened Reserve | Pre-default cure notices issued. Final opportunity to adjust tenure or negotiate loan moratorium. |
| Substandard NPA | 91 – 365 Days Overdue | 15% – 25% Profit Provision | File transferred to Zonal SARB desks. Formal OTS negotiations open with 35% to 50% principal waivers. |
| Doubtful (D1 / D2) | 1 – 3 Years Overdue | 40% – 100% Capital Lock | Bank initiates summary suits or Lok Adalat referrals. Viable 50% to 65% principal haircuts. |
| Loss Asset | Over 3 Years Overdue | 100% Written-off Balance | Full balance sheet write-off completed. Up to 70% principal waivers settled via National Lok Adalat. |
Mandatory capital provisioning locks 15% to 100% of the unpaid balance as bad debt reserves. To eliminate balance sheet drag, banks transfer overdue files to Stressed Assets Resolution Branches (SARB) on Jalna Road. These committees prioritize quick liquidity over multi-year litigation, opening prime opportunities for negotiated OTS waivers.
The Bombay High Court (Aurangabad Bench) strictly prohibits high-handed debt collection. Judicial rulings confirm that recovery must adhere to statutory due process and borrower dignity.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Defending Legal Notices in Adalat Road District Court
When personal loans default, lenders initiate action before the Judicial Magistrate First Class (JMFC) at the District Court Complex on Adalat Road. Creditors file cases under Section 138 of the Negotiable Instruments Act, 1881 for bounced cheques or Section 25 of the PSSA, 2007 for failed NACH debits.
The law requires creditors to serve a demand notice granting a 15-day statutory response window. Ignoring this notice allows banks to file criminal complaints leading to summons. A debt advocate examines the notice, disputes erroneous fees, and submits an authoritative legal reply within 15 days.
This formal reply proves the lack of criminal intent, establishes verifiable financial distress, prevents non-bailable warrants, and transitions the matter to the National Lok Adalat for an amicable compromise.
Banker's General Lien Rules & Salary Protection
Under Section 171 of the Indian Contract Act, 1872, banks hold a general lien allowing set-off only over accounts within their own branch network sharing identical CIF or PAN details.
Crucially, this lien cannot touch accounts at separate banking institutions without a civil court order. Furthermore, Section 60(1)(i) of the Code of Civil Procedure (CPC), 1908 protects two-thirds of disposable salary from civil attachment, preserving essential family living funds.
We advise clients to shift salary credits to unlinked institutions and formally revoke NACH mandates under RBI rules, insulating monthly income from arbitrary bank debits.
Personal Loan Settlement Roadmap in Aurangabad
The flowchart below illustrates the structured loan settlement process across Aurangabad, Jalna, and Marathwada, highlighting workplace privacy protection, Adalat Road court notice defense, Zonal SARB negotiations, and final No Dues Certificate issuance.
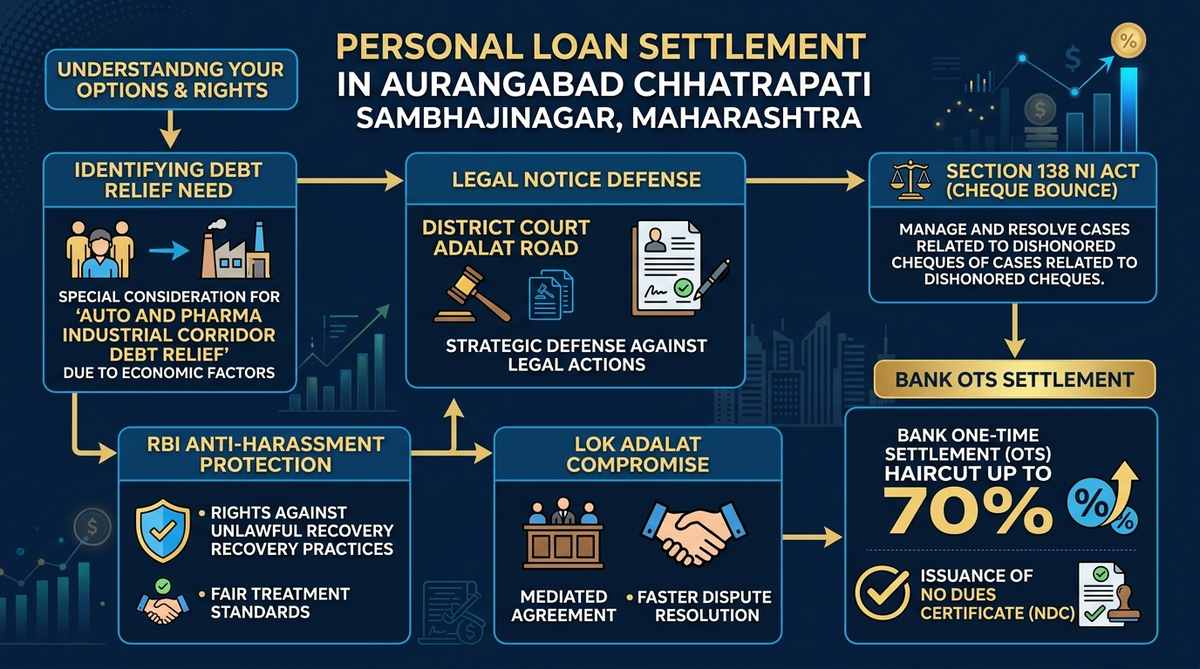
Figure 1.0: Comprehensive Aurangabad Loan Settlement Framework, Adalat Road Court Summons Defense, and Bank Zonal SARB Haircut Protocol.
OTS Haircut Mechanics & NPV Recovery Formula
Bank Settlement Committees on Jalna Road use a Net Present Value (NPV) formula to evaluate settlement proposals. Prolonged litigation in civil courts or DRT costs banks heavy advocate retainers, administrative time, and locked provisioning capital.
Where C_t is expected recovery, r is the discount rate, and deductions account for court costs and locked NPA funds over 4 to 7 years.
An immediate lump-sum settlement releases locked capital and eliminates court overhead. Consequently, bank credit committees approve 40% to 70% principal waivers alongside 100% penal interest write-offs.
Enforcing RBI Fair Practices & Police Limits in Waluj
Under the RBI Master Directions on Fair Practices Code, recovery agents must follow strict rules. Contact is restricted strictly between 08:00 and 19:00 hours. Intimidation, abusive calls, and contacting colleagues or family are strictly prohibited. Visiting industrial units in Waluj or Shendra without consent directly violates RBI mandates.
Under rulings in Arnesh Kumar v. State of Bihar, local police stations in MIDC Waluj, CIDCO, and Kranti Chowk cannot intervene in civil loan defaults. Officers cannot register FIRs or summon borrowers for civil non-payment.
When agents breach rules, our advocates issue Cease-and-Desist notices to bank Nodal Officers and lodge complaints on the RBI Ombudsman portal (CMS) to halt all unlawful recovery.
5-Step Zonal SARB Settlement Protocol in Aurangabad
Executing a legally protective loan settlement across Aurangabad and Jalna follows a structured 5-step roadmap:
Financial Hardship Dossier Compilation
We audit total liabilities and gather hardship evidence, including production cut notices, medical bills, or turnover loss, to substantiate genuine financial distress.
Legal Cease-and-Desist Notice & Workplace Privacy Shield
Our advocates serve formal notices on bank Zonal Heads, barring collection agent visits to Waluj and Shendra factories or family homes in CIDCO.
Statutory Notice Defense at Adalat Road District Court
We draft and submit replies to Section 138 NI Act and Section 25 PSSA notices in 15 days, preventing warrants and moving cases toward Lok Adalat.
Direct Negotiations with Zonal SARB Desks
Bypassing agencies, we negotiate directly with credit committees on Jalna Road, securing 40% to 70% principal cuts and 100% penal interest waivers.
Sanction Letter Audit & Mandatory NDC Delivery
We verify stamped OTS letters before direct RTGS remittance and ensure delivery of your ₹0 No Dues Certificate under RBI guidelines.
Sanction Letter Audit & Mandatory NDC in Aurangabad
Never remit funds based on verbal claims or WhatsApp messages from collection agents. A valid compromise requires an official OTS Sanction Letter on bank letterhead, bearing the manager's signature, seal, settlement sum, and closure covenants.
Under RBI Circular RBI/2023-24/60, lenders must issue an official No Dues Certificate (NDC) within 30 days of settlement payment. Any unjustified delay requires the lender to pay the borrower ₹5,000 per day in compensation.
Credit bureaus reflect the account as 'Settled' with ₹0 balance. This eliminates default reporting. Borrowers systematically restore scores above 750 within 18 to 24 months using secured credit cards and prompt utility payments.
Debt Resolution Pathways in Aurangabad & Marathwada
Comparing available debt resolution options helps borrowers in Aurangabad and Jalna make informed legal decisions:
| Resolution Pathway | Principal Haircut Range | Legal Binding Finality | CIBIL Bureau Status | Resolution Timeline |
|---|---|---|---|---|
| Direct Zonal SARB Settlement (Aurangabad) | 40% – 70% Principal Haircut | High Legal Finality via formal bank NDC | 'Settled' with ₹0 balance | 3 to 6 Weeks |
| DLSA National Lok Adalat (Adalat Road) | 45% – 70% Principal Haircut | Absolute Finality with status of Civil Court Decree | 'Settled' with ₹0 balance | Quarterly Sessions |
| Bank Loan Restructuring | 0% Principal Haircut (Tenure elongation) | Conditional on continued monthly EMI payments | 'Restructured' with active debt | 2 to 4 Weeks |
| Civil Court Litigation (Adalat Road) | Zero guaranteed haircut; subject to decree | Prolonged litigation risk with multiple appeals | 'Suit Filed' with compounding dues | 4 to 7 Years |
SettleLoans Legal Representation in Aurangabad
Resolving defaulted personal loans in Chhatrapati Sambhajinagar and Jalna requires professional legal representation and rigorous adherence to banking regulations. SettleLoans provides comprehensive legal defense for automotive engineers, pharmaceutical specialists, and commercial traders, ensuring complete protection from harassment and delivering substantial debt relief.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: Personal Loan Settlement in Aurangabad
Why do engineers in Waluj and traders in Aurangabad need specialized loan settlement lawyers?
Engineers in Waluj, pharma personnel in Chikalthana, and traders in Jalna face severe workplace reputation risks. Collection agencies exploit these fears with visits to factory gates. Specialized advocates enforce RBI regulations, defend Section 138 notices in Adalat Road courts, protect salary accounts under Section 60(1) CPC, and negotiate 40% to 70% OTS waivers with bank Zonal SARB desks.
Can private banks freeze or debit my salary account under Section 171 Banker's Lien in Aurangabad?
Under Section 171 of the Indian Contract Act, 1872, a commercial bank has a general lien only on accounts within its own branch network. A creditor bank cannot freeze or debit funds held in a different banking institution without an order from a competent civil court. Furthermore, Section 60(1)(i) CPC expressly shields two-thirds of disposable salary from court attachment.
Can recovery agents visit Waluj MIDC or Shendra industrial units or my home in CIDCO?
No. Under RBI Master Directions on Fair Practices Code, recovery agents are strictly prohibited from visiting a debtor's workplace or industrial unit without prior written consent. Permissible home visits in CIDCO or Garkheda are restricted between 08:00 and 19:00 hours, and agents must display official credentials. Violations can be escalated to the RBI Ombudsman.
What is the legal procedure when a bank serves a Section 138 NI Act or Section 25 PSSA notice from Adalat Road District Court?
Borrowers must file a formal legal reply through an advocate within 15 days of receiving a notice under Section 138 NI Act or Section 25 PSSA. The reply documents financial hardship, disputes arbitrary penalty computations, and denies criminal intent. Prompt response prevents magistrate arrest warrants and steers the case toward National Lok Adalat conciliation.
How does the National Lok Adalat under DLSA Chhatrapati Sambhajinagar resolve defaulted loans?
The DLSA Chhatrapati Sambhajinagar holds National Lok Adalats at Adalat Road District Court. Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat award functions as a final Civil Court decree. It is non-appealable, closes all pending court cases, and mandates the bank to issue a permanent zero-balance closure letter.
What percentage of debt waiver is legally achievable through a bank OTS in Aurangabad?
Depending on loan delinquency age, the bank's provisioning status, and documented financial distress (such as industrial layoffs, salary cuts, or business turnover loss), senior advocates negotiate 40% to 70% principal waivers. Additionally, lenders provide a 100% complete waiver of unapplied penal interest and late fees.
Can Aurangabad city police or MIDC Waluj police station arrest me or register an FIR for an unpaid personal loan?
No. Involuntary loan default is strictly a civil breach of contract under the Indian Contract Act, 1872. Local police stations, including MIDC Waluj, CIDCO, and Kranti Chowk, have no statutory authority to register FIRs or arrest borrowers for civil loan default. The Supreme Court in Arnesh Kumar v. State of Bihar confirmed that police cannot intervene in commercial debt disputes.
How does SettleLoans calculate and leverage the bank's Net Present Value (NPV) recovery formula?
Bank credit committees evaluate settlement proposals using the Net Present Value model: NPV = ∑ [ C_t / (1 + r)^t ] minus legal costs and capital locked in NPA provisions. Our advocates prove that protracted litigation over 4 to 7 years in local courts degrades recoverable value due to court fees and provisioning drag, making an immediate cash settlement mathematically advantageous for the lender.
What is the statutory timeline for receiving a No Dues Certificate (NDC) under RBI Circular RBI/2023-24/60?
Under RBI Circular RBI/2023-24/60, all commercial banks and NBFCs must issue an official No Dues Certificate within 30 days of receiving full settlement payment. Lenders failing to issue the certificate within 30 days without valid justification must pay the borrower statutory compensation of Rs 5,000 per day of delay.
How does a personal loan settlement impact CIBIL scores and what is the rehabilitation timeline?
The lending institution reports the settled loan to credit bureaus as 'Settled' with a zero balance. This stops ongoing overdue remarks, though it leads to an initial score drop of 75 to 150 points. Borrowers can rebuild their score above 750 in 18 to 24 months by utilizing secured credit cards and maintaining disciplined repayment records.