- Statutory Civil Decree: Under Section 21(1) LSA Act, 1987, a Lok Adalat award is a Civil Court decree. It has full legal force.
- Absolute Finality: Section 21(2) makes every award final. Banks cannot add fees or file appeals.
- Order 21 CPC Execution: If the bank delays your NDC, file an Execution Petition. The court can attach bank accounts.
- RBI ₹5,000 Daily Penalty: Under RBI Circular RBI/2023-24/60, banks must return papers in 30 days. Delays mandate ₹5,000 daily fines.
- Mandatory CIBIL Update: Lenders must update credit records to 'Settled&apos. with a ₹0 balance within 30 days under CICRA rules.
1. The Post-Settlement Breach Crisis
Lok Adalats resolve loan disputes quickly in India. Borrowers and banks sign a settlement before a judge. The bench passes a binding Lok Adalat Award. The borrower pays the agreed sum on time. In return, the bank closes the loan. It must issue a No Dues Certificate (NDC) and return property papers.
Yet many borrowers face delays after paying. Bank branches often fail to issue the NDC. Core banking systems keep adding interest. Recovery agents call again. Credit bureaus like CIBIL still show the loan as overdue or written off.
This happens when branch staff fail to update central teams. They do not upload the judicial award. The system then treats the waived sum as bad debt. Callers claim the award was only temporary.
Lenders cannot alter or cancel a Lok Adalat award. The law gives your award the force of a civil decree. You can use court powers to force bank action and claim fines.
2. Statutory Supremacy
To enforce a settlement, you must know the Legal Services Authorities (LSA) Act, 1987. A Lok Adalat is not just a mediation panel. It is a statutory judicial body set up by Parliament.
Section 21 of the LSA Act, 1987 sets two core legal rules:
Section 21(1) states every Lok Adalat award is a Civil Court decree. Once signed, it holds full executable power like a regular court order.
Section 21(2) makes every award final and binding on all parties. No appeal lies in any court. This stops banks from reopening cases.
The Supreme Court has confirmed the power of Lok Adalat awards in key rulings:
- State of Punjab &. Anr. v. Jalour Singh &. Ors. (2008) 2 SCC 660: The Supreme Court ruled that awards are final. No appeal lies against them. They can only be challenged under Article 226/227 on proof of fraud.
- K.N. Govindan Kutty Menon v. C.D. Shaji (2012) 2 SCC 51: The Supreme Court held that cheque bounce cases settled in Lok Adalat become civil decrees executable under the CPC.
- P.T. Thomas v. Thomas Job (2005) 6 SCC 478: The court held that Lok Adalat awards have statutory finality and close all original claims.
When a bank manager delays compliance, the bank breaches a court decree. The court award replaces the old loan contract.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Civil Court Execution Proceedings
A Lok Adalat award is a civil decree. You can enforce it under Order 21 of the Code of Civil Procedure (CPC), 1908. Borrowers who pay on time have the right to file execution petitions against non-compliant banks.
When a bank withholds an NDC, your lawyer files an Execution Petition in Civil Court. Order 21 CPC provides strong tools:
Specific Performance of Mandatory Injunctions (Order 21 Rule 32 CPC)
If the bank refuses to issue an NDC, the court acts under Rule 32. It can attach bank assets or seize original property deeds.
Attachment of Bank Branch Operating Accounts (Order 21 Rule 43 & 46 CPC)
If a bank took extra money, the court issues a Garnishee Order. This freezes the bank branch's RBI account until the decree is paid.
Territorial Jurisdiction of the Executing Court
Under Sections 38 and 39 CPC, file the petition where the case started. Or file where the bank branch is located.
Filing an Execution Petition brings fast results. Banks do not want their accounts attached over simple closure delays.
4. Bank Accounting Realities in Lok Adalat Awards
Bank accounting rules show why settlements happen. Loans in Lok Adalat are Non-Performing Assets (NPAs) past 90 days. Under RBI rules, banks must set aside cash reserves:
| NPA Classification Category. | Overdue Aging Timeline. | Mandatory RBI Capital Provision. | Balance Sheet Impact Upon Lok Adalat Settlement. |
|---|---|---|---|
| Sub-Standard NPA. | 91 to 365 Days Overdue. | 15% Secured / 25% Unsecured. | Bank frees locked capital and adds it back to profits. |
| Doubtful Asset 1 (D1). | 1 to 2 Years as NPA. | 25% to 40% Secured / 100% Unsecured. | Bank recovers capital and clears bad debt. |
| Doubtful Asset 2 / Loss Asset. | 2+ Years or Declared Loss. | 100% Full Provision / Technical Write-off. | Every rupee collected counts directly as net profit. |
When you pay, the bank gains instant cash. It reverses bad debt reserves right away.
Banks use the Net Present Value (NPV) formula. They compare quick cash with slow court trials:
Here C_t is expected cash flow. Rate r is the bank's cost of capital. Deductions cover court fees, delays, locked funds, and RBI fines.
The bank has already booked its balance sheet gains. Withholding your NDC or harming your CIBIL score is illegal. Courts and the RBI treat this delay as a major failure.
5. Visual Judicial Roadmap
This roadmap shows how to enforce your Lok Adalat award. Follow these legal steps to get your NDC, fix CIBIL records. And claim RBI delay fines.
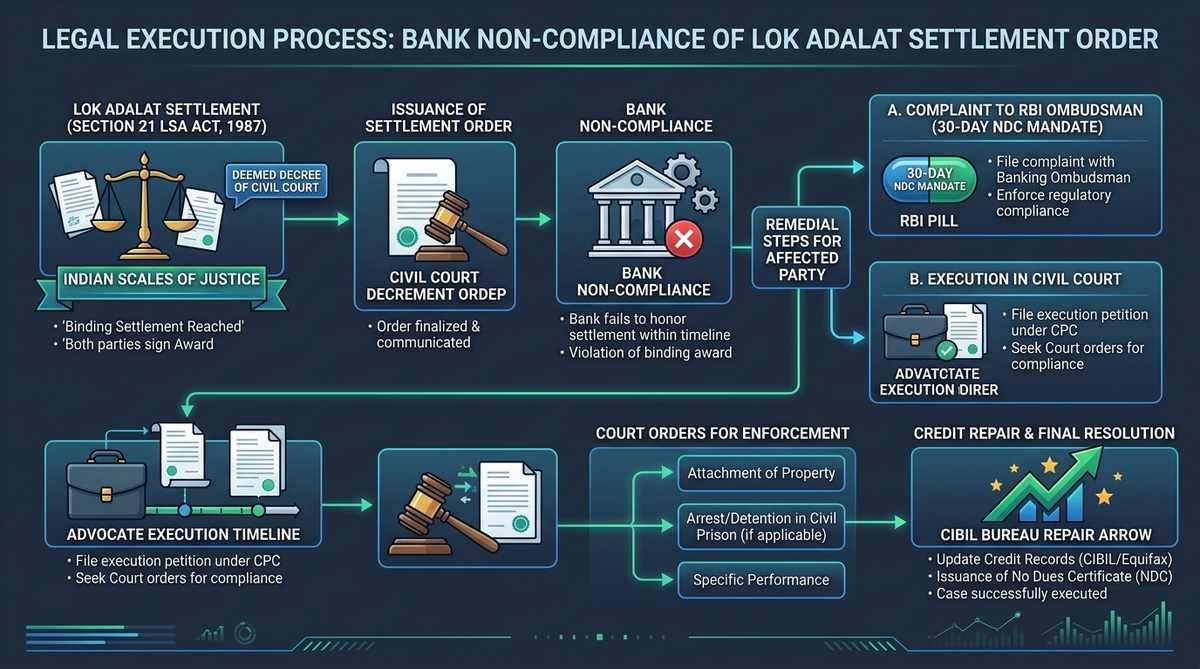
6. The 4-Stage Legal Protocol to Compel Immediate Bank
Visiting the branch rarely solves delays. Advocates use a 4-stage legal plan to force compliance:
Stage 1: Forensic Verification of Compliance & Certified Award Compilation
Gather your proof: certified Lok Adalat Award with court seals, payment receipts. And settlement letter.
Stage 2: Serving Advocate Legal Notice for Civil Decree Disobedience
Your lawyer sends a notice to the bank MD and Nodal Officer. It cites Section 21 LSA Act and gives 15 business days to act.
Stage 3: Escalation to the RBI Integrated Banking Ombudsman
If the bank ignores the notice, lodge a complaint on the RBI CMS portal (cms.rbi.org.in). The Ombudsman can order fast loan closure and damages.
Stage 4: Filing Execution Petition Under Order 21 CPC in Civil Court
Your counsel files an Execution Petition under Order 21 CPC. The Civil Court can attach bank branch accounts and order property return.
This legal plan forces senior bank officers to act without delay.
7. Resolving CIBIL Bureau Violations
Bank delays can hurt your credit score. Lenders often fail to update credit bureaus. CIBIL, Experian, and Equifax may still show overdue debt.
Under the Credit Information Companies (Regulation) Act (CICRA), 2005, lenders must update credit bureaus every 30 days:
The account status must change to "Settled" or "Post-Write-off Settled". This closes the trade-line and stops negative remarks.
The current balance and overdue amount must show ₹0. Showing overdue sums violates Section 21 of CICRA.
Lawyers file CIBIL disputes with the Lok Adalat award attached. Under CICRA Section 21, bureaus must fix records within 30 days. If the bank delays, the RBI Ombudsman awards payout.
8. Sanction Forensics, Mandated Timelines
You must know your legal timelines. The Reserve Bank of India sets strict rules against bank delays.
Under RBI Circular RBI/2023-24/60, all banks, NBFCs, and HFCs must:
- Release all original property documents within 30 calendar days of full settlement.
- Issue an official No Dues Certificate (NDC) confirming zero remaining liability.
- Pay payout of ₹5,000 per day of delay beyond 30 days directly to the borrower.
- Official Bank Letterhead &. Reference Number: Must have registered letterhead, official reference numbers. And branch contact details.
- Unambiguous Recital of Full Satisfaction: Must state the loan is closed under the Lok Adalat award with zero remaining dues.
- Authorized Signatory Seal: Must carry the seal and signature of an authorized bank manager with employee code.
- Indemnity &. Collateral Release Clause: Must confirm the removal of mortgage charges and satisfaction on CERSAI.
If your bank delays your NDC beyond 30 days, claim your ₹5,000 daily penalty. Advocates help recover these funds through nodal officers and the Ombudsman.
9. Lok Adalat Non-Compliance Defense Matrix
Compare available legal routes to enforce your Lok Adalat settlement:
| Enforcement Channel. | Governing Statutory Law. | Procedural Complexity. | Typical Resolution Timeline. | Ultimate Remedy Delivered. |
|---|---|---|---|---|
| Advocate Statutory Legal Notice. | Section 21 LSA Act &. Contract Act. | Direct notice to PNO &. MD. | 7 to 15 Business Days. | Fast branch action, loan closure, and NDC issuance. |
| RBI Banking Ombudsman. | RBI Integrated Ombudsman Scheme, 2021. | Online portal grievance with award proof. | 30 to 45 Calendar Days. | RBI order forcing NDC, CIBIL fix. And delay fines. |
| Civil Court Execution (Order 21 CPC). | Order 21 Rules 30, 32 &. 46 CPC. | Execution petition before Civil Judge. | 2 to 4 Months. | Court attaches bank accounts and executes the decree. |
| Contempt actions (High Court). | Contempt of Courts Act, 1971 / Art. 226. | High Court writ for judicial disobedience. | 3 to 6 Months. | Court fines against bank management and damages. |
10. SettleLoans Lok Adalat Award Enforcement
Enforcing a Lok Adalat order takes skilled legal help. SettleLoans protects borrowers across India. We serve notices on bank executives. We file execution petitions under Order 21 CPC. We win ₹5,000 daily delay fines from the RBI. We also update CIBIL records to a ₹0 balance.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
11. FAQs: Bank Non-Compliance with Lok Adalat Orders
Direct, legally verified answers to critical questions regarding Lok Adalat awards, civil decree executions, No Dues Certificates. And credit bureau rectifications in India.
What is the legal status of a Lok Adalat settlement award under Indian law?
Under Section 21(1) LSA Act, 1987, a Lok Adalat award is a Civil Court decree. Under Section 21(2), it is final and binding. No appeal lies against it.
What can I do if the bank refuses to follow the Lok Adalat settlement order?
File an Execution Petition under Order 21 CPC in Civil Court. The court can attach bank accounts. You can also file a complaint with the RBI Ombudsman.
Can a bank demand additional interest or charges after a Lok Adalat settlement award is passed?
No. The loan merges into the court award once signed. The bank cannot demand extra interest, penal fees, or dues.
Can a bank appeal against a Lok Adalat award in a higher court?
No appeal lies against it under Section 21(2) LSA Act. In Jalour Singh, the Supreme Court held awards can only be challenged on proof of fraud.
What is the RBI timeline for the bank to issue a No Dues Certificate after Lok Adalat payment?
Under RBI Circular RBI/2023-24/60, banks must return papers and issue an NDC within 30 days. Delays carry a ₹5,000 per day fine.
Why is my CIBIL score still showing 'Overdue' or 'Written Off' after Lok Adalat settlement?
Banks often delay credit updates. Under CICRA 2005, lenders must update records to 'Settled' with ₹0 balance within 30 days. You can file a CIBIL dispute and complain to the RBI.
Can recovery agents contact me after a Lok Adalat settlement is executed?
No. Recovery calls after settlement breach the court award and RBI rules. You can send a legal notice and file a police complaint.
In which court should the Execution Petition for a Lok Adalat award be filed?
File the Execution Petition in the Civil Court that referred the case. Or file where the bank branch operates.
What evidence is required to enforce a Lok Adalat settlement order?
You need a certified Lok Adalat Award copy with court stamps. You also need payment receipts, bank statements. And the settlement letter.
Can the Civil Court attach the bank's property or bank accounts if they disobey the Lok Adalat award?
Yes. Under Order 21 Rules 30, 43, and 46 CPC, the Civil Court can attach bank accounts. It can seize assets to enforce the decree.