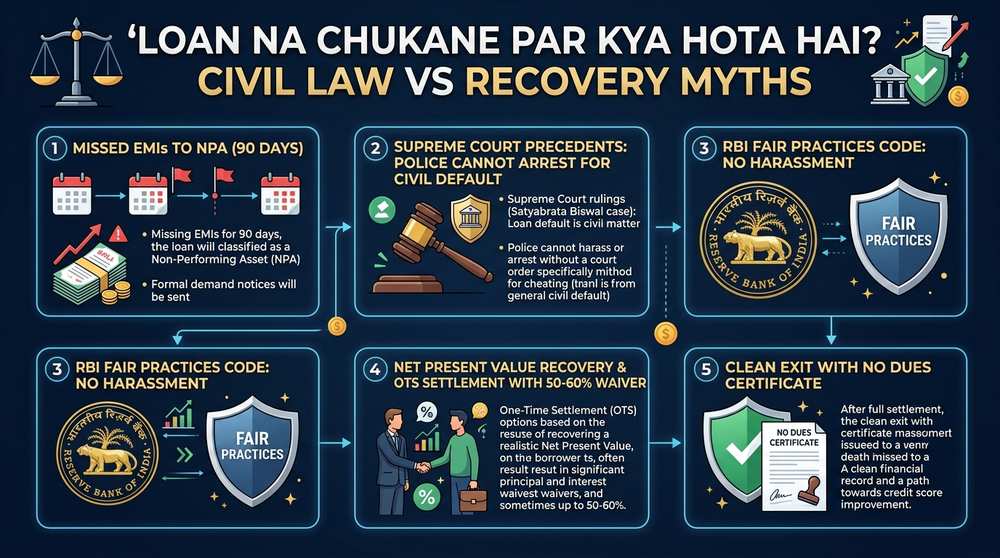
- Zero Criminal Arrest Risk: Defaulting on unsecured loans due to genuine financial insolvency is a civil breach of contract; police have no legal jurisdiction to arrest or detain you.
- Section 420 IPC Inapplicable: Cheating requires proving pre-planned deceit at loan disbursement; genuine post-disbursement default is purely a commercial failure.
- RBI Protection from Harassment: Recovery agents cannot contact relatives, visit workplaces unannounced, call after 7 PM, or issue fabricated legal notices.
- Section 60 CPC Asset Shield: Basic household necessities, tools of trade, salary limits, and employee provident funds (EPF) are completely protected from bank attachment.
- Clean Exit via OTS: An advocate-negotiated One-Time Settlement allows a 45% to 65% principal waiver with a bank-stamped No Dues Certificate.
1. Kya Police Pakad Legi? Loan Default Legal Reality
Jab kisi vyakti ki aarthik sthiti kharab hoti hai—chahe job loss se ya medical emergency se—aur wo bank loan EMIs nahi chuka pata, to sabse bada darr hota hai: "Kya bank police complaint karega? Kya police mujhe pakad legi?"
Is sawal ka spasht kanooni jawab hai: Nahi, police aapko personal loan default par arrest nahi kar sakti. Bharat me loan na chuka pana commercial civil dispute hai, koi criminal offense nahi. Loan agreement Indian Contract Act, 1872 ke tehat civil contract hota hai jisme bank ke paas keval civil recovery ke raste hote hain.
Supreme Court ne tay kiya hai ki police debt recovery agency nahi hai. Agar agent arrest ki dhamki deta hai, to wo khud IPC Section 506 ke tehat apradh karta hai.
2. Civil Breach vs Criminal Fraud: Section 420 IPC & BNS Provisions Debunked
Recovery agents darre hue borrowers ko Section 420 IPC (Cheating) aur Section 406 (Criminal Breach of Trust) ke tehat FIR ki dhamki dete hain. Lekin kanoon ke mutabiq Section 420 ke liye shuruat se hi thagne ki mansha (mens rea) hona zaroori hai. Asali documents par liye gaye loan me baad ka default dhokhadhadi nahi banta.
Supreme Court of India ke Aitihasik Faisle
Dalip Kaur v. Jagnar Singh (2009) 14 SCC 696
Breach of contract ko cheating me tabdeel nahi kiya ja sakta jab tak shuruat me hi thagne ki mansha na ho.
Hridaya Ranjan Prasad Verma v. State of Bihar (2000) 4 SCC 168
Vaada pura na kar pane aur dhokhadhadi me antar hai. Commercial default par FIR dakhil karna kanoon ka durupyog hai.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Recovery Agent Coercion, Fake Police Notices & RBI Safeguards
Bank civil court me lamba samay lagne ke kaaran third-party collection agencies ko commission par hire karte hain. Yeh agents borrower ke darr ka fayda uthane ke liye gair-kanooni hathkande apnate hain:
Fake Police Notices
WhatsApp par farzi seals aur arrest warrants bhejkar darana IPC Section 465/468 ke tehat non-bailable forgery apradh hai.
Relatives & Workplace Calls
Parivar ya employer ko call karke badnam karna RBI Fair Practices Code aur privacy rights ka ghor ullanghan hai.
Abusive Language & Odd Hours
Subah 8 baje se pehle ya sham 7 baje ke baad call karna, gaali dena IPC Section 506 ke tehat dandniya hai.
Illegal Home Visits
Bina official ID card ke ghar par aakar shor machana legal trespass aur criminal harassment banta hai.
RBI Circular (RBI/2022-23/108) ke mutabiq banks apne agents ke har aacharan ke liye kanooni roop se zimmedar hain aur RBI Ombudsman ke madhyam se bank par jurmana lagwaya ja sakta hai.
4. Bank Accounting Realities: NPA Provisioning & The NPV Recovery Formula
Jab borrower 90 din tak EMI nahi bharta, to account Non-Performing Asset (NPA) ban jata hai. Bank ko Substandard NPA me 15% aur Doubtful asset me 100% mandatory provisioning karni padti hai. Kyunki civil court me 3-5 saal lagte hain, bank Net Present Value (NPV) recovery formula se settlement evaluate karte hain:
Where C_t represents estimated recoveries across time periods t, r is the bank discount rate, and deductions account for 3 to 5 years of litigation expenses and locked regulatory capital reserves.
Is commercial model ke karan bank 50% se 65% principal discount par One-Time Settlement (OTS) karne ke liye taiyar ho jate hain, jisse unka blocked capital release ho jata hai.
6. How Advocate Intervention Stops Harassment & Shifts Bank to Settlement
Advocate ke formal legal representation lete hi bank recovery ka roop badal jata hai:
Formal Cease-and-Desist Notice
Bank Nodal Officer ko notice bhejkar direct calls band karwayi jati hain aur communication counsel ke through transfer hoti hai.
Counter-Complaints for Coercion (IPC 506)
Farzi notices ka record banakar Cyber Crime aur Magistrate ke samne counter-criminal proceedings ki jati hain.
RBI Ombudsman Escalation
RBI Integrated Ombudsman portal par recovery violations ki complaint se bank par regulatory penalty ka dabav banta hai.
Direct Institutional OTS Negotiation
Hardship dossier ke aadhar par bank Zonal Committee se 50% se 65% principal waiver par settlement tay hota hai.
7. Sanction Letter Forensics & Section 482 CrPC / 528 BNSS Quashing Precedents
Yadi collection agency Magistrate ke samne Section 156(3) ya Section 200 CrPC ke tehat farzi criminal complaint dakhil kare, to High Court me Section 482 CrPC (Section 528 BNSS) ke tehat petition dakhil karke use turant quash karwaya jata hai:
- No Initial Deceit: Sanction letters aur KYC sabit karte hain ki borrower ne shuruat me koi jaal-saazi nahi ki.
- History of Part-Payment: Shuruati EMIs sabit karti hain ki borrower ki mansha dhokha dene ki nahi thi.
- Civil Nature: Vivad keval balance amount ka hai jiska faisla civil court me hi ho sakta hai.
- Bhajan Lal Precedent: Ulterior motive aur anuchit dabav banane ke liye dakhil criminal case ko High Court radd karta hai.
8. CIBIL Score Impact, Secure Remittance & RBI-Mandated No Dues Certificate
Loan default se credit score 150-250 points gir jata hai. Lekin settlement ke baad recovery band hoti hai aur score re-build hota hai. Surakshit settlement ke 3 anivarya niyam:
1. Official Sanction Letter
Letter bank ke official letterhead par unique reference number ke sath aana chahiye.
2. Direct Bank Remittance
Payment seedhe bank loan account me RTGS/NEFT se honi chahiye, agent ko nahi.
3. Stamped NDC & CIBIL
RBI circular ke tehat 30 din me No Dues Certificate aur CIBIL me Settled status update hota hai.
9. Dispute Resolution Comparative Matrix: Bank Recovery Avenues in India
Bharat me loan default ke recovery madhyamon ka tulnatmak vishleshan:
| Recovery Mechanism | Legal Forum / Authority | Statutory Basis | Criminal Risk | Typical Settlement Outcome |
|---|---|---|---|---|
| Police FIR / Arrest Threat | Local Police Station | Section 420 IPC / 318 BNS | Zero (Rejected) | Quashed or closed as civil matter |
| Summary Recovery Suit | City Civil Court | Order 37, CPC 1908 | None (Monetary) | Compromise decree with installment relief |
| Commercial Arbitration | Arbitrator Tribunal | Arbitration Act | None (Civil Award) | Section 30 Consent Award (45%–60% OTS) |
| Section 138 Cheque Bounce | Magistrate Court | NI Act | Quasi-criminal | Compounded on payment of agreed amount |
| National Lok Adalat | DLSA | Legal Services Act | None (Compromise) | Final award with 50%–70% waiver |
10. SettleLoans Legal Defense Pathway: Your Shield Against Harassment
Karz na chuka pane par darr me jeene ke bajaye sahi kanooni rasta apnayein. SettleLoans banking advocates harassment rukwate hain aur One-Time Settlement (OTS) karwake aarthik aazaadi dilwate hain.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
11. Frequently Asked Questions: Loan Na Chukane Par Kya Hoga
Loan na chukane par bank action, police arrest myths, civil rights aur settlement se jude sawalon ke kanooni jawab.
Kya loan na chukane par police mujhe arrest ya pakad sakti hai?
Nahi. Bharat me personal loan ya credit card default civil breach of contract hai. Supreme Court aadesh ke anusar police bina shuruati fraud ke kisi borrower ko arrest nahi kar sakti.
What is the legal difference between civil loan default and Section 420 cheating?
Section 420 IPC requires proving dishonest intention from day one. Genuine default due to financial hardship after paying initial EMIs is strictly a civil breach, not cheating.
Recovery agent police ki dhamki kyu dete hain aur fake notice kyu bhejte hain?
Agents darr peda karke vasooli karne ke liye dhamki dete hain kyunki civil court me 3-5 saal lagte hain. Farzi notices bhejna IPC Section 506 aur 383 ke tehat dandniya hai.
What actually happens to your CIBIL score when you default on a loan?
90 din par loan NPA banta hai aur score 150-250 points girta hai. One-Time Settlement (OTS) ke baad status 'Settled' ho jata hai, jisse score rebuilding ka rasta khulta hai.
Can bank freeze my salary account or seize my household assets for personal loan?
Unsecured loan me bank bina court decree ke assets seize nahi kar sakta. Section 60 CPC ke tehat gharelu saman aur provident fund (EPF) poori tarah protected hain.
What is the step-by-step NPA timeline after missing loan EMIs?
1-30 din SMA-0 reminders, 31-60 din SMA-1 calls, 61-90 din SMA-2 notices, aur 91 din par account NPA ho jata hai, jahan se OTS settlement ka rasta khul jata hai.
What legal remedies do banks legitimately have to recover unpaid unsecured debt?
Bank Order 37 CPC summary suit, civil arbitration, DRT (₹20 Lakhs se upar), Lok Adalat conciliation ya mutual One-Time Settlement (OTS) se hi recovery kar sakte hain.
What should I do immediately if recovery agents harass my family or workplace?
Recordings save karein. Advocate dwara Nodal Officer ko cease-and-desist notice bhijwayein aur RBI Integrated Ombudsman portal (cms.rbi.org.in) par turant complaint darj karein.
How does advocate-assisted One-Time Settlement (OTS) work for a clean exit?
Advocate Zonal Committee ko financial hardship dossier bhejkar 50%-65% principal waiver negotiate karte hain aur bank-stamped No Dues Certificate jari karwate hain.