- Regulated NBFC Entity. You may borrow via the KreditBee app. KrazyBee Services Private Limited provides the loan. It also issues all legal notices.
- Section 25 PSSA & Arbitration Defense. Section 25 PSSA notices arrive for failed auto-debits. Online arbitration notices may also arrive. A lawyer can answer both notices easily.
- Ban on Third-Party Harassment. Scraping phone contacts breaks RBI rules. Calling relatives or sending WhatsApp threats is illegal under the IT Act.
- 40% to 60% Haircut Approval. When loans pass 90 days unpaid, KrazyBee can settle. The Credit Committee approves 40% to 60% discounts. All penal fees get wiped out.
Corporate Entity Architecture
Borrowers must know who owns their debt. Millions borrow through the KreditBee app. But KreditBee is only a software app run by Finnov Private Limited. The actual loan and legal risk belong to KrazyBee Services Private Limited. It is an RBI-registered NBFC (Registration No. N-02.00262) based in Bengaluru.
Under RBI Digital Lending rules, all norms apply to KrazyBee Services. In some cases, KrazyBee co-lends with other NBFCs. These partners include InCred, Vivriti Capital, Northern Arc, and Piramal Finance. Still, all legal notices and OTS deals come from KrazyBee Services.
Do not negotiate with app chatbots. Do not deal with recovery tele-callers. These agents have no power to give waivers or issue a No Dues Certificate (NDC). Real debt relief requires direct talks with KrazyBee's Stressed Assets team.
Statutory Entity Profile: KrazyBee Services Private Limited
Delinquency Progression & NPA Provisioning
When you miss an EMI, KrazyBee tracks the debt across set stages. As the loan grows older, KrazyBee offers bigger principal waivers.
In the first 30 days (SMA-0), you get automated SMS and app alerts. Between 31 and 60 days (SMA-1), agents call your phone. KrazyBee also runs repeated e-NACH auto-debits. This causes heavy bank bounce fees.
Between 61 and 90 days (SMA-2), collection pressure rises. At 90 days of non-payment, the loan turns into a Non-Performing Asset (NPA).
Under Ind AS 109 rules, an NPA forces KrazyBee to set aside cash reserves. The loan moves to Sub-Standard (90–180 DPD) and Loss Asset (180+ DPD). Provisions rise up to 100%. Holding bad debt hurts their balance sheet. This leads KrazyBee's Credit Committee to accept compromise settlements with large haircuts.
| Delinquency Stage. | Days Past Due (DPD). | NBFC Accounting & Provisioning. | Recovery Tactics & Settlement Window. |
|---|---|---|---|
| SMA-0. | 1 – 30 Days. | Stage 1 Performing Asset (0.4%–1% ECL). | Automated SMS, push alerts, and gentle calls. Full recovery sought. |
| SMA-1. | 31 – 60 Days. | Stage 2 Significant Increase in Credit Risk. | Repeated e-NACH sweeps, bounce fees added, and agency allocation. |
| SMA-2. | 61 – 90 Days. | Stage 2 Pre-NPA Warning Threshold. | Intense telecalling, pre-litigation notices, and restructuring window. |
| NPA (Sub-Standard). | 91 – 180 Days. | Stage 3 Default Asset (25%–40% Provisioning). | Section 25 PSSA legal notices sent. Optimal for 35% to 45% OTS haircut. |
| NPA (Doubtful / Loss). | 181 – 365+ Days. | Stage 3 Loss Asset (70%–100% Full Write-off). | Digital arbitration and Lok Adalat notices. Best 50% to 60% OTS haircut window. |
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
KrazyBee Legal Notices & Sec 25 PSSA
When an account defaults, KrazyBee sends legal notices. These formal letters can look alarming. But they are standard pre-court notices used to start settlement talks.
Section 25 Payment and Settlement Systems Act (PSSA), 2007
The most common notice falls under Section 25 of the Payment and Settlement Systems Act, 2007. When an e-NACH mandate bounces for low balance, Section 25 applies. This works just like Section 138 cheque bounce rules.
The lender must give you 15 days to reply. A Section 25 notice is not an arrest warrant. It is not a court order. It is a compoundable notice. A lawyer can send a reply showing financial hardship. This stops court complaints and opens One-Time Settlement talks.
Unilateral Digital Arbitration & Online Dispute Resolution (ODR)
KrazyBee often sends online arbitration notices. They use private dispute portals. They pick a sole arbitrator in Bengaluru or Delhi without your consent.
The Supreme Court ruled in Perkins Eastman and TRF Ltd on this issue. One-sided arbitrator choices are illegal. Your lawyer can file objections under Section 12, 13, and 16 of the Arbitration Act. This halts biased proceedings and brings lenders to the negotiation table.
Civil Contract Law vs. Fake Criminal Allegations (Section 420 / 406 IPC)
Recovery callers sometimes threaten FIRs under Section 420 and Section 406 of the IPC (or Sections 316 and 318 BNS). The Supreme Court clarified this in Satishchandra Ratanlal Shah and Dalip Kaur. Loan default is purely a civil dispute. It falls under the Indian Contract Act, 1872. The police cannot step into civil loan recovery.
Net Present Value (NPV) Recovery Valuation
To get big loan waivers, you must know how lenders value bad loans. KrazyBee evaluates debts using a Net Present Value (NPV) recovery formula.
Under RBI Master Directions on Compromise Settlements (2023), lenders weigh cash offers against slow court cases. Civil suits and Order 37 CPC summary claims take years to resolve.
C_t is expected recovery. r is the cost of funds. Deductions include court delays, legal fees, agency costs, and locked capital.
App loans range from ₹10,000 to ₹4,00,000. Taking thousands of borrowers to court costs too much money. Court fees quickly exceed the total debt.
Under RBI Fair Lending rules (2024), NBFCs cannot compound penal charges. Our lawyers audit your loan ledger. We wipe out all bounce fees and penal interest. By showing genuine hardship, borrowers can secure 40% to 60% principal waivers from KrazyBee.
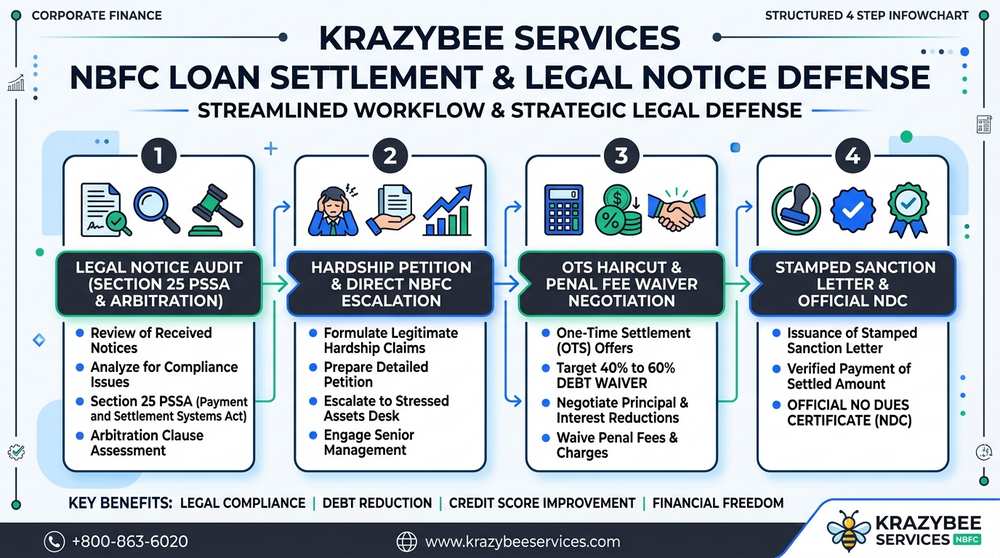
KrazyBee Services NBFC Loan Settlement & Legal Defense Blueprint
Halting Digital Recovery Harassment
Defaulting on an app loan often triggers aggressive recovery calls. Borrowers face continuous phone calls, threats to family, and workplace visits. These tactics violate RBI guidelines and Indian law.
Under the RBI Master Directions on Recovery Agents and Digital Lending Guidelines (2022), clear rules protect borrowers:
Strict Calling Hours (08:00 AM to 07:00 PM Only)
Recovery agents cannot call before 8:00 AM. They cannot call after 7:00 PM. Late-night WhatsApp messages and auto-dialer robocalls are strictly illegal.
Absolute Prohibition of Third-Party Contacting & Data Scraping
Scraping phone contacts breaks RBI rules. Calling friends or employers violates Section 72A of the IT Act, 2000.
Ban on Physical Intimidation, Abusive Language & Impersonation
Abusive language is a crime. Threatening physical visits is illegal. Posing as police officers breaks Sections 419, 503, and 506 IPC (Sections 319 and 351 BNS).
When agents break the law, our team acts immediately. First, we send a Cease-and-Desist Notice to KrazyBee's Nodal Officer. Next, we file a complaint on the RBI CMS Portal. For severe abuse, we file on the Cyber Crime Portal (cybercrime.gov.in). This stops harassment right away.
Step-by-Step NBFC Settlement Roadmap with KrazyBee Services
Follow this six-step roadmap to settle your KrazyBee loan safely:
We inspect your Section 25 PSSA notice and arbitration summons. We help you cancel the e-NACH mandate at your bank to stop bounce charges.
We compile proof of your financial hardship. This includes job loss letters, medical bills, or bank records. We send your file directly to KrazyBee's Stressed Assets desk in Bengaluru.
We examine your full loan ledger. We remove all unlawful bounce fees, penalty interest, and late charges under RBI rules.
Our team negotiates with KrazyBee's Credit Committee. We use bad-debt rules to secure a 40% to 60% principal waiver.
Our lawyers verify the OTS letter on official KrazyBee letterhead. You pay the settlement sum directly to KrazyBee's verified bank account.
KrazyBee must issue your ₹0 No Dues Certificate within 30 days under RBI Circular RBI/2023-24/60. They mark the loan 'Settled' on CIBIL.
KrazyBee Sanction Audit & NDC Mandate
Beware of fake settlement offers from collection telecallers. Rogue agents often send fake WhatsApp receipts. They ask for UPI payments. Paying without a verified letter means your money goes to interest. This leaves your loan unpaid.
Every genuine KrazyBee OTS letter must meet strict standards:
RBI Circular RBI/2023-24/60: 30-Day NDC Mandate & ₹5,000/Day Penalty
Under RBI Circular RBI/2023-24/60, lenders must issue your NDC fast. They get 30 calendar days from full payment. If KrazyBee delays past 30 days, they must pay you ₹5,000 per day of delay.
CIBIL Score Trajectory, Credit Rehabilitation
After settlement, KrazyBee reports the loan as 'Settled'. The balance shows ₹0 on CIBIL and Experian. It also updates on Equifax and CRIF High Mark.
A 'Settled' mark may drop your score by 75 to 150 points at first. But this ends default marks and legal notices. Follow this credit repair plan:
Check ₹0 balance reporting across all four bureaus. Dispute any errors using your stamped NDC.
Get a secured credit card backed by a Fixed Deposit (FD). Use under 25% of the limit and pay on time every month.
Keep a clean 12-month on-time payment track record. Your credit score will climb back to 750+.
Comparative Resolution Matrix: Default vs. Agency vs. Legal OTS
The table below compares unmanaged loan default, agency collection pressure, and legal representation via SettleLoans:
| Key Evaluation Parameter. | Unilateral Default / Inaction. | Dealing with Recovery Telecallers. | SettleLoans Legal NBFC Settlement. |
|---|---|---|---|
| Legal Protection. | Zero. Risk of court summons. Risk of arbitration awards. | Zero. Verbal promises. Fake police threats. | Full legal protection. Lawyer replies. Cease-and-desist notices. Full defense. |
| Collection Harassment. | Daily phone calls. Contact list spam. Office visits. | WhatsApp threats. Untraceable calls. Daily stress. | Complete stop. Direct escalation to KrazyBee Nodal Officer. Complaint to RBI Ombudsman. |
| Penal Charge Waiver. | 0%. Bounce fees compound. Late interest grows. | Minimal. Small verbal discount. High agency fees. | 100% full waiver. Zero bounce fees. Zero late interest. |
| Principal Debt Haircut. | None. Total debt keeps rising. | 0% to 15%. Rarely given in writing. | 40% to 60% debt waiver. Approved by Credit Committee. |
| Sanction Verification. | No written letter. | Fake WhatsApp receipts. Rogue UPI payment risk. | Stamped OTS letter on official KrazyBee letterhead. |
| Closure & CIBIL Update. | 90+ DPD default marks damage your credit score. | Leftover dues keep loan active on CIBIL. | Clean ₹0 No Dues Certificate within 30 days under RBI rules. |
Why Borrowers in Distressed Borrowers Choose SettleLoans
SettleLoans is India's leading legal debt resolution advisory. We protect borrowers against aggressive fintech collection practices. We negotiate institutional settlements.
We handle all creditor talks. We audit your loan ledger. We reply to Section 25 PSSA and arbitration notices. Our team negotiates directly with KrazyBee in Bengaluru. We ensure complete transparency until your verified ₹0 No Dues Certificate arrives.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: KrazyBee NBFC Loan Settlement
What is the relationship between KrazyBee Services Private Limited and KreditBee?
KrazyBee Services Private Limited is an RBI-registered NBFC (Registration No. N-02.00262). KreditBee is a digital app run by Finnov Private Limited. Users apply for loans through the app. But KrazyBee lends the money. KrazyBee also issues legal notices and approves One-Time Settlements (OTS).
How should I respond to a Section 25 PSSA legal notice issued by KrazyBee Services?
A Section 25 PSSA notice gives you 15 days to reply. It is not an arrest warrant. It is not a court order. Do not panic. Hire a lawyer to send a formal reply within 15 days. The reply explains your money hardship and opens direct settlement talks.
Can KrazyBee recovery agents call my family, friends, or employer for loan default?
No. Under RBI Digital Lending rules, agents cannot call third parties. They cannot scrape your contacts. They cannot call office staff or relatives. Calling third parties breaks Section 72A of the IT Act. You can file a police and RBI complaint.
What percentage of debt waiver or haircut can you negotiate on a defaulted KrazyBee loan?
Unsecured loans turn into NPAs after 90 days unpaid. KrazyBee then offers 40% to 60% debt waivers. Your lawyer also gets a 100% waiver on all bounce fees. All penal charges get waived under RBI Fair Lending rules.
Can KrazyBee or KreditBee file a police complaint (FIR) or have me arrested for loan default?
No. Loan default is a civil breach of contract under the Indian Contract Act, 1872. Police cannot file an FIR. They cannot arrest you for inability to pay. Fake police threats and bogus arrest warrants violate RBI rules.
How should I handle unilateral online arbitration notices sent by KrazyBee legal counsel?
The Supreme Court ruled in Perkins Eastman and TRF Ltd. One-sided arbitrator choices are illegal. Your lawyer files objections under Section 12 and Section 14 of the Arbitration Act. This halts biased hearings and starts settlement talks.
How can I verify that a KrazyBee settlement letter is genuine and authentic?
A real OTS letter uses KrazyBee Services Private Limited letterhead. It lists the CIN and RBI Reg No. N-02.00262. It shows your name, loan account number, settlement sum, and due date. Always pay into KrazyBee's official bank account. Never pay a personal UPI handle.
How long does KrazyBee take to issue the No Dues Certificate (NDC) and update CIBIL?
Under RBI Circular RBI/2023-24/60, KrazyBee must issue the NDC within 30 days. They must also update credit bureaus in 30 days. If KrazyBee delays past 30 days, they must pay you ₹5,000 per day of delay.
How does settling a KrazyBee loan affect my CIBIL score and credit history?
KrazyBee reports the loan as 'Settled' with a ₹0 balance to CIBIL. Your score may drop 75 to 150 points at first. But this ends default marks and legal notices. You can rebuild your score to 750+ within 18 to 24 months using a secured card.
Who has the authority at KrazyBee Services to sanction a One-Time Settlement?
Recovery callers have zero power to approve loan discounts. Real waivers of 40% to 60% come from KrazyBee's Credit Committee. Always demand an official stamped sanction letter before paying.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24).
- RBI Regulatory Framework for Digital Lending: Guidelines on Digital Lending & Loan Service Providers (LSPs) (2022).
- RBI Master Circular: Fair Practices Code for Non-Banking Financial Companies (NBFCs) & Recovery Agent Governance.
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online Redressal Portal for Complaints on NBFC Harassment & Excessive Penalties.
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987 — National Lok Adalat Conciliation Framework.