- Multi-Bureau Asymmetry: Banks send data separately to Experian. Settled loans often stay wrongly marked as 'Written-Off'.
- 30-Day CICRA Mandate: Section 21 of CICRA 2005 requires lenders and Experian to resolve disputes within 30 days.
- ₹100/Day RBI Penalty: RBI Circular RBI/2023-24/72 mandates ₹100 daily payout for delayed dispute resolutions.
- Convert Settled to Closed: Repay the waived principal balance to convert your Experian status to 'Closed'.
- Fintech API Underwriting: Fixing Experian errors stops automated rejections on loan and credit card applications.
1. The Multi-Bureau Architecture in India
In India, the CICRA Act 2005 governs credit reporting. The Reserve Bank of India licenses four bureaus: CIBIL, Experian, Equifax, and CRIF High Mark. Many borrowers only monitor CIBIL. But top banks like SBI, HDFC, ICICI, Axis, and Kotak also check Experian. Digital apps and NBFCs check Experian too.
Many borrowers settle a loan through One-Time Settlement (OTS). Their CIBIL report updates, but Experian still shows 'Written-Off&apos. or 'Settled'. This happens because banks report to each bureau independently. Banks pull internal records and send separate monthly data files to each bureau.
Technical delays or bank filing errors often cause data gaps. When this happens, Experian receives outdated files. Borrowers who paid their dues then face low credit scores and instant loan rejections. Understanding Experian terms helps you fix these errors quickly.
A status of "Settled" means the bank accepted a discounted amount and absorbed a loss. A "Closed" tag means you paid the full loan with zero loss to the lender.
A "Written-Off" tag shows an active default where the bank wrote off bad debt. A "Post-Write-off Settled" tag shows you paid the agreed settlement with a ₹0 balance.
If a bank fails to send fresh data, Experian continues showing old defaults. This failure harms your credit rating and violates your rights under Indian credit reporting laws.
2. Statutory Grounding for Experian Disputes
Your right to accurate credit data is protected by law. The primary law is the Credit Information Companies (Regulation) Act, 2005 (CICRA). It works alongside the CIC Rules and Regulations 2006.
Under Section 21 of the CICRA Act 2005, banks and credit bureaus must keep accurate records. Section 21(3) requires them to fix wrong data within 30 calendar days of receiving a dispute.
The Reserve Bank of India issued Circular RBI/2023-24/72 to protect borrowers. Under this rule, lenders and bureaus must resolve disputes within 30 calendar days. If they fail, they must pay you ₹100 per day of delay directly into your bank account.
Under Section 22 of the CICRA Act 2005, you can escalate unresolved disputes to legal settlement or arbitration. Did lenders ignore your settlement proof? You can claim payout for service deficiency under the Consumer Protection Act, 2019.
Section 21 of CICRA requires banks and bureaus to correct disputed data within 30 days.
The RBI Banking Ombudsman can penalize banks and order quick credit report corrections.
The Consumer Protection Act 2019 lets borrowers claim damages for wrongful loan rejections.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. The Mechanical Anatomy of Credit Bureau Inaccuracies
To understand why errors happen on Experian, look at how banks process settled loans. When you complete an OTS settlement, the bank verifies payment. Then, bank staff must update internal records and tag the account for credit bureaus.
The stressed assets team notifies the operations team to update the core banking system. But three common breakdowns often occur:
Premature Balance Sheet Write-Off Prior to Settlement Inflow
Banks often write off bad loans after 180 days. Did you settle after this write-off? The bank often forgets to update Experian. Your status must show "Post-Write-off Settled". with a ₹0 balance.
Fragmented Multi-Bureau Member Reporting Feeds
Banks often update CIBIL first and delay Experian files. Any format glitch or data error can freeze your Experian profile in default status.
Lingering Phantom Overdue Balances & DPD Accumulation
Some bank systems leave waived amounts in the overdue field. Showing an overdue balance on a settled account lowers your credit score every month.
These errors cause serious harm. Digital lenders check Experian records via automated APIs. If the system detects an active default or overdue amount, it rejects your loan application instantly.
4. Bank Balance Sheet Accounting, NPA Provisioning
Banks must follow RBI Prudential Norms on Income Recognition, Asset status and reserves (IRACP). These rules force lenders to set aside capital reserves for overdue accounts:
| default status. | Overdue Aging Timeline. | Mandatory RBI Capital Provision. | Experian Bureau Reporting Status. |
|---|---|---|---|
| Special Mention Account 1 (SMA-1). | 31 – 60 Days Overdue. | 5% Capital Reserve. | 30+ Days Past Due (DPD) Warning Flag. |
| Special Mention Account 2 (SMA-2). | 61 – 90 Days Overdue. | 10% Capital Reserve. | 60+ DPD default Tag. |
| Substandard NPA. | 91 – 365 Days Overdue. | 25% Capital Reserve. | NPA / Default Status. |
| Doubtful NPA 1 (D1) / Loss Asset. | 12+ Months Default. | 100% Full Provision. | Written-Off / Settled ₹0. |
When you file a CICRA 2005 dispute, the bank faces compliance costs. They also risk ₹100/day fines under RBI Circular RBI/2023-24/72. Bank credit teams assess dispute resolution using Net Present Value (NPV):
In this model, C_t represents settlement cash flow and r is the discount rate. Deductions include daily RBI fines (₹100/day), legal fees. And regulatory audit risks.
Banks face fines and reputational risk for wrong reporting. Therefore, lenders act quickly to update credit files once they receive formal legal notices.
5. Experian Credit Dispute Strategic Roadmap
This roadmap guides you from settlement to credit repair. It covers your No Dues Certificate, online dispute filing. And score recovery to 750+.
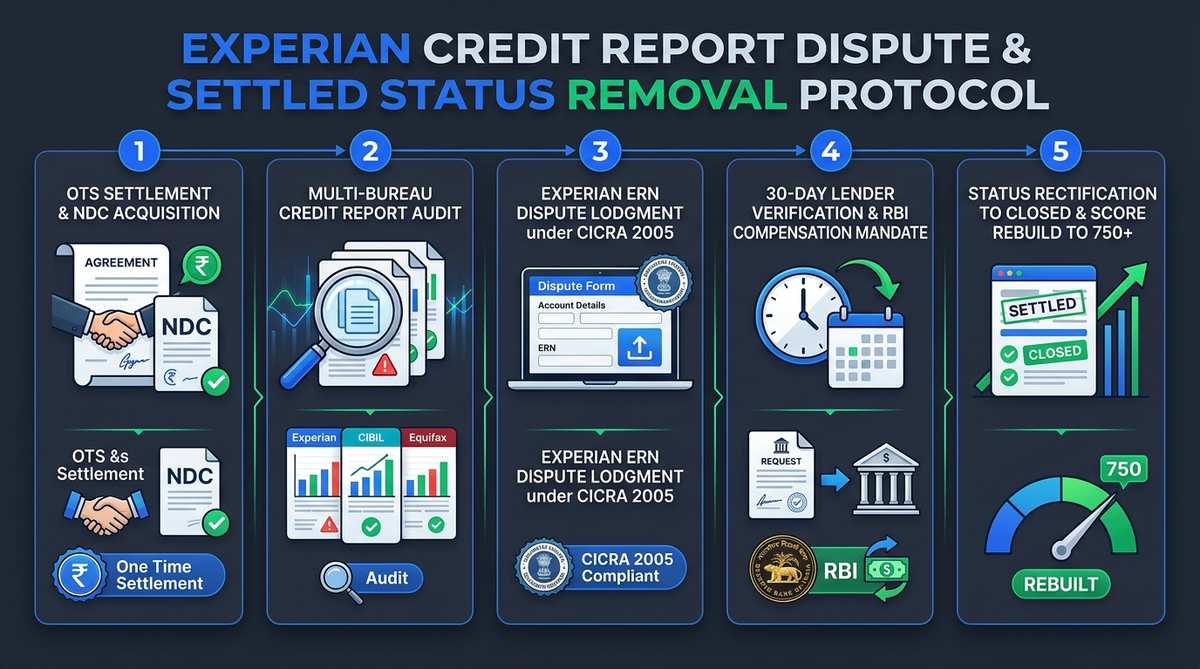
6. Step-by-Step Experian India Dispute Protocol
Fixing an Experian record requires proper legal documents and official channels. Calling regular customer care rarely works. Customer agents cannot change records without bank approval. Follow this 4-stage Experian dispute process:
Stage 1: Generate Latest Experian Credit Report & Extract ERN
Get your recent Experian report. Find your unique 10-digit Experian Report Number (ERN) at the top. You need an ERN issued in the last 30 days to file a valid dispute.
Stage 2: Lodge Formal Online Dispute on Experian Consumer Portal
Go to the Experian India Online Dispute Portal. Enter your ERN, PAN, date of birth. And phone number. Select the account and dispute the Account Status and Overdue Balance.
Stage 3: Upload Comprehensive Evidentiary Dossier
Upload clear copies of key documents: (1) Official Settlement Sanction Letter, (2) Bank statements with UTR numbers, and (3) Stamped No Dues Certificate (NDC).
Stage 4: Experian-to-Bank Verification Loop & 30-Day Resolution
Experian sends a verification request to your bank. Under CICRA rules, the bank has 21 calendar days to verify records. Experian will update your report within the 30-day legal window.
Did the bank fail to reply within 21 days? Send a legal notice to the bank's Principal Nodal Officer immediately.
7. Converting "Settled" Status to "Closed"
Did you settle a loan in the past? Your report may show "Settled". with a ₹0 balance. This tag is factually correct after a settlement. However, automated bank filters may still flag it as a risk. This can lead to instant rejections on new loans.
Under RBI rules, you can ask the original lender for a Post-Settlement Account Closure Agreement. This lets you upgrade a "Settled". status to "Closed":
Send a formal request to the bank's Stressed Assets desk. Ask for the exact calculation of the waived principal amount.
Agree to repay only the waived principal amount. Ensure all penal charges and legal fees are fully waived.
Once you clear the balance, the bank issues a fresh Loan Closure Certificate. This confirms full loan repayment.
The bank sends an updated data file to Experian and CIBIL. This updates your account status from "Settled". to "Closed".
Changing your status from "Settled". to "Closed". removes default tags. It helps you unlock prime interest rates.
8. Sanction Letter Forensics & NDC for Experian
Do not rely on verbal promises or unverified settlement letters from collection agents. Fake settlement letters waste your money and leave your Experian record in default.
- Official Bank Letterhead &. Digital Signature: The letter must come from the corporate office. It needs authorized digital signatures.
- Explicit Account &. PAN Recital: It must list your full name and PAN. It must state your exact 16-digit loan account number.
- Unambiguous Credit Bureau Reporting Clause: The letter must promise accurate bureau reporting. The bank must report the account as "Settled". or "Closed". with ₹0 balance to Experian and CIBIL.
- Direct payment into Official Loan Account: Always pay directly into your official loan account. Use NEFT, RTGS, or IMPS.
Under RBI Circular RBI/2023-24/60, all banks and NBFCs must issue a No Dues Certificate (NDC). They must also update credit bureaus to ₹0 balance within 30 calendar days. If a lender delays beyond 30 days, they must pay you ₹5,000 for each day of delay.
The Experian Score Rehabilitation Trajectory (580 to 750+)
Once Experian updates your status to "Closed". with ₹0 balance, your score begins to recover. Follow three simple steps. First, get a fixed-deposit credit card with a ₹30,000–₹50,000 limit. Next, keep credit usage below 25%. Finally, pay bills in full every month. Your score can reach 750+ within 12 to 18 months.
9. Experian Credit Report Dispute Matrix
Compare the main dispute and rectification options under Indian banking laws:
| Dispute Mechanism. | Governing Legal Framework. | Turnaround Timeline. | Bureau Status Outcome. | Legal Enforceability. |
|---|---|---|---|---|
| Direct Experian ERN Online Dispute. | Section 21 CICRA Act 2005. | 30 Calendar Days. | Status Updated / Corrected to ₹0. | Binding legal Mandate. |
| Advocate Legal Notice to Nodal Officer. | CICRA 2005 &. Consumer Protection 2019. | 15 Calendar Days. | Expedited Member File Submission. | Pre-Litigation Legal Instrument. |
| RBI Integrated Ombudsman Escalation. | RBI Circular RBI/2023-24/72. | 30 – 45 Days. | Compelled Rectification + ₹100/Day Award. | legal Regulatory Award. |
| Post-Settlement Closure Agreement. | RBI Prudential Compromise Framework. | 20 – 30 Days. | Converted from Settled to "Closed" | Bilateral Contractual Discharge. |
10. SettleLoans Multi-Bureau Dispute Defense
Fixing multi-bureau credit errors in India requires legal and banking expertise. At SettleLoans, our legal team audits your reports across Experian, CIBIL, Equifax, and CRIF High Mark. We detect wrong entries, illegal write-offs. And phantom balances. We serve legal notices to bank Nodal Officers and file Experian disputes. We also escalate delays to the RBI Ombudsman. Our team helps you convert "Settled". marks to clean "Closed". accounts.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
11. FAQs: Experian Credit Report Disputes
Direct answers to common questions about Experian disputes, CICRA rules. And credit score recovery.
Can you completely remove a Settled status from an Experian credit report?
You cannot delete a genuine 'Settled' mark without paying the dues. But you can convert 'Settled' to 'Closed'. Pay the remaining waived principal to the lender, get a fresh No Dues Certificate. And have the bank update Experian India.
Why does Experian India show Written-Off when CIBIL shows Settled?
Banks send data files to each credit bureau separately. If a bank misses an Experian update, old 'Written-Off' remarks remain visible until you raise a formal dispute under CICRA 2005.
What is the statutory turnaround time for an Experian credit report dispute under CICRA 2005?
Under Section 21 of the CICRA Act 2005, credit bureaus and banks must investigate and resolve credit report disputes within 30 calendar days.
What compensation is available under RBI rules if a credit bureau dispute exceeds 30 days?
Under RBI Circular RBI/2023-24/72. If a bank or bureau fails to resolve a dispute within 30 calendar days, they must pay you ₹100 per day of delay directly into your bank account.
What documents are required to file an online Experian credit report dispute?
You need: (1) Your 10-digit Experian Report Number (ERN), (2) Settlement Sanction Letter, (3) Payment receipts with UTR numbers, and (4) Stamped No Dues Certificate (NDC).
How does converting Settled to Closed impact my Experian credit score?
Converting 'Settled' to 'Closed' removes default flags. This can lift your Experian score by 45 to 90 points immediately and help you reach 750+ within 6 to 12 months.
What should I do if the bank fails to respond to Experian's dispute verification request?
If the bank does not verify records within 21 days, send an advocate legal notice to the bank's Principal Nodal Officer and file a complaint on the RBI Ombudsman portal (cms.rbi.org.in).
Do fintech lenders and NBFCs check Experian India in addition to CIBIL?
Yes. Many digital loan apps and NBFCs check Experian India in real time for automated loan approvals.
Can an advocate force a bank to correct an erroneous credit bureau remark?
Yes. Advocates use Section 21 of CICRA 2005, the RBI Ombudsman Scheme. And the Consumer Protection Act to compel banks to correct erroneous records and pay payout.
What is the difference between Written-Off and Post-Write-off Settled in Experian?
'Written-Off' means the bank booked the unpaid loan as a 100% loss. 'Post-Write-off Settled' means you paid a negotiated settlement after write-off, reducing the balance to ₹0.