- Civil Nature of Default. Loan default is a civil dispute. Local police cannot issue summons or file FIRs for unpaid bank debt.
- Salary Protection. Section 60(1) CPC and Section 171 Contract Act protect techie and govt pay from bank liens.
- Vanchiyoor Court Defense. Prompt replies to Section 138 NI Act and Section 25 PSSA notices halt criminal claims. Cases move to Lok Adalat.
- Zonal SARB Waivers (40%–70%). MG Road SARB talks yield 40% to 70% principal cuts and full penal fee waivers.
- Mandatory ₹0 NDC in 30 Days. Under RBI Circular RBI/2023-24/60, banks must issue closure letters within 30 days or pay ₹5,000 daily penalty.
Debt Landscape & Borrowers in Trivandrum
Trivandrum is Kerala's state capital and tech hub. Technopark in Kazhakkoottam employs thousands of IT engineers. The city hosts the Secretariat, ISRO's VSSC in Thumba, and BrahMos. Trade routes span Chalai Market, Palayam, Pattom, and Kowdiar down to Kollam.
Banks like SBI, Federal Bank, Canara, and HDFC disbursed large personal loans. NBFCs like Bajaj Finance gave digital credit lines. But IT layoffs, salary cuts. And medical emergencies have hit cash flow. Many staff and business owners now struggle to pay monthly EMIs.
Technopark engineers and govt staff fear background checks and workplace shame. Recovery agents in Vazhuthacaud harass debtors illegally. They call HR teams and family in Kowdiar and Peroorkada. This breaks RBI rules. Borrowers have legal remedies to stop harassment and settle debt.
NPA Delinquency Aging in Trivandrum
Under RBI IRACP norms, unpaid loans move through SMA stages. After 90 days of default, the loan becomes an NPA. Banks must then set aside reserve funds. This rule pushes bank managers to approve OTS waivers.
| default Stage. | Aging Threshold. | Mandatory Bank Provisioning. | Institutional Strategy &. OTS Scope. |
|---|---|---|---|
| SMA-0 &. SMA-1. | 1 – 60 Days Overdue. | Standard Capital Reserve. | Regular Reminders. Automated calls and penalty fees begin. Debt waivers are not available. |
| SMA-2. | 61 – 90 Days Overdue. | Pre-NPA Watchlist Reserve. | Pre-NPA Alerts. Demand notices go out. Branches evaluate loan restructuring or tenure extension. |
| Substandard NPA. | 91 – 365 Days Overdue. | 15% – 25% Profit Provision. | SARB Transfer. Files move to MG Road SARB desks. 35% to 50% principal waivers open up. |
| Doubtful (D1 / D2). | 1 – 3 Years Overdue. | 40% – 100% Capital Lock. | Balance Sheet Cleanup. Lenders aim to resolve bad loans. 50% to 65% waivers become viable. |
| Loss Asset. | 3+ Years Overdue. | 100% Written-off Balance. | Deep Waivers. Accounts are written off. Up to 70% waivers are settled in Lok Adalat. |
The Kerala High Court bans harsh loan recovery acts. Lenders cannot use muscle power to harass debtors at home or work. Loan recovery must follow civil law and respect privacy under Article 21 of the Constitution of India.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Defending Legal Notices in Vanchiyoor Courts
Bounced NACH debits or cheques trigger legal demand notices. Banks issue these under Section 138 of the Negotiable Instruments Act, 1881. They also issue them under Section 25 of the Payment and Settlement Systems Act, 2007 (PSSA). Notices cite CJM or JFCM Magistrate Courts. These sit at Vanchiyoor Court in Trivandrum.
Borrowers get a 15-day statutory response window to reply. Ignoring notices lets banks file cases under Section 142 NI Act. This leads to court summons. A formal reply by advocates proves no criminal intent. It details real hardship like tech layoffs or medical bills. It also disputes unfair fees and invites settlement talks.
Court trials take years and bring high costs. A prompt legal reply moves files to MG Road SARB desks. It can also lead to fast compromise in DLSA Lok Adalat.
Banker's General Lien Rules in Trivandrum
Under Section 171 of the Indian Contract Act, 1872, banks have a general lien. This applies to funds within the same bank under matching CIF or PAN data. If a loan defaults, that bank may try to freeze linked savings or salary accounts.
This lien does not apply to other banks. An SBI default cannot touch accounts in Federal Bank or HDFC. Also, Section 60(1) of the Code of Civil Procedure (CPC), 1908, shields salary pay. Under Section 60(1)(i) CPC, the first ₹1,000 and two-thirds of the rest are exempt from attachment.
Borrowers can shift salary credits to an unlinked bank. They can also cancel NACH mandates in writing under RBI rules.
Personal Loan Settlement Roadmap in Trivandrum & Kerala
The chart below outlines each step of the debt settlement process in Thiruvananthapuram. It covers workplace privacy protection, Vanchiyoor court defense, SARB talks. And final ₹0 No Dues Certificate issuance.
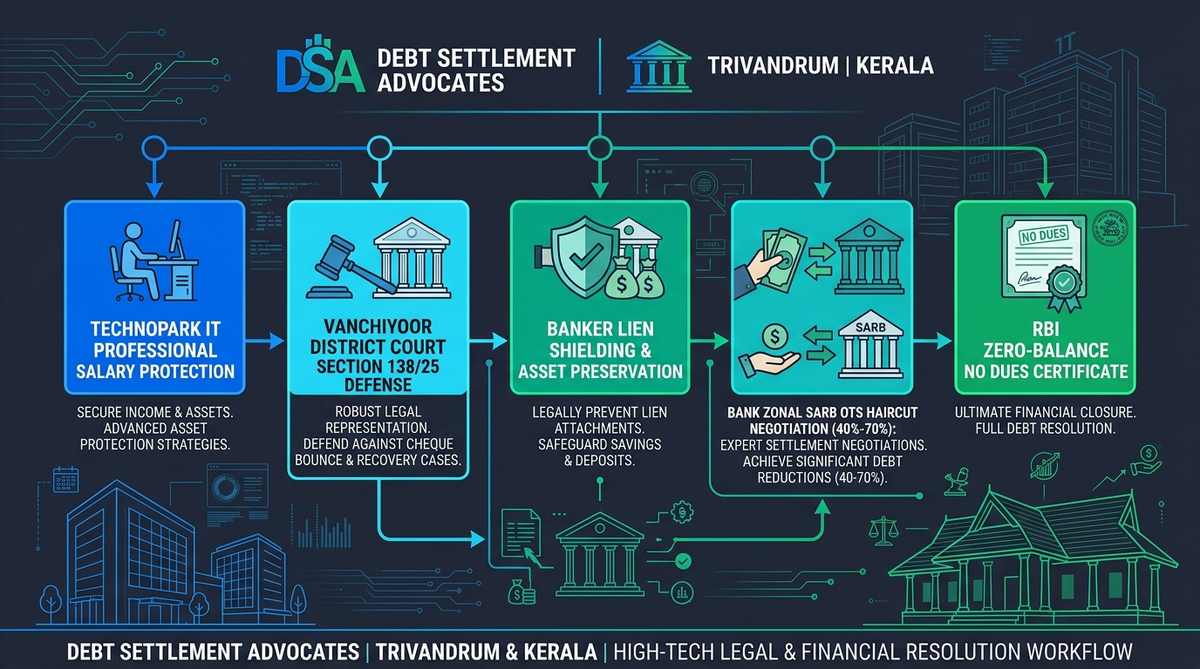
Figure 1.0: End-to-End Trivandrum Debt Settlement Framework, Vanchiyoor Court Defense &. Bank Zonal SARB Resolution Protocol.
OTS Haircut Mechanics & NPV in Trivandrum
Bank committees on MG Road assess OTS offers. They use the Net Present Value (NPV) formula. They weigh quick cash against years of slow court recovery.
Here C_t is expected yearly recovery. The symbol r is the discount rate. Deductions cover court costs and locked NPA funds.
Court battles tie up bank funds and incur legal fees. A cash OTS gives quick liquidity to the lender. Under RBI rules, bank committees approve 40% to 70% principal waivers. They also waive 100% of penal interest and late fees.
Enforcing RBI Fair Practices in Trivandrum
Under RBI Master Directions (2022), recovery agents must follow strict rules. They cannot call before 8:00 AM or after 7:00 PM. They cannot use threats or abuse. Agents cannot visit Technopark or govt desks without prior consent. Visiting agents must show official ID and bank letters.
Under the Kerala Police Act, 2011, police cannot handle civil debt claims. The Supreme Court confirmed this in Arnesh Kumar v. State of Bihar and Lalita Kumari v. Govt. of UP. If agents make threats, our advocates send legal notices to bank nodal officers. We also file complaints on the RBI Integrated Ombudsman Portal (CMS).
5-Step Settlement Protocol in Trivandrum
Settling debt with banks in Trivandrum follows a 5-step roadmap:
Financial Hardship Dossier Compilation
We audit total debt and collect hardship proofs. Proofs include layoff memos, pay cuts, medical bills. And bank distress statements.
Cease-and-Desist Notice & Workplace Privacy Shield
Our advocates send formal notices to bank nodal officers. This bars recovery visits to Technopark desks, govt offices, or homes.
Statutory Notice Defense in Vanchiyoor Courts
We reply to Section 138 NI Act and Section 25 PSSA notices in 15 days. This refutes criminal claims and seeks Lok Adalat settlement.
Direct Negotiations with MG Road Zonal SARB Desks
We talk directly with SARB desks on MG Road. We secure 40% to 70% principal waivers using NPV formulas.
Sanction Letter Audit & Mandatory NDC Delivery
We verify stamped OTS letters before direct RTGS payment. We also ensure fast delivery of your ₹0 No Dues Certificate under RBI rules.
Sanction Letter Audit & NDC in Trivandrum
Never pay money on verbal promises or WhatsApp chats. A valid OTS Sanction Letter comes on bank letterhead. It bears the manager's sign, bank seal, exact waiver sum. And full closure terms.
Under RBI Circular RBI/2023-24/60, lenders must issue the No Dues Certificate (NDC) in 30 days. Unlawful delay requires a penalty of ₹5,000 per day paid to the borrower. Bureaus update to 'Settled&apos. with ₹0 balance. You can rebuild scores above 750 in 18 to 24 months.
Debt Resolution Pathways in Trivandrum
Comparing debt resolution paths helps Trivandrum borrowers choose the right strategy:
| Resolution Pathway. | Principal Haircut Range. | Legal Binding Finality. | CIBIL Bureau Status. | Resolution Timeline. |
|---|---|---|---|---|
| Direct Zonal SARB Settlement (Trivandrum). | 40% – 70% Principal Haircut. | Complete. Bank issues formal NDC. | 'Settled&apos. / ₹0 Dues. | 3 to 6 Weeks. |
| DLSA Lok Adalat (Vanchiyoor Court). | 45% – 70% Principal Haircut. | Absolute. Acts as Civil Court Decree. | 'Settled&apos. / ₹0 Dues. | Quarterly Cycles. |
| Bank Loan Restructuring. | 0% Haircut (Tenure Extension). | Conditional. Depends on ongoing EMI. | 'Restructured&apos. / Active Debt. | 2 to 4 Weeks. |
| Civil Court Litigation (Vanchiyoor / High Court). | Uncertain (Subject to Decree). | Prolonged. Subject to appeals. | 'Suit Filed&apos. / Compounding. | 4 to 7 Years. |
SettleLoans Legal Defense in Trivandrum
Resolving loans in Trivandrum needs legal skill. We protect your reputation and defend court notices. We negotiate with bank Zonal Committees. SettleLoans helps professionals achieve debt relief.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Thiruvananthapuram
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Thiruvananthapuram can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Vanchiyoor, Thiruvananthapuram, Kerala - 695035
Jurisdiction: Vanchiyoor Judicial First Class Magistrate courts adjudicate ECS bounce and civil money suits under the Kerala judicial framework.
Address: ADR Centre, District Court Complex, Vanchiyoor, Thiruvananthapuram - 695035
Lok Adalat Conciliation: Operates under Kerala State Legal Services Authority (KELSA) guidelines, facilitating equitable settlements for NRI and domestic borrowers.
FAQs: Personal Loan Settlement in Trivandrum
Why do Technopark IT professionals and government employees in Trivandrum require specialized debt settlement advocates?
Technopark software engineers and government servants face unique job risks. These include background checks and workplace reputation. Recovery agents exploit these fears by threatening office visits. Empanelled Trivandrum debt settlement advocates enforce RBI rules. They represent clients before Vanchiyoor courts. They also protect salary accounts from unlawful banker liens. also, they negotiate 40% to 70% One-Time Settlement (OTS) waivers with bank Zonal SARB desks on MG Road and Vazhuthacaud.
Can a bank freeze or auto-debit my salary account under Section 171 Banker's Lien in Kerala?
Under Section 171 of the Indian Contract Act, 1872, a bank has a general lien only on accounts in its own branch network. A bank cannot freeze or debit funds in another bank without a Civil Court order. also, Section 60(1) of the Code of Civil Procedure, 1908, shields basic salary from attachment.
Can the Thiruvananthapuram City Police or local police stations arrest me for personal loan default?
No. Involuntary loan default is a civil dispute under the Indian Contract Act, 1872. Police stations in Kazhakkoottam, Cantonment, Museum, Medical College, and Vanchiyoor cannot file FIRs or arrest debtors for unpaid loans. The Supreme Court confirmed this in Arnesh Kumar v. State of Bihar and Lalita Kumari v. Govt of UP.
How should I respond to Section 138 NI Act or Section 25 PSSA notices issued in Vanchiyoor Court?
You must send a legal reply through an advocate within 15 days of getting a notice under Section 138 of the Negotiable Instruments Act, 1881, or Section 25 of the PSSA, 2007. The reply shows genuine financial distress. It proves there was no dishonest intent. It also challenges unfair fines and proposes an OTS via the National Lok Adalat.
How does the District Legal Services Authority (DLSA) Thiruvananthapuram Lok Adalat settle loan disputes?
The DLSA Thiruvananthapuram holds National Lok Adalats at the Vanchiyoor District Court Complex. Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat settlement award acts as a final Civil Court decree. The bank cannot appeal or file new cases. It must also provide a zero-balance closure letter.
What percentage of debt waiver can borrowers in Trivandrum and Kollam expect through bank OTS policies?
Loan age and NPA status determine the discount. Documented hardship like tech layoffs, salary cuts, or medical costs also helps. Senior advocates secure 40% to 70% principal waivers. They also get a 100% waiver on penal interest and late fees.
How do advocates prevent recovery agents from visiting Technopark campuses or government offices?
Advocates send formal Cease-and-Desist notices to the bank's Principal Nodal Officer and Zonal Asset team. These notices cite RBI Master Directions (2022). The rules ban workplace visits and calls outside 8:00 AM to 7:00 PM. Any violation goes to the RBI Ombudsman and City Police Commissionerate.
Can the entire loan settlement process in Trivandrum be handled confidentially and digitally?
Yes. SettleLoans provides a secure, digital debt defense process. We handle liability audits, hardship files, legal replies, and SARB talks remotely with full privacy. Empanelled Trivandrum advocates represent you under a formal Vakalatnama at Vanchiyoor Court if needed.
What is the mandatory timeline for banks to issue a No Dues Certificate (NDC) under RBI circulars?
Under RBI Circular RBI/2023-24/60, banks and NBFCs must issue a No Dues Certificate (NDC) within 30 days of full settlement. They must also update credit bureaus. If a lender delays without cause, it must pay the borrower ₹5,000 per day of delay.
How does personal loan settlement affect credit scores and what is the rehabilitation timeline?
The bank reports the account to CIBIL and Experian as 'Settled' with a ₹0 balance. This causes a short-term drop of 75 to 150 points. However, it stops overdue reporting. Borrowers can rebuild their score above 750 in 18 to 24 months with good credit habits.