- Zero SARFAESI on Personal Debt: Unsecured loans carry no mortgage charges. Lenders cannot auction your machines or home without a civil court order.
- Statutory Tool Protections: Section 60(1)(b) & (c) CPC protects your artisan tools, machines, and basic home from court attachment.
- Section 138 NI Act Compounding: Under Section 147 NI Act, you can settle cheque bounce cases in Rajkot courts through an agreed OTS.
- 40%–70% OTS Waivers: Advocate-led talks with bank Stressed Asset Committees win large principal cuts and full CIBIL ₹0 clearance.
1. Anatomy of the Rajkot MSME & Engineering Debt Crisis
Rajkot, Jamnagar, and Bhavnagar form Western India's engineering hub. There are over 30,000 MSMEs in this region. Key clusters thrive in Aji GIDC and Shapar-Veraval. Lodhika GIDC and Bhaktinagar are also major industrial hubs. Jamnagar hosts the primary brass manufacturing cluster. These units make iron castings, auto forgings, pumps, and tools. They face heavy cash needs and long credit cycles.
Rising metal prices hurt profit margins significantly. Long payment delays from auto OEMs exhaust credit limits. Promoters then take high-interest personal loans for factory bills. When cash dries up, missed EMIs cause multi-lender defaults.
2. Legal Distinctions for Rajkot Borrowers
Secured loans and personal loans differ under the law. Secured lenders with mortgages can issue Section 13(2) notices under the SARFAESI Act, 2002. They can take possession under Section 13(4). But this rule applies only to pledged property.
Unsecured personal loans and digital credit lines have no mortgage charge on your plant, machines, or home. Lenders cannot seal workshops or auction assets without a civil court order. Civil suits in Gujarat courts take 3 to 7 years. Because of this, lenders prefer fast out-of-court OTS settlements.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Statutory Protections for Saurashtra Borrowers
Borrowers across Saurashtra enjoy strong legal safeguards. Section 60(1)(b) and (c) of the CPC protects your vital tools. Courts cannot attach artisan gear, work machines, or basic household items. Lenders cannot seize running furnaces, lathes, or CNC tools. This rule applies even with a valid court money decree.
Under the MSMED Act, 2006, registered MSMEs deserve timely payments. Claims before MSEFC Gujarat prove genuine commercial distress to banks. The RBI Fair Practices Code sets very strict recovery rules. Agents cannot call before 8 AM or after 7 PM. They cannot make surprise visits or threaten your staff.
4. Bank NPA Accounting in Rajkot
Deep loan haircuts stem from RBI IRACP rules. When a loan is 90 days overdue, it becomes a Non-Performing Asset (NPA). The bank must then set aside profit funds as loan loss provisions:
| NPA Aging Classification | Overdue Horizon (DPD) | Mandatory Bank Provisioning Requirement | Lender Settlement Stance |
|---|---|---|---|
| Special Mention Account (SMA-2) | 61 to 90 Days | Standard asset buffer (General provisioning) | Bank calls and branch visits. No debt cuts yet. |
| Sub-Standard Asset (Unsecured) | Up to 12 Months as NPA | 25% of total unsecured outstanding ledger balance | Bank issues legal notices. Early settlement talks can start. |
| Doubtful Asset (D1 / D2) | 1 to 3 Years as NPA | 100% full provisioning on unsecured exposure | The bank locks 100% funds. Banks approve 40% to 60% principal cuts. |
| Loss Asset / Technical Write-Off | Identified as Uncollectible | 100% full balance sheet write-off against reserves | The bank writes off the debt. You can get deep OTS waivers up to 70% in Lok Adalat. |
Where C_t is expected recovery and r is the discount rate. Deductions cover court costs and locked NPA funds.
Our advocates submit a hardship file with audited records. The bank's Stressed Asset Committee sees clear merit. A fast lump sum gives higher Net Present Value (NPV) than slow court trials.
5. Loan Settlement Roadmap in Rajkot
The diagram below shows the 5-step debt resolution process. It covers hardship audits, legal shielding, court notice defense, OTS negotiations, and credit bureau clearance.
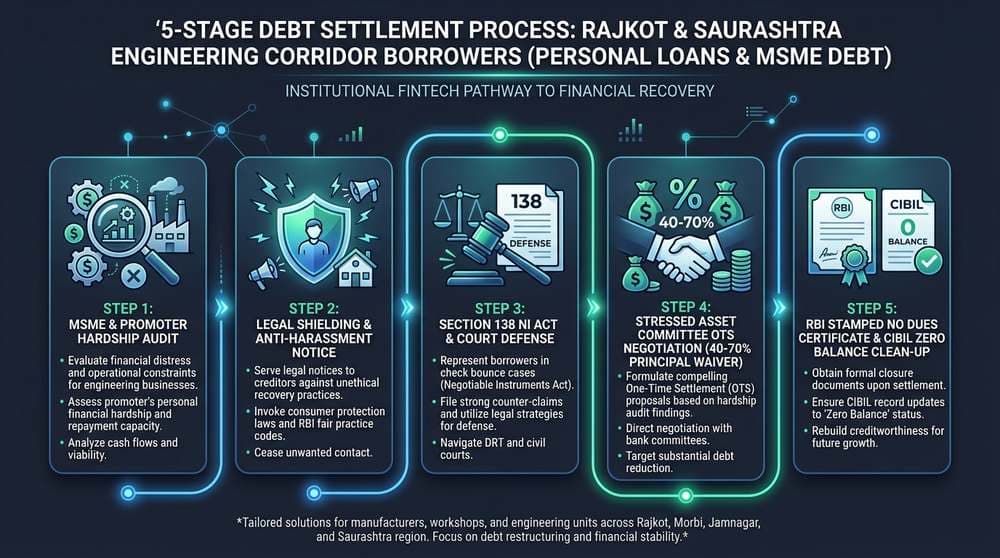
We audit your cash flow. We send cease-and-desist notices under RBI rules. Our advocates handle summons in Rajkot magistrate courts. We negotiate with bank Zonal SARB desks to secure full debt closure with ₹0 credit bureau updates.
6. Judicial Defense in Rajkot Courts
When personal loans default, banks issue legal notices. They file cheque bounce cases under Section 138 of the Negotiable Instruments Act. They also file NACH cases under Section 25 of the PSSA 2007. These cases reach the Chief Judicial Magistrate in Rajkot. You can settle cheque bounce cases at any stage under Section 147. Our advocates appear in court and secure your bail. We challenge notices and record settlements for your full acquittal.
In civil courts, lenders may file summary suits under Order 37 CPC. You get 10 days to appear and apply for Leave to Defend. By showing triable issues, our advocates secure unconditional leave to defend. For claims above ₹20 Lakhs, we use Lok Adalat benches to finalize settlements.
7. Structuring an Institutional OTS in Rajkot
Talks must move to the bank's Zonal Stressed Asset Resolution Branch (SARB). We build a clear hardship file. We include MSME balance sheets, GST drops, and bank statements to prove genuine financial stress.
Our advocates audit your account under RBI Circular RBI/2023-24/53. We remove illegal penal interest and bounce charges. We then offer a realistic compromise (often 30% to 60% of principal) for full loan closure.
Never pay money based on verbal or WhatsApp promises from collection agents. Banks often adjust informal payments against overdue interest without closing the loan. Pay only after you receive an official, signed bank sanction letter.
8. Forensic Audit of OTS Letters in Rajkot
Your settlement letter must come on official bank letterhead. It must show reference numbers, bank seals, and officer signatures. It must include your loan numbers and PAN details. It should list the agreed amount clearly. A specific clause must promise to withdraw all court cases in Rajkot.
Under RBI Circular RBI/2023-24/60, banks must issue your No Dues Certificate within 30 days. They must pay ₹5,000 per day for any delay. Credit bureaus then mark the loan as 'Settled' with ₹0 balance. You can rebuild your CIBIL score to 750+ over 18 to 24 months.
Without a sanction letter and No Dues Certificate, banks can sell old debts to Asset Reconstruction Companies (ARCs). SettleLoans secures complete legal closure so loans never reopen.
9. Debt Resolution Matrix for Rajkot Borrowers
Compare contested court litigation against an advocate-led OTS to decide the best path for your business:
| Strategic Parameter | Unilateral Default / Contested Litigation | Advocate-Led Bank OTS Resolution |
|---|---|---|
| Promoter & Family Dignity | Agent calls, unannounced visits, and family stress. | Full legal protection via RBI notices. |
| Total Financial Liability | High penal interest and rising legal costs. | 40% to 70% debt waiver. Penal interest is waived. |
| Resolution Timeline | 3 to 7 years in civil or DRT courts. | 45 to 90 days for full debt closure. |
| Legal Risk Exposure | Risk of court warrants and money decrees. | Full case compounding, acquittal, and case closure. |
| CIBIL Bureau Status | Active 'Suit Filed' status that drops score below 550. | Updated to 'Settled' with ₹0 dues on your file. |
| Enterprise Asset Safety | Risk of civil court asset execution. | Full legal release of all debt claims. |
| Business Focus & Peace | Heavy stress and disrupted factory work. | Permanent closure, No Dues Certificate, and peace of mind. |
10. SettleLoans Legal Defense in Rajkot
SettleLoans provides full legal and financial support for foundry owners and auto part makers across Rajkot. Our senior advocates stop collection harassment. We defend Section 138 NI Act notices in court. We also win 40% to 70% bank OTS settlements with official No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Rajkot
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Rajkot can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Race Course Road, Sadar, Rajkot, Gujarat - 360001
Jurisdiction: Benches handle Section 138 trials and summary recovery suits for Saurashtra-based engineering and diesel engine MSMEs.
Address: Nyaya Mandir, District Court Building, Rajkot - 360001
Lok Adalat Conciliation: Administers pre-litigation settlement conferences through Gujarat SLSA, delivering final civil court decrees on loan waivers.
11. FAQs: Debt Settlement in Rajkot
Clear answers to key questions about personal loan settlement, MSME debt relief, court defense, and borrower rights in Rajkot.
Why do foundry owners and MSME promoters in Rajkot face personal loan debt traps?
Foundries and machine units in Rajkot, Jamnagar, and Bhavnagar face 90 to 180 day payment delays from auto OEMs. Raw material prices also fluctuate. When bank limits run out, promoters take high-interest personal loans to pay wages and bills. This leads to heavy debt compounding.
How do loan settlement services in Rajkot halt recovery agent harassment?
Advocates send cease-and-desist notices under RBI Fair Practices Code (RBI/2022-23/108). This forces lenders to talk only through legal counsel. It bans factory visits, calls outside 8 AM to 7 PM, and pressure on staff or family.
What is the procedure for handling Section 138 NI Act summons in Rajkot courts?
When cheques bounce, banks file cases under Section 138 NI Act before the Chief Judicial Magistrate in Rajkot. Our advocates appear in court and secure bail. We challenge notice flaws. We then settle the case under Section 147 NI Act through an agreed OTS for full acquittal.
Can banks seize factory machinery or residential property for unsecured personal loans?
No. Unsecured personal loans have no mortgage or asset charge. Lenders have zero power under the SARFAESI Act, 2002 to seize property without a civil court order. Also, Section 60(1)(b) & (c) CPC protects your work tools, factory machinery, and basic home from attachment.
What percentage of debt waiver can Rajkot borrowers secure in an OTS?
Rajkot borrowers often get 40% to 70% principal waivers on unsecured personal and MSME loans. Banks also waive 100% of penal interest, late fees, and bounce charges under RBI compromise guidelines.
How do banks evaluate Rajkot MSME debt under the Net Present Value (NPV) formula?
When a loan crosses 90 days, banks make heavy provisions under RBI IRACP rules. Committees use an NPV formula. They see that quick cash beats 3 to 5 years of slow court trials.
Can Rajkot personal and business debts be resolved through Lok Adalat?
Yes. DLSA Rajkot holds regular National Lok Adalats. Banks bring pre-approved settlement mandates. Awards made in Lok Adalat act as final civil court decrees under the Legal Services Authorities Act, 1987.
What is the difference between bank OTS and contested proceedings at DRT Ahmedabad?
For claims above ₹20 Lakhs, cases before DRT Ahmedabad take years of legal costs and uncertainty. In contrast, an advocate-led OTS settles the entire debt in 45 to 90 days without prolonged trial.
What precautions are vital before remitting settlement funds to lenders?
Never pay based on phone calls or WhatsApp chats. Always demand an official OTS Sanction Letter on bank letterhead. Check the reference number, settlement amount, and debt closure clause. Pay only into your loan account via RTGS or NEFT.
What is the timeline for receiving the No Dues Certificate and CIBIL score restoration?
Under RBI Circular RBI/2023-24/60, lenders must deliver your No Dues Certificate within 30 days. If they delay, they must pay ₹5,000 per day. Credit bureaus then mark the account as 'Settled' with ₹0 balance. You can rebuild your score to 750+ within 18 to 24 months.