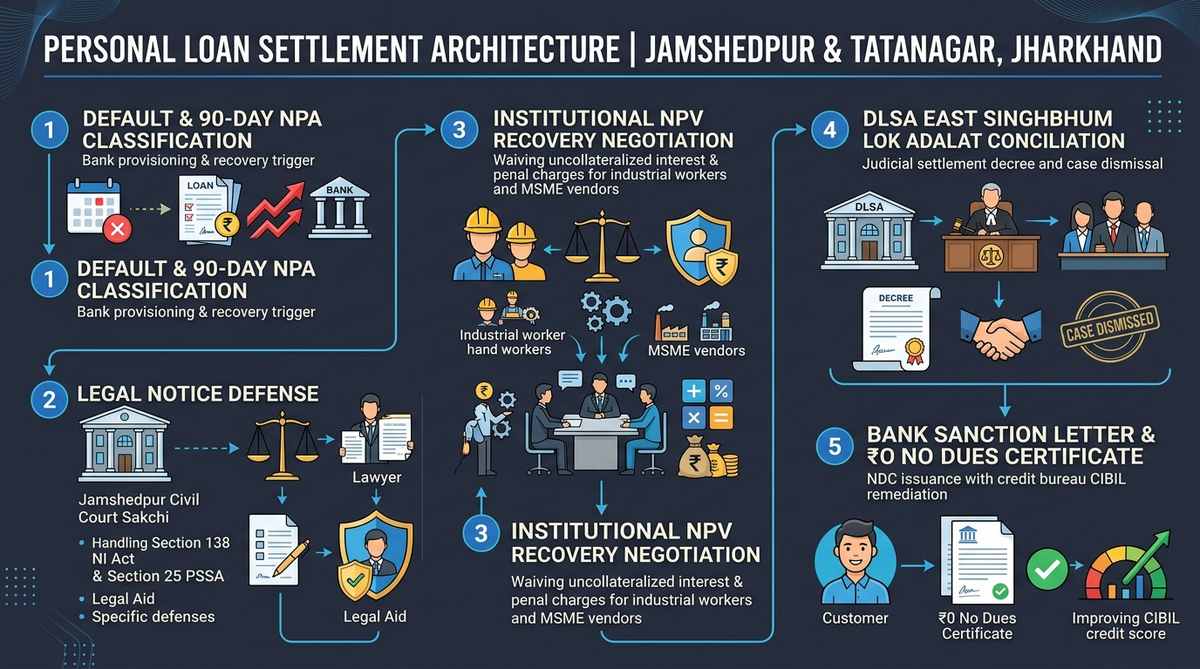
- Advocate-Led Zonal Talks: Industrial workers and MSME vendors settle directly with bank zonal recovery committees, bypassing aggressive collection agencies.
- Salary & Wage Protections: Tata Steel, Tata Motors, and ancillary employees enjoy statutory safeguards under Section 60 CPC against unlawful workplace salary attachments.
- Adityapur MSME Relief: Auto-component manufacturers utilize balance-sheet forensics and OEM payment disruption records to achieve 40% to 65% debt waivers.
- Sakchi Court & Lok Adalat Defense: Summons under Section 138 NI Act and Section 25 PSSA are resolved through binding settlement decrees before DLSA East Singhbhum Lok Adalat.
- Guaranteed ₹0 NDC Closure: Every negotiated settlement guarantees a bank sanction letter and an RBI-mandated zero-balance No Dues Certificate within 30 days.
Managing Personal Debt Defaults in Jamshedpur & Tatanagar
Jamshedpur serves as the industrial core of Jharkhand, anchored by integrated steel production, commercial vehicle manufacturing, and extensive auto-ancillary clusters across Adityapur. While major manufacturing plants provide steady employment, local workers and vendor units remain vulnerable to cyclical industry slowdowns, automotive production freezes, and delayed supply-chain payments. During economic contractions, retail borrowing frequently surges among engineers, technicians, and local contractors to cover family emergencies and operational deficits.
When automotive plant shifts reduce or health crises strike, servicing high-interest personal loans and credit cards becomes unsustainable. Unsecured debt interest compounds rapidly, turning manageable dues into severe financial strain. Recovery agencies often deploy aggressive calls and home visits across Sakchi, Kadma, Bistupur, and Telco. Legally, loan default is purely a civil contractual dispute governed by the Indian Contract Act, 1872, rather than a criminal offense.
Under Reserve Bank of India directions, commercial banks and NBFCs must maintain formal compromise mechanisms for financially distressed borrowers. Retaining an experienced loan settlement lawyer in Jamshedpur allows borrowers to stop harassment, assert legal protections, and route discussions through counsel. Structured compromise settlements eliminate excessive penal interest and achieve realistic debt closures.
Judicial Jurisdiction: Sakchi Courts to DRT Ranchi
Understanding the judicial hierarchy of East Singhbhum is essential for resolving debt disputes. In Jamshedpur, bank litigation begins before the District and Sessions Court at Sakchi. Lenders frequently file complaints under Section 138 of the Negotiable Instruments Act for bounced cheques, or Section 25 of the Payment and Settlement Systems Act for failed electronic mandates. These matters are heard by Judicial Magistrate First Class benches at Sakchi Civil Court.
Summary civil suits under Order 37 of the Code of Civil Procedure are also instituted in Sakchi for debt recovery. However, when unpaid debt exceeds twenty lakh rupees, legal jurisdiction transfers entirely to the Debts Recovery Tribunal (DRT) in Ranchi under the Recovery of Debts and Bankruptcy Act. Constitutional writ petitions and Section 482 CrPC quashing petitions against unlawful harassment are heard by the High Court of Jharkhand at Ranchi.
| Jurisdiction Authority | Court Forum | Case Classification | Governing Statute | Advocate Defense Strategy |
|---|---|---|---|---|
| East Singhbhum District | Sakchi Civil Court, Jamshedpur | Sec 138 NI Act, Sec 25 PSSA, Order 37 CPC | Negotiable Instruments Act, PSSA 2007, CPC 1908 | Timely reply in 15 days, secure court bail, initiate DLSA conciliation. |
| Adityapur Industrial Area | Seraikela-Kharsawan District Courts | Commercial vendor disputes, Summary debt suits | Commercial Courts Act, 2015, Indian Contract Act | Submit corporate books, establish manufacturing delay, structure OTS. |
| Debts Recovery Tribunal | DRT Ranchi (Kanke Road) | Original Applications exceeding twenty lakh rupees | RDB Act 1993, SARFAESI Act 2002 | Challenge inflated penal claims, contest territoriality, negotiate compromise. |
| High Court of Jharkhand | Doranda Bench, Ranchi | Writ Petitions, Section 482 CrPC Quashing | Constitution of India, CrPC 1973 | Enforce fundamental rights against illegal coercion and unlawful police summons. |
| Lok Adalat Conciliation | DLSA Complex, Sakchi Court | Pre-litigation and pending bank recovery matters | Legal Services Authorities Act, 1987 | Execute binding civil decree with mutual waiver and zero future liability. |
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Bank NPA Accounting & Compromise Valuation in Jamshedpur
Commercial banks across Jamshedpur adhere to uniform Prudential Norms established by the Reserve Bank of India. When an unsecured personal loan or credit card remains unpaid for ninety consecutive days, it is classified as a Non-Performing Asset (NPA). The bank must halt interest income recognition and reverse accrued uncollected revenue from its balance sheet.
As bad debts age from Substandard to Doubtful categories, RBI mandates compel lenders to lock away regulatory capital reserves between 15% and 100%. Carrying delinquent unsecured assets depresses the lender Capital Adequacy Ratio (CAR). Consequently, bank recovery committees evaluate settlement proposals using an institutional Net Present Value (NPV) recovery formula:
Where C_t represents projected cash recovery, r is the institutional discount rate, and deductions account for multi-year court delays and tied-up capital provisioning reserves.
Litigating unsecured loans through local civil courts or DRT Ranchi routinely consumes four to seven years in legal fees and administrative overhead. Because unsecured loans carry no underlying physical assets to auction, banks recognize that immediate cash recovery holds greater net value than prolonged court disputes. This economic reality enables legal advocates to secure 40% to 65% debt waivers for qualifying borrowers.
Halting Harassment Under RBI Directives in Jamshedpur
Salaried workers and local traders in Jamshedpur often encounter severe pressure from third-party recovery agents. Unlawful collection practices include late-night calls, messages to personal contacts, and unannounced visits to residential quarters in Kadma, Bistupur, Sonari, or Telco. These actions violate fundamental borrower rights and statutory banking standards.
In ICICI Bank Ltd. v. Prakash Kaur (2007), the Supreme Court ruled that banks cannot use coercive tactics or recovery musclemen to collect debts. Furthermore, RBI Fair Practices Codes forbid recovery communications before 8:00 AM or after 7:00 PM, repetitive calls on the same day, or contact with workplace managers and relatives.
SettleLoans issues formal legal cease-and-desist notices to bank nodal authorities. This directs lenders to route all inquiries exclusively through appointed legal counsel. If collection agencies persist in unlawful conduct, our advocates file formal complaints with DLSA East Singhbhum, Sakchi Cyber Crime Cell, and the RBI Banking Ombudsman.
Personal Loan Settlement & Legal Resolution Process in Jamshedpur
Tailored Settlement Solutions for Steel & MSME Sectors
Borrowers across Jamshedpur and the industrial belt face specific financial hurdles that demand tailored legal negotiation strategies:
Technical and administrative personnel across Tata Steel, Tata Motors, Tinplate, and engineering vendors frequently utilize personal credit during peak operating cycles. When overtime hours drop or medical crises arise, loan servicing becomes strained. Recovery agents sometimes threaten workplace salary attachment. Under Section 60(1)(i) of the Code of Civil Procedure, basic salaries are protected from attachment, while Provident Fund and gratuity are entirely immune under EPF legislation. Our advocates protect employee dignity, ensure strict confidentiality, and negotiate affordable compromise settlements.
Industrial units across Adityapur supply vital automotive and engineering components. Delayed client receivables and production fluctuations can strain commercial liquidity, pushing promoters to utilize personal credit lines for working expenses. SettleLoans assists MSME owners by analyzing audited financials, presenting verifiable supply-chain disruptions to bank committees, and securing 45% to 65% principal waivers that relieve business promoters of personal liability.
Early-career engineers and industrial technicians in urban Jamshedpur often experience debt traps from digital lending applications and multiple credit cards. Hidden fees and rapid interest accumulation quickly deplete monthly incomes. SettleLoans assists young professionals by consolidating multi-lender defaults, challenging unfair digital charges under RBI Digital Lending Directives, and executing structured one-time settlements that provide a viable path toward long-term financial recovery.
Defending Sec 138, Sec 25 PSSA & Lok Adalat in Sakchi
When loan defaults cross 120 days, lenders may initiate court proceedings in East Singhbhum. These include Section 138 Negotiable Instruments Act complaints for dishonored cheques and Section 25 Payment and Settlement Systems Act cases for bounced NACH mandates before Judicial Magistrates at Sakchi Civil Court. These matters remain civil debt disputes in substance.
Borrowers receiving statutory legal notices have fifteen days to submit an authoritative legal reply. Counsel refutes inflated penalty claims and documents genuine hardship. When court summons appear, advocates secure bail and prevent coercive steps. The matter is referred to the National Lok Adalat organized by DLSA East Singhbhum. Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat award functions as a final civil decree, requiring banks to withdraw all complaints.
OTS Sanction Letter Forensics & Zero-Balance NDC Mandate
Settling a loan without legal verification carries serious financial risks. Unscrupulous recovery agents sometimes issue fake compromise letters on forged letterheads, taking payments that banks later dispute. SettleLoans verifies every settlement document before advising client disbursement.
Our advocates ensure the settlement letter originates from the bank official loan portal, displays valid reference numbers, and bears the authorized signature of a Chief Manager or Zonal Head. The letter must state that the agreed sum constitutes full settlement and that all legal cases will be dismissed. Payments are made directly to the loan account via RTGS or NEFT. Under RBI directives, lenders must issue the zero-balance No Dues Certificate within thirty days, subject to a ₹5,000 daily penalty for non-compliance.
Post-Settlement CIBIL Trajectory & Score Rehabilitation
Settling an unmanageable loan causes the lender to report the account as Settled with zero balance. While this initially lowers the credit score by 75 to 150 points, it halts monthly default reporting and Days Past Due (DPD) accumulation that damages credit profiles.
Once the zero-balance status is recorded, borrowers can systematically restore their creditworthiness. By obtaining a secured credit card backed by a fixed deposit, maintaining utilization below 25%, and clearing monthly bills promptly, borrowers in Jamshedpur can rebuild their CIBIL score past 750 within eighteen to twenty-four months.
| Financial Metric | Active Unresolved Default | Lawyer-Led OTS Settlement | Post-Settlement Credit Rehabilitation |
|---|---|---|---|
| Credit Bureau Status | Compounding delinquency, written-off tag, score sub-550 | Marked Settled with ₹0 balance, delinquency halted | Rebuilt prime score above 750 within 18–24 months |
| Legal & Court Exposure | Active Sakchi summons, Section 138 & 25 PSSA warrants | Cases withdrawn under binding Lok Adalat decree | Absolute legal immunity, zero court appearances |
| Workplace & Dignity Risk | Harassment calls, workplace queries, threats to HR | Completely terminated via legal cease-and-desist | Complete privacy and peace of mind restored |
| Total Financial Liability | Escalating penal interest compounding monthly | 40% to 65% debt reduction, affordable payment terms | Zero remaining liability, authentic ₹0 No Dues Certificate |
| CIBIL Score Path | Continuous downward spiral below 550 Points | Stabilizes immediately upon zero balance issuance | Recovers past 750 within 18 to 24 months |
Why Jamshedpur Borrowers Choose SettleLoans Legal Advocates
Resolving defaulted personal debt in Jamshedpur, Tatanagar, and Adityapur requires seasoned legal expertise and firm advocacy. SettleLoans combines local courtroom experience in East Singhbhum with deep mastery of RBI banking regulations. Our advocates protect employment standing, resolve court summons, stop recovery harassment, and secure maximum debt waivers with authentic No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
Frequently Asked Questions: Loan Settlement in Jamshedpur
How does personal loan settlement work for industrial workers in Jamshedpur?
Personal loan settlement is an RBI-approved compromise process. When a personal loan enters NPA, lawyers present your verified financial distress to the bank zonal recovery committee. They eliminate uncollateralized penal charges and secure a 40% to 65% debt waiver, supported by an official sanction letter and No Dues Certificate.
Can banks attach the salary of Tata Steel or Tata Motors workers in Jamshedpur?
No. Banks cannot attach salaries without a civil decree. Section 60(1)(i) CPC protects the majority of employee salary from attachment. Furthermore, statutory Provident Fund and gratuity accumulations are completely immune under the EPF Act. Loan default is a civil contract matter, not departmental misconduct.
What protections exist for Adityapur industrial vendors facing business loan default?
MSME owners are protected under RBI debt restructuring norms. By submitting audited accounts, GST returns, and OEM supply-chain disruption records, business promoters prove genuine hardship. Our lawyers negotiate significant debt waivers while safeguarding machinery and personal assets from unlawful recovery action.
Which local courts in East Singhbhum handle personal loan disputes and Section 138 cases?
Sakchi Civil Court in Jamshedpur adjudicates Section 138 Negotiable Instruments Act cheque complaints and Section 25 PSSA electronic mandate cases before Judicial Magistrates. Civil summary suits under Order 37 CPC are heard by local Civil Judges.
When is a defaulted loan case moved to DRT Ranchi instead of Sakchi Civil Court?
Under the Recovery of Debts and Bankruptcy Act, banks can only initiate proceedings before the Debts Recovery Tribunal when total debt claims exceed twenty lakh rupees. For debts above this limit anywhere in East Singhbhum, jurisdiction lies exclusively with DRT Ranchi.
How do debt settlement advocates in Jamshedpur stop recovery agent harassment?
Lawyers issue formal legal cease-and-desist notices to bank nodal authorities. This directs lenders to route all communications through counsel. If agents violate RBI rules by calling outside permitted hours (8 AM to 7 PM), advocates file complaints with DLSA, Cyber Police, and the RBI Ombudsman.
What debt waiver percentage can borrowers in Jamshedpur realistically negotiate?
Borrowers in Jamshedpur typically achieve a 40% to 65% waiver on personal loans and credit cards. Legal advocates eliminate unfair late fees, annual charges, and penal interest. The final settlement depends on default vintage and verified financial hardship.
Can personal loan defaults be settled during DLSA East Singhbhum Lok Adalat?
Yes. National Lok Adalats organized by DLSA East Singhbhum at Sakchi Court provide an ideal settlement platform. A Lok Adalat settlement award acts as a final, non-appealable civil court decree under Section 21 of the Legal Services Authorities Act, requiring lenders to withdraw all court cases.
How do borrowers verify an OTS sanction letter before disbursing settlement funds?
An authentic One-Time Settlement letter must be issued on bank letterhead, bearing the signature and employee code of an authorized officer. It must confirm full account closure upon payment. All settlement payments must be made directly to the loan account via RTGS or NEFT.
How does loan settlement affect CIBIL scores and how can industrial workers rebuild credit?
Settling a loan reports the account as Settled with a zero balance. While it causes an initial credit score drop of 75 to 150 points, it halts monthly delinquency reporting. Borrowers can rebuild their score above 750 within 18 to 24 months using secured credit cards.
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements (DOR.STR.REC.20/21.04.048/2023-24).
- High Court of Jharkhand at Ranchi: Official Case Status, Rulings and Judicial Directives.
- Jharkhand State Legal Services Authority (JHALSA): National Lok Adalat Settlement Guidelines.
- Debts Recovery Tribunal (DRT Ranchi): Territorial Jurisdiction for Jharkhand Debts exceeding ₹20 Lakhs.
- Reserve Bank - Integrated Ombudsman Scheme (CMS Portal): Online Complaint System for Banking Grievances.