- Civil Dispute Rights: Unsecured loan default is a civil matter under the Indian Contract Act, 1872. Banks cannot file police FIRs or make arrests.
- SARB Notice Defense: We handle bank SARB notices. We defend Section 138 NI Act and Section 25 PSSA cases. We turn them into OTS terms.
- DLSA Khordha Lok Adalat: Sessions at Nyaya Seva Sadan in Bhubaneswar grant 40% to 60% principal waivers. The decree is final.
- Waiver of Penal Charges: Under RBI rules, banks waive 100% of penal fees and late fines. They also waive e-NACH bounce charges.
- Guaranteed ₹0 NDC: Under RBI Circular RBI/2023-24/60, banks must deliver your NDC in 30 days. Daily fines of ₹5,000 apply for delays.
Debt Landscape & Realities in Bhubaneswar
Bhubaneswar and Cuttack form the business hub of Odisha. Many work in tech firms in Patia. Others run units in Mancheswar. Sudden income cuts cause real stress. IT staff face project delays. Mining contractors in Keonjhar face slow client payments. Credit cards and personal loans quickly become hard to pay.
Default on a loan is a civil matter under the Indian Contract Act, 1872. Borrowers have clear rights under RBI rules and Orissa High Court rulings. You can stop agent harassment. You can challenge unfair charges and negotiate a One-Time Settlement (OTS).
Statutory Civil Protections & RBI Anti-Harassment Mandates
When EMIs bounce, banks assign files to collection agencies. However, the RBI sets strict rules on collection conduct. Agents may only call between 8:00 AM and 7:00 PM. Calling coworkers, HR teams in Infocity, or non-guarantor relatives is illegal. Agents cannot use abusive words or make surprise home visits. They must carry official bank ID cards.
Personal loan default carries no criminal fines. Police in Bhubaneswar and Cuttack cannot file FIRs or detain borrowers for debt. If agencies cross legal lines, a settlement lawyer issues formal cease-and-desist notices to the bank. We can also file complaints with the RBI Ombudsman.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Delinquency Lifecycle & NPA Stages in Bhubaneswar
Overdue loans follow RBI asset classification rules (IRACP) and Ind AS 109. After 90 days past due, the bank marks the loan as a Non-Performing Asset (NPA). The bank stops adding interest to its books. It also sets aside capital reserves to cover the loss. The bank now focuses on recovering its core capital.
| default Stage. | Days Past Due (DPD). | Bank Collection Actions in Odisha. | Legal Exposure in Bhubaneswar. | Realistic OTS Haircut Range. |
|---|---|---|---|---|
| SMA-0 (Initial Default). | 1 – 30 Days. | Automated reminder SMS. Payment reminder calls. | No court cases. Early credit bureau reporting. | Low. Bank asks for full EMI payment. |
| SMA-1 (Mid default). | 31 – 60 Days. | Calls from bank agents. Loan recall warning letters. | Warning letters. Credit score drops 40–70 points. | Low. Loan restructuring may be discussed. |
| SMA-2 (Pre-NPA Stage). | 61 – 90 Days. | Home visits by agents. Final loan recall warnings. | Section 138 NI Act or Section 25 PSSA legal notices. | Medium. Discussions on fee waivers can start. |
| NPA (Substandard Asset). | 91 – 180 Days. | Case moved to Zonal SARB in Bhubaneswar. | JMFC Court summons under Section 25 PSSA. | High (35%–50% Principal Haircut). |
| Doubtful / Loss Asset. | 181 – 365+ Days. | Full loan loss booked. Technical write-off review. | Civil suits and National Lok Adalat hearings. | Maximum (50%–60% Principal Haircut). |
When a loan turns into a Doubtful Asset past 180 days, the bank books big losses. A lump-sum payment brings instant cash. This leads bank committees to approve 40% to 60% waivers.
NPV Valuation Logic & Haircuts in Bhubaneswar
Banks review settlement proposals using RBI Net Present Value (NPV) rules. Unsecured loans carry no collateral. Banks compare settlement cash against slow court lawsuits. Order 37 CPC suits take 3 to 5 years in court. They involve high legal costs and locked bad loan funds. An early settlement gives banks better net cash value.
Here, C_t is recovered cash. The letter r is discount rate. Deductions cover court costs and locked capital.
Realistic Settlement Haircut Slabs by Product & Aging in Bhubaneswar
| Credit Facility Category. | default Aging. | Penal &. Bounce Waiver. | Principal Haircut Range. | Target Settlement Offer. |
|---|---|---|---|---|
| Unsecured Personal Loan (IT / Salaried). | 90 – 180 Days (NPA). | 100% Full Waiver. | 30% – 45% Principal Waiver. | Pay 45%–55% of Core Balance. |
| Unsecured Personal Loan (IT / Salaried). | 181 – 365+ Days (Doubtful). | 100% Full Waiver. | 45% – 60% Principal Waiver. | Pay 35%–40% of Core Balance. |
| Unsecured Business Facility (Contractors). | 90 – 180 Days (NPA). | 100% Full Waiver. | 30% – 45% Principal Waiver. | Pay 45%–55% of Drawn Funds. |
| Credit Card Receivables &. Digital Apps. | 180+ Days (Written Off). | 100% All Penal Charges. | 50% – 65% Principal Waiver. | Pay 30%–35% of Total Dues. |
Bhubaneswar Loan Settlement & Legal Defense Roadmap
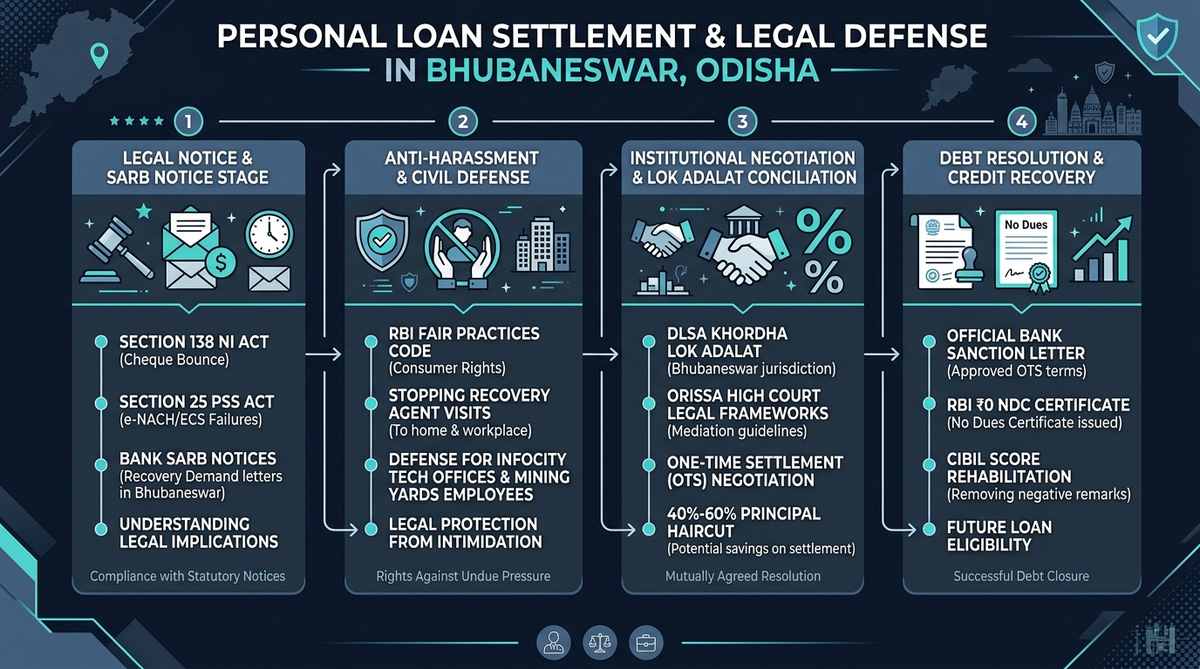
Defending SARB Demands & Sec 138 in Bhubaneswar
When defaults pass 90 days, banks transfer cases to Stressed Assets Recovery Branches (SARB) in Bhubaneswar. These include SBI SARB in Ashok Nagar or PNB in Saheed Nagar. Lenders send 15-day demand notices. They file under Section 138 of the NI Act for cheques. They file under Section 25 of the PSSA for failed e-mandates.
A demand notice is not an arrest warrant. An advocate files a formal legal reply within 15 days. This establishes financial hardship and stops unfair fines. Also, one-sided arbitrator appointments violate Supreme Court rulings (Perkins Eastman and TRF Ltd.). Challenging arbitrator jurisdiction under Section 12 halts ex-parte orders and leads banks to mutual OTS settlements.
Settling via National Lok Adalat in Bhubaneswar
The DLSA Khordha hosts quarterly National Lok Adalats at Nyaya Seva Sadan in Bhubaneswar Court. DLSA Cuttack also offers this conciliation process. Bank officers attend with authority. They grant 40% to 60% principal waivers. They also waive 100% of penal fees.
Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat Award is final. It acts as a Civil Court Decree. It cannot be appealed. This gives borrowers complete immunity from future claims and dismisses all Section 138 and Section 25 cases.
Step-by-Step Settlement Blueprint in Bhubaneswar
Achieving a binding One-Time Settlement requires a clear legal strategy across six phases:
1Comprehensive Financial Hardship Dossier Compilation
We gather proof of hardship. For example, job loss letters, medical bills, or mining contract payment delays. This proves the default was not willful.
2Suspending e-NACH Mandates & Serving Anti-Harassment Cease-and-Desist Notices
We help you cancel e-NACH mandates under NPCI rules. We also issue legal notices under RBI rules to stop agent visits.
3Submitting Institutional OTS Hardship Petition to Bank SARB Desks
Our lawyers submit a compromise petition under RBI rules directly to the bank Zonal SARB in Bhubaneswar. We propose realistic terms.
4Managing Counter-Demands & Securing Credit Committee Approval
When lenders make counter-offers, we show your true payment capacity. We use NPV math to secure Credit Committee approval for 40% to 60% debt waivers.
5Forensic Audit of the OTS Sanction Letter
We audit the OTS sanction letter on bank letterhead. We verify account numbers, payment schedules. And legal case withdrawal clauses.
6Direct Account Remittance & Enforcing Statutory ₹0 NDC Delivery
You pay the settlement amount directly into your loan account via RTGS/NEFT. Under RBI Circular RBI/2023-24/60, the bank must issue your NDC within 30 days.
Sanction Letter Audit & NDC in Bhubaneswar
Borrowers in Bhubaneswar must avoid fake settlement letters from agents. Every real sanction letter comes on bank letterhead with reference numbers, official seals. And debt discharge clauses.
Settling a loan marks your credit bureau record as 'Settled&apos. with a ₹0 balance. This causes a short-term drop in score. But monthly default marks stop completely. You can rebuild your CIBIL score above 750 in 18 to 24 months. Use a secured credit card and pay on time.
Comparative Resolution Matrix in Bhubaneswar
Reviewing legal debt resolution options helps borrowers in Bhubaneswar and Cuttack choose the best path:
| Resolution Pathway. | Legal Mechanism. | Haircut Potential. | Resolution Timeline. | Judicial Finality. |
|---|---|---|---|---|
| Direct Bank OTS. | Direct settlement under RBI rules. | 40% – 60% Debt Haircut | 15 to 30 Days. | Signed contract with ₹0 NDC. |
| National Lok Adalat. | Lok Adalat decree via DLSA bench. | 45% – 60% Debt Haircut | 1 day session. | Civil Court Decree (Final). |
| Arbitration Defense. | Challenge arbitrator under Section 12. | Converts to OTS. | 3 to 9 Months. | Settled or challenged under Section 34. |
| Section 138 / 25 Defense. | Defend Section 138 in JMFC court. | 35% – 50% Debt Haircut | 2 to 6 Months. | Court case withdrawn and closed. |
Why Borrowers in Bhubaneswar Choose SettleLoans
Disputes and court notices need skilled legal support. SettleLoans helps workers and business owners across Bhubaneswar and Cuttack. We stop harassment. We defend notices in local courts. We also appear at DLSA Lok Adalats to secure maximum debt waivers.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: Personal Loan Settlement in Bhubaneswar
Why should borrowers in Bhubaneswar hire a debt settlement lawyer instead of dealing with recovery agents directly?
Unsecured loan default is a civil contract dispute. Recovery agents have no legal power to waive debt. A settlement lawyer protects you from harassment. They answer bank SARB notices and defend Section 138 and Section 25 PSSA court summons. They negotiate authentic 40% to 60% OTS debt waivers directly with bank credit committees.
How does Bhubaneswar's commercial landscape impact loan settlement negotiations for IT engineers and mining contractors?
Lenders know that IT project delays in Infocity and mining cash crunches in Keonjhar cause real hardship. Documenting these income losses helps bank Stressed Assets Committees approve large debt write-offs.
What legal protections exist against recovery agents visiting Infocity offices or homes in Bhubaneswar?
Under RBI rules, recovery agents may only call between 8:00 AM and 7:00 PM. Visiting workplaces in Infocity, calling employers, or harassing family members is illegal. Borrowers can report violations to the RBI Ombudsman.
Can a bank file a police FIR or arrest a borrower for defaulting on a personal loan in Odisha?
No. Personal loan default is a civil matter under the Indian Contract Act, 1872. Police in Odisha cannot file FIRs or arrest borrowers for unpaid loans. Section 138 NI Act and Section 25 PSSA cases are bailable matters handled in magistrate courts.
What is a bank Stressed Assets Recovery Branch (SARB) notice and how should borrowers in Bhubaneswar respond?
After 90 days of default, banks transfer accounts to centralized SARB units like Ashok Nagar in Bhubaneswar. A SARB notice demands loan recall. Filing a formal legal reply proves real hardship and starts compromise OTS talks.
How does National Lok Adalat at DLSA Khordha resolve personal loan disputes in Bhubaneswar?
DLSA Khordha organizes quarterly Lok Adalats at Nyaya Seva Sadan in Bhubaneswar Court. An agreed settlement award holds the force of a final Civil Court Decree. It permanently closes the debt and ends all court cases.
What percentage of loan waiver can borrowers in Bhubaneswar realistically achieve through an OTS?
For loans overdue past 90 days, you can negotiate a 40% to 60% principal waiver. Banks also waive 100% of penal interest, late fees, and bounce charges.
How should borrowers handle Section 138 NI Act or Section 25 PSSA court summons in Bhubaneswar?
Consult a settlement advocate immediately upon receiving summons from the SDJM Court Bhubaneswar. Your lawyer appears in court. They dispute unfair fees and move the case to Lok Adalat or mutual OTS.
How does loan settlement affect CIBIL scores and how long does credit rehabilitation take in Odisha?
Your loan status changes to 'Settled' with a ₹0 balance. Your score drops at first. Using a fixed-deposit credit card can restore your score above 750 in 18 to 24 months.
What is the statutory deadline for banks to issue the No Dues Certificate (NDC) post-settlement in Odisha?
Under RBI Circular RBI/2023-24/60, banks must deliver an NDC within 30 days of payment. Any delay requires the bank to pay ₹5,000 per day in statutory penalties.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- High Court of Orissa (Cuttack): Judicial Directives on Civil Debt Recovery, Section 138 NI Act Defense &. Lok Adalat Conciliation
- Odisha State Legal Services Authority (OSLSA): DLSA Khordha (Bhubaneswar Nyaya Seva Sadan) &. DLSA Cuttack Lok Adalat Guidelines
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online CMS Portal for Bhubaneswar Regional Office &. Recovery Agent Harassment Redressal
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987. Pre-Litigation Lok Adalat Conciliation Mandates