1. The Reality of Personal Loan Default in India:
Jab ek borrower personal loan ki regular Equated Monthly Installments (EMIs) pay karne me asamarth ho jata hai, to wo aksar collection agents ki calling, ghar par physical visits aur legal threats ke chalte severe mental trauma aur confusion ka shikar ho jata hai. Bharat me HDFC Bank, ICICI Bank, State Bank of India, Axis Bank, Kotak Mahindra Bank ya kisi leading NBFC jaise Bajaj Finance, Tata Capital ya Aditya Birla Capital se liya gaya personal loan ek unsecured credit facility hota hai. Iska matlab hai ki bank ke paas loan sanction karte waqt koi collateral security, property mortgage ya gold pledge nahi hota.
Jab loan default hota hai, to lending institution ek structured recovery protocol follow karta hai. Shuruat ke 30 se 60 dino me automated SMS reminders, interactive voice response (IVR) calls aur call-center level follow-ups kiye jaate hain. Yadi 60 din tak payment nahi aati, to bank account ko third-party collection agencies (Direct Recovery Agents ya DRAs) ko assign kar deta hai. Ye recovery agents commissions par kaam karte hain, isliye wo aksar illegal psychological tactics, relatives ko call karna ya police complaint ki jhooti dhamkiyan dekar borrower par pressure banate hain.
Ek borrower ke roop me aapke liye ye samajhna behad zaroori hai ki financial insolvency ya genuine majboori (jaise business loss, job loss, ya severe medical emergency) ke kaaran loan default karna koi criminal crime nahi hai. Indian law ke mutabiq ye purely ek civil contract breach hai jo Indian Contract Act, 1872 ke purview me aata hai. Bank ka antim maqsad borrower ko jail bhejna nahi (jo ki legally possible bhi nahi hai), balki apne balance sheet se non-performing assets ko clear karke maximum possible recovery karna hota hai. Yahi institutional reality One-Time Settlement (OTS) ke legal mechanism ka foundation banati hai.
2. Delinquency Lifecycle, DPD Timelines & RBI NPA Provisioning Dynamics
Personal loan me best settlement discount hasil karne ke liye bank ki balance sheet accounting aur Reserve Bank of India (RBI) ke Prudential Framework on Resolution of Stressed Assets ko samajhna zaroori hai. Bank har defaulted loan account ko Days Past Due (DPD) ke adhar par alag-alag delinquency buckets me classify karta hai:
1. SMA-0 (1 se 30 Din Overdue): Early delinquency stage jisme bank regular reminder notices bhejta hai aur late payment fees add karta hai.
2. SMA-1 (31 se 60 Din Overdue): Pre-stress stage jisme collection agents field visits aur regular phone calls shuru karte hain.
3. SMA-2 (61 se 90 Din Overdue): Critical alert stage jisme bank borrower ko restructuring ya tenure extension offer kar sakta hai taaki account NPA banne se bach sake.
4. Non-Performing Asset (NPA) (91+ Din Overdue): RBI Master Circular on Income Recognition, Asset Classification and Provisioning (IRACP) ke mutabiq, jaise hi loan 90 days continuous overdue cross karta hai, account standard asset se Substandard NPA me convert ho jata hai.
Jab koi loan NPA banta hai, to RBI mandates ke tehat bank ko apne operating profits me se ek specific percentage Provisioning Reserve ke roop me block karna padta hai. Unsecured loans ke case me Substandard stage par 15%, Doubtful D1 stage (12 se 24 mahine) par 25% se 40%, aur Doubtful D2/Loss Asset stage par 100% tak provisioning karni padti hai. Ye locked capital bank ke profit margins aur lending capacity ko severely affect karta hai. Yahi kaaran hai ki jaise-jaise account purana hota hai (120 se 180 din ke baad), bank ka Zonal Credit Committee ek practical One-Time Settlement (OTS) approve karke account close karne ke liye zyada flexible ho jata hai.
| Delinquency Category | Overdue Period (DPD) | Bank Regulatory Provisioning | Settlement Haircut Potential |
|---|---|---|---|
| SMA-0 / SMA-1 | 1 – 60 Days | Standard Provisioning (0.4%) | Zero Haircut; Only Penal Fee Waiver Possible |
| SMA-2 | 61 – 90 Days | High Risk Pre-NPA Warning | Tenure Restructuring or Part Penal Waiver |
| Substandard NPA | 91 – 180 Days | 15% Mandatory Capital Provision | 25% – 40% Principal Haircut Window Opens |
| Doubtful D1 Asset | 181 – 365 Days | 25% – 40% Capital Provision | 40% – 60% Principal Haircut Sweet Spot |
| Doubtful D2 / Loss | 365+ Days | 100% Written-Off Asset | 50% – 70% Maximum Debt Waiver |
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Statutory Protections, Civil Court Jurisdictions & Legal Notice Defense
Jab aap personal loan default karte hain, to bank ke legal advocates dwara formal legal notices bheje jaate hain. In notices ko samajhna aur unka sahi legal reply file karna bank ke pressure ko khatam karne ke liye critical hai:
1. Section 25 Payment and Settlement Systems Act (PSSA), 2007: Jab aapka automated National Automated Clearing House (NACH) e-mandate ya ECS debit insufficient balance ke kaaran bounce hota hai, to bank Section 25 PSSA ke tehat legal notice dispatch karta hai. Ye notice quasi-criminal nature ka hota hai lekin isme 30 days ka statutory cure period diya jata hai. Ek professional debt settlement advocate iska reply draft karke financial distress aur absence of fraudulent intent establish karta hai, jisse criminal action void ho jata hai aur matter settlement table par shift ho jata hai.
2. Section 138 Negotiable Instruments Act, 1881: Yadi bank ke paas aapka security cheque tha aur unhone use present karke bounce karwa diya, to Section 138 NI Act ka demand notice bhejte hain. Notice milne ke 15 dino ke andar legal reply dena mandatory hai. Section 147 NI Act ke tehat cheque bounce ke cases 100% compoundable hote hain, jiska matlab hai ki compromise settlement hote hi court complaint unconditionally withdraw kar li jaati hai.
3. DRT Pecuniary Limit Barrier (RDB Act, 1993): Recovery of Debts and Bankruptcy Act ke Section 1(4) ke tehat Debt Recovery Tribunal (DRT) me sirf wahi cases file kiye ja sakte hain jaha debt exposure ₹20 Lakhs ya usse zyada ho. Agar aapka personal loan ₹20 Lakhs se kam hai, to bank DRT ke summary recovery provisions use nahi kar sakta.
4. Order XXXVII Civil Procedure Code (CPC) Summary Suits: Bank civil court me summary suit file kar sakta hai, lekin civil litigation me 4% se 7% non-refundable state court fees lagti hai aur Indian local civil courts me faisla aane me 4 se 8 saal ka samay lagta hai. Is multi-year court friction aur heavy legal costs ke chalte bank civil suits file karne ke bajaye One-Time Settlement (OTS) ko priority deta hai.
Section 171 Indian Contract Act ke mutabiq, lending bank sirf usi bank me mojood accounts par apna lien ya set-off laga sakta hai jaha se loan liya gaya tha. Agar aapka salary account kisi doosre independent commercial bank me hai, to defaulting bank ke paas aapke doosre account se auto-debit karne ya use freeze karne ka koi legal authority nahi hota.
4. Recovery Agent Harassment Defense & RBI Fair Practices Compliance Shield
Personal loan default ke dauran sabse zyada takleef recovery agents ke aggressive behavior se hoti hai. Lekin Reserve Bank of India ne Master Circular on Recovery Agents and Fair Practices Code (August 2022) ke tehat borrowers ke fundamental rights ko protect karne ke liye sakht guidelines banayi hain:
1. Permitted Calling Hours: Recovery agents sirf subah 8:00 AM se shaam 7:00 PM ke beech hi call ya physical visit kar sakte hain. Raat ko call karna ya continuous repetitive calling karna illegal hai.
2. No Third-Party Privacy Violations: Agents ko aapke doston, rishtedaron, padosiyon ya office colleagues ko call karke loan ke baare me batane ya social shaming karne ki sakht manaahi hai. Aisa karna Right to Privacy (Article 21) ka direct violation hai.
3. Mandatory Identity Verification: Har field recovery agent ke paas bank dwara authorized Identity Card aur Bank Authorization Letter hona anivarya hai. Bina ID card ke aane wale agent ko enter karne se mana kiya ja sakta hai.
4. Prohibition of Abusive Language & Intimidation: Physical threats, abusive language, ya mental harassment resort karne par bank aur agency ke khilaaf Indian Penal Code (Section 503/506) / Bharatiya Nyaya Sanhita ke under criminal complaint darj karwayi ja sakti hai.
Jab aap SettleLoans jaise professional legal advocates ko appoint karte hain, to hum bank ko ek formal Letter of Representation and Cease-and-Desist Notice serve karte hain. Iske baad bank aur uske collection agencies ko sabhi communications legal counsel ke through karne ka mandate mil jata hai, jisse daily unauthorized calls aur home visits turant band ho jaate hain. Yadi bank compliance follow nahi karta, to RBI Integrated Ombudsman Scheme (RB-IOS 2021) portal par complaint register karke bank par heavy regulatory penalty lagwayi ja sakti hai.
5. Visual Settlement Workflow: NPA Transition to Zero-Balance NDC
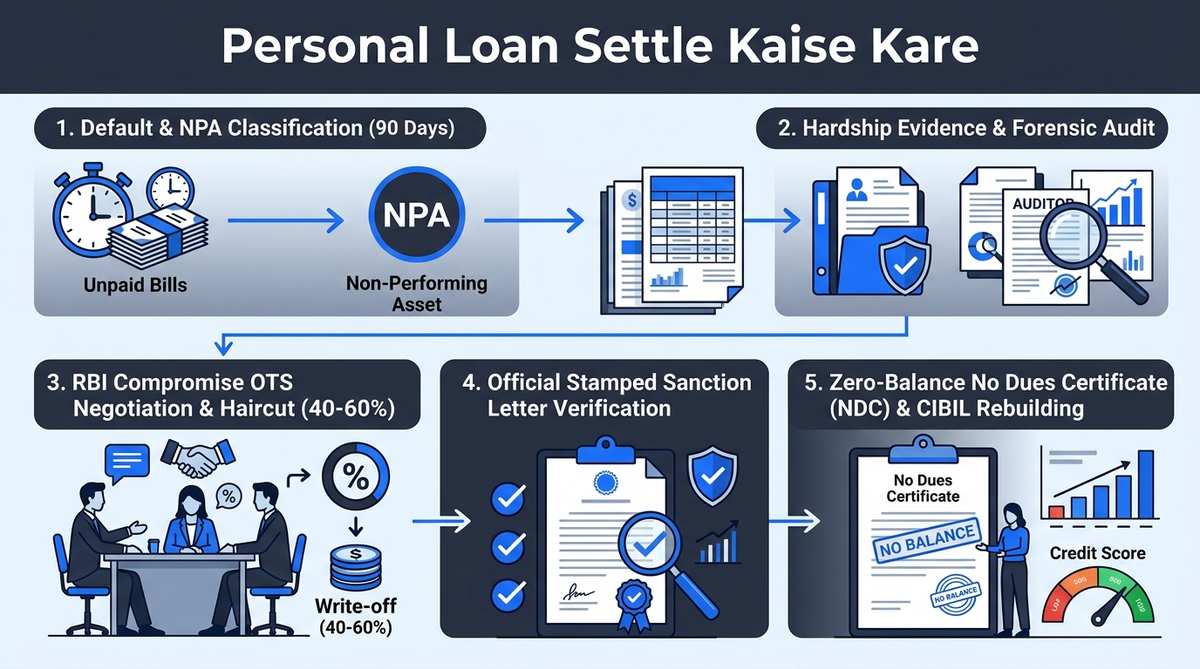
Figure 1.0: Comprehensive Personal Loan Resolution Architecture
Step-by-step institutional trajectory from 90-day NPA classification to forensic ledger audit, RBI compromise negotiation, and official No Dues Certificate issuance.
6. The Haircut Calculation Matrix & Net Present Value (NPV) Recovery Formula
Borrowers ke man me sabse bada sawal hota hai: “Personal loan settle kitne percentage me hota hai?” Iska realistic answer bank ke accounting formula aur recovery economics par depend karta hai. Bank settlement offer banate waqt emotional arguments par nahi, balki cash flow valuation par faisla leta hai.
Har RBI-compliant settlement me sabse pehle loan ledger ki forensic cleansing hoti hai:
• 100% Penal Interest Waiver: Default ke baad bank dwara lagaya gaya 24% se 36% penal interest poori tarah waive hota hai.
• 100% Bounce & Late Fee Waiver: Mandate bounce charges, late processing fee, aur penal interest par laga GST 100% reverse kiya jata hai.
Iske baad jo actual Core Principal Balance bachta hai, us par borrower ki documented financial insolvency ke anusaar 40% se 60% tak ka haircut (discount) negotiate kiya jata hai.
Where C_t represents estimated recoveries, r is the discount rate, and deductions account for 3–5 years of court friction and capital locked in NPA provisions.
| Original Principal Balance | Inflated Bank Ledger (Penal Fees) | Realistic OTS Haircut Range | Expected Settlement Settlement Amount |
|---|---|---|---|
| ₹2,00,000 | ₹2,75,000+ | 50% – 60% Haircut | ₹80,000 – ₹1,00,000 |
| ₹5,00,000 | ₹6,80,000+ | 45% – 55% Haircut | ₹2,00,000 – ₹2,50,000 |
| ₹10,00,000 | ₹13,50,000+ | 40% – 50% Haircut | ₹4,50,000 – ₹5,50,000 |
| ₹20,00,000 | ₹27,00,000+ | 40% – 50% Haircut | ₹9,00,000 – ₹11,00,000 |
7. Bank Se Baat Karne Ka Tarika: 5-Phase Legal Settlement Protocol
Bank ke sath settlement initiate karte waqt unstructured phone calls ya branch me emotional arguments karne se nuksan hota hai. Settlement ko successful banane ke liye yeh 5-phase professional roadmap follow karein:
Phase 1: Forensic Loan Ledger Audit. Sabse pehle apne comprehensive loan statement ko analyze karein. Disbursed amount, total paid EMIs, actual remaining principal, aur bank dwara lagaye gaye penal surcharges aur GST ko alag-alag categorize karein.
Phase 2: Financial Hardship Dossier Compilation. Bank ka Credit Committee bina documented proof ke discount approve nahi karta. Apne hardship ke authentic proofs collect karein, jaise job termination letter, salary slip reduction, audited business loss statement, bank account debit statements, ya critical illness hospital discharge summaries.
Phase 3: Formal Advocate Representation & Channeling. Local recovery agents ko entertain karne ke bajaye bank ke Nodal Officer aur Zonal Settlement Desk ko ek formal Hardship Settlement Representation submit karein. Isme clear karein ki default non-willful hai aur borrower genuine distress me hai.
Phase 4: Credit Committee OTS Counter-Negotiation. Bank shuruat me sirf 10% se 20% discount offer karega. Hamare senior legal advocates NPV recovery math aur hardship dossier present karke realistic 40% se 60% haircut secure karne ke liye counter-negotiate karte hain.
Phase 5: Sanction Letter Verification & Payment Execution. Settlement finalize hone par bank se official One-Time Settlement Sanction Letter hasil karein. Letter ki legal auditing ke baad hi designated bank loan account me direct payment transfer karein.
8. Sanction Letter Forensics, 7-Point Audit Checklist & Zero-Balance No Dues Certificate
Loan settlement process me sabse bada fraud collection agents dwara fake settlement letters issue karke hota hai. Agent paise lekar part-payment me daal dete hain aur account default me hi bana rehta hai. Isliye payment transfer karne se pehle settlement letter ka 7-Point Forensic Audit anivarya hai:
1. Official Bank Letterhead: Letter bank ke official printed letterhead par hona chahiye jisme bank ka registered logo, corporate office address aur unique reference number mention ho.
2. Exact Loan Account Details: Borrower ka pura naam, registered PAN number, aur exact loan account number clearly print hona chahiye.
3. Specific Settlement Amount & Due Date: Negotiated settlement figure (e.g., ₹2,50,000) aur payment deadline date clearly stated honi chahiye.
4. Full & Final Waiver Clause: Letter me explicit term honi chahiye ki payment complete hone ke baad bank bacha hua pura balance waive off karega aur borrower ke khilaaf koi future claim ya liability nahi rahegi.
5. Withdrawal of Legal Proceedings: Bank commitment dega ki pending legal notices (Section 138 NI Act, Section 25 PSSA, civil suits) withdraw aur dismiss kar liye jayenge.
6. Authorized Signatory Seal: Letter par Branch Manager ya Authorized Settlement Officer ka name, employee code aur bank round stamp hona zaroori hai.
7. No Dues Certificate (NDC) Guarantee: Letter me likha hona chahiye ki payment ke 21 se 30 dino ke andar bank official Zero-Balance No Dues Certificate (NDC/NOC) issue karega.
9. Comparative Resolution Matrix: OTS vs. Lok Adalat vs. Restructuring vs. Court Litigation
Defaulted personal loan ko resolve karne ke liye multiple institutional avenues available hoti hain. Sahi option chunna aapki financial situation aur immediate cash liquidity par depend karta hai:
| Resolution Avenue | Primary Mechanism | Typical Haircut / Relief | Legal Finality & Speed |
|---|---|---|---|
| One-Time Settlement (OTS) | Direct advocate negotiation with Bank Zonal Credit Committee | 40% – 60% Principal Haircut + 100% Penal Waiver | Fastest resolution (30–60 days); Stamped Bank Sanction Letter |
| National Lok Adalat | Statutory conciliation under Legal Services Authorities Act, 1987 | 35% – 50% Haircut with mutual consensus | High finality; Equivalent to Civil Court Decree with zero appeal |
| Tenure Restructuring | Extending loan tenure to lower monthly EMI burden | 0% Haircut; Total interest cost increases | Keeps credit score intact; Requires active ongoing income |
| Civil Court Defense (Order 37) | Contesting summary suits through appointed legal counsel | Dispute resolution based on procedural lapses & merits | Protracted litigation (3–7 years); High court and legal expenses |
10. Credit Bureau Trajectory: Understanding ‘Settled’ Status & Rebuilding 750+ CIBIL
Loan settlement complete hone ke baad Credit Information Companies (Regulation) Act (CICRA), 2005 ke tehat bank 30 se 45 dino ke andar charo credit bureaus (TransUnion CIBIL, Experian, Equifax, CRIF High Mark) ko updated data report karta hai. Loan account status ‘Overdue / Default’ se hatkar ‘Settled’ reflect hone lagta hai aur current outstanding balance ₹0 ho jata hai.
‘Settled’ status aane se CIBIL score me 75 se 150 points ka immediate drop ho sakta hai, lekin iska sabse bada fayda yeh hai ki har mahine lagne wale continuous negative overdue default marks permanently band ho jaate hain. RBI guidelines ke mutabiq agle 12 se 24 mahino ke liye mainstream unsecured loans par cooling-off period rehta hai.
Aap in 3 steps ko follow karke apna CIBIL score wapas 750+ tak rebuild kar sakte hain:
1. FD-Backed Secured Credit Card: Kisi bhi leading bank (jaise IDFC WOW, OneCard, ya SBI Unnati) me ₹25,000 se ₹50,000 ki Fixed Deposit karke 100% approval ke sath Secured Credit Card lein.
2. 20%–30% Credit Limit Utilization: Har mahine total credit limit ka sirf 20% se 30% hi use karein aur billing cycle generate hone par full amount time par pay karein.
3. 18–24 Months Clean Payment Track Record: Consistent on-time payments se credit algorithms aapko creditworthy treat karna shuru karte hain aur 2 saal ke andar aapka CIBIL score premium 750+ range me recover ho jata hai.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
Frequently Asked Questions: Personal Loan Settlement in India
Personal loan settle kaise kare aur bank se baat shuru karne ka sahi tarika kya hai?
Personal loan settle karne ke liye sabse pehle apni financial hardship (jaise job loss, medical emergency ya business loss) ke verifiable documents assemble karein. Bank ke branch manager ya collection agents se verbal deal karne ke bajaye bank ke Nodal Officer ya Zonal Settlement Desk ko ek formal written hardship representation bhejein. Isme clear karein ki default willful nahi hai aur aap ek One-Time Settlement (OTS) ke through account permanently close karna chahte hain.
Personal loan settlement me bank kitna discount ya haircut deta hai?
Unsecured personal loan settlement me bank 100% penal interest, late fees aur bounce charges ko completely waive off karta hai. Core principal amount par 40% se 60% tak ka haircut (discount) milna realistic hota hai, jo account ki NPA age (120 se 180 din overdue) aur borrower ki verified repayment capacity par depend karta hai.
Kya personal loan default hone par police arrest ya jail ho sakti hai?
Bilkul nahi. Unsecured personal loan default karna strictly ek civil dispute hai jo Indian Contract Act, 1872 ke under aata hai. Police ke paas loan default me FIR register karne ya arrest karne ka koi legal right nahi hai. Agar cheque bounce (Section 138 NI Act) ya NACH mandate bounce (Section 25 PSSA) ka notice aata hai, to ye bailable quasi-criminal matters hote hain jisme settlement ke baad court case immediately compound hokar dismiss ho jata hai.
Recovery agents agar ghar aakar dhamki de ya badtameezi kare to kya karein?
RBI Master Circular (August 2022) ke mutabiq recovery agents subah 8 baje se pehle aur shaam 7 baje ke baad call ya visit nahi kar sakte. Unhe gali-galoch, dhamki, privacy violation ya relatives ko inform karne ki sakht manaahi hai. Aise mamle me turant incident record karein, bank ke Principal Nodal Officer ko complaint bhejein, legal cease-and-desist notice serve karein aur RBI Ombudsman (RB-IOS 2021) portal par complaint register karein.
Kya bank mere kisi dusre bank ke salary account se paise kaat sakta hai?
Nahi. Bank sirf usi bank me mojood savings ya fixed deposit accounts par Section 171 Indian Contract Act ke tehat 'Banker's Right of Set-Off' use kar sakta hai jaha se loan liya gaya tha. Kisi dusre independent bank ke salary account ko bina civil court decree ke freeze ya auto-debit karne ka bank ke paas koi legal right nahi hota.
Bank ka official OTS settlement letter authentic hai ya fake, kaise pehchanein?
Authentic settlement letter hamesha bank ke official letterhead par authorized signatory ke physical stamp ya digital verification ke sath aata hai. Isme aapka exact loan account number, agreed settlement amount, payment deadline, aur ek clear clause hona chahiye ki payment ke baad bacha hua balance waive ho jayega aur 30 din me zero-balance No Dues Certificate (NDC) issue kiya jayega. Collection agent ke WhatsApp text ya plain paper par kabhi payment na karein.
Settlement payment kahan aur kaise karni chahiye?
Settlement payment hamesha directly apne official loan account number me NetBanking, NEFT/RTGS, ya bank branch counter par receipt lekar karni chahiye. Kisi bhi collection agent, recovery agency ke personal account ya kisi third-party account me ek rupaya bhi transfer na karein.
Loan settlement ke baad No Dues Certificate (NDC) kab milta hai?
Settlement letter me agreed poori amount pay karne ke baad bank ko 21 se 30 dino ke andar official 'No Dues Certificate' (NDC) ya 'No Objection Certificate' (NOC) issue karna mandatory hota hai. Ye certificate confirm karta hai ki loan account permanently close ho chuka hai aur outstanding balance ₹0 hai.
Loan settlement se CIBIL score par kya asar padta hai aur ise kaise sudharein?
Settlement ke baad credit bureaus (CIBIL, Experian) me account status 'Settled' reflect hota hai aur score temporary 75 se 150 points drop ho sakta hai. Lekin compounding overdue default ruk jata hai. Ek Fixed Deposit ke against Secured Credit Card lekar aur 20%-30% utilization maintain karke 18 se 24 mahine me CIBIL score wapas 750+ tak rebuild kiya ja sakta hai.
Kya Lok Adalat me personal loan settle karwana zyada faydemand hota hai?
Haan, National Lok Adalat me settlement karwane ka sabse bada fayda ye hai ki waha hua settlement ek Civil Court Decree ke barabar legally binding hota hai. Bank future me us debt par koi further litigation nahi kar sakta aur dono parties ka dispute permanently aur zero court fee ke sath resolve ho jata hai.
- RBI Master Circular – Framework on Resolution of Stressed Assets & Compromise Settlements (June 2023)
- RBI Master Directions on Outsourcing of Financial Services & Fair Practices Code for Recovery Agents
- Section 25 of the Payment and Settlement Systems Act, 2007 (Electronic Clearing Mandate Bounce Laws)
- Section 138 & Section 147 of the Negotiable Instruments Act, 1881 (Cheque Dishonor & Legal Compounding)
- National Legal Services Authority (NALSA) – Pre-Litigation Lok Adalat Conciliation & Settlement