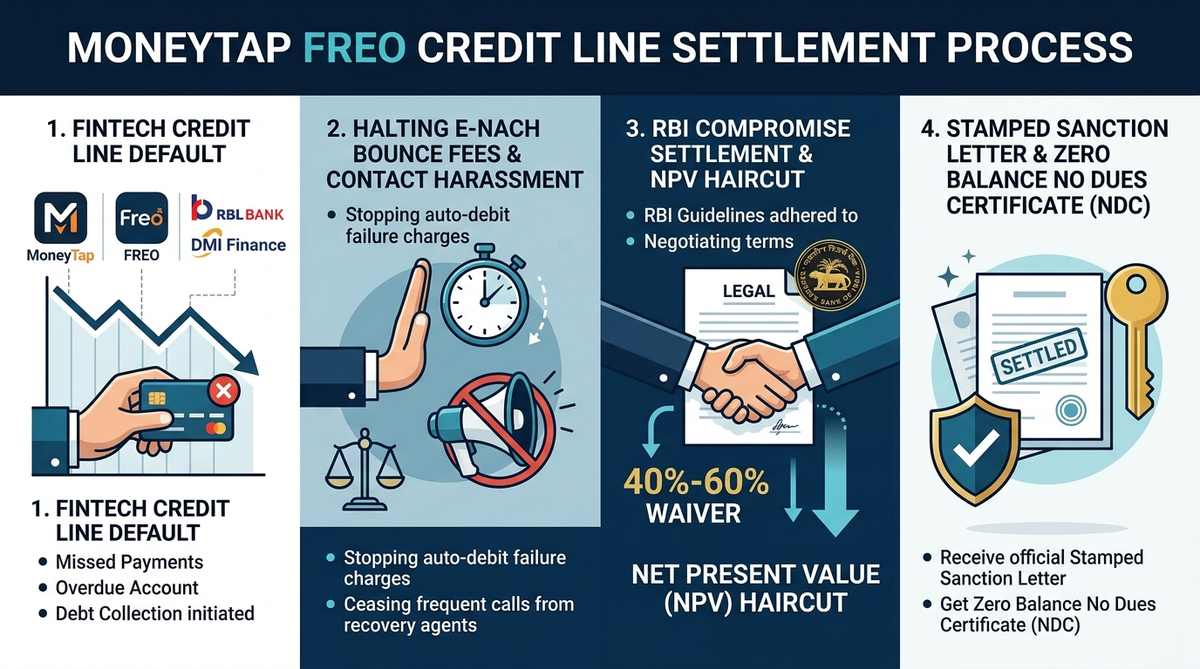
- Underlying Regulated Lenders. MoneyTap and Freo are loan apps. Your legal contracts sit with RBI lenders. The primary lenders are RBL Bank and DMI Finance.
- Halting Multi-Loan e-NACH Sweeps. Each cash draw makes a new sub-loan. Stopping auto-debits under NPCI rules stops repeat fees of ₹500 to ₹1,000.
- Statutory Compromise Waivers. Accounts past 90 days reach NPA status. They get 40% to 60% OTS waivers under RBI rules. All penal fees are dropped.
- Digital Harassment Protections. RBI rules protect your privacy. Agents cannot take your phone contacts. They cannot call family or employers. Calls are banned outside 8:00 AM to 7:00 PM.
- Mandatory ₹0 No Dues Certificate. Under RBI Circular RBI/2023-24/60, lenders must issue an NDC in 30 days. Delays carry a ₹5,000 daily fine.
Deconstructing MoneyTap & Freo
MoneyTap runs under Freo by MWYN Tech Private Limited. It offers an app-based credit line. Under RBI rules, MoneyTap is a Lending Service Provider (LSP). It runs a Digital Lending App (DLA). It is not a direct lender.
The loan money comes from partner lenders. Main risk sits with RBL Bank Limited and DMI Finance Private Limited. Some lines come from Piramal Capital.
All loan agreements stay with RBL Bank or DMI Finance. Credit reporting and settlement approvals remain with them too. In hard times, borrowers must talk to bank Stressed Asset Desks. Do not deal with external app callers.
The Revolving Credit Line Trap
MoneyTap lets users take many cash draws from one credit limit. Each draw forms a new sub-loan. Each loan has its own EMI term. Rates range from 18% to 36% per year.
When funds run low, active draws trigger multiple e-NACH debit runs. Missing one payment triggers three bounce fees. Each fee costs ₹450 to ₹1,000 plus GST. Bank charges add up too. In 60 to 90 days, penal interest quickly inflates total dues.
- SMA-0 (1–30 DPD). Automated SMS and WhatsApp alerts start. Multiple auto-debit attempts occur.
- SMA-1 (31–60 DPD). Debt collection teams take over. Bounce fees rise. App credit line access stops.
- SMA-2 (61–90 DPD). Recovery agencies get involved. Automated legal notices warn of credit damage.
- NPA & Write-Off (90+ DPD). Lenders set aside full loss provisions under Ind AS 109. This allows formal One-Time Settlements.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Stopping Recurring Auto-Debit Penalties
Automated sweeps hit bank accounts many times a month across active sub-loans. This drains bank savings with heavy bounce fees.
Under NPCI guidelines and RBI rules, account holders can stop auto-debits. You can instruct your bank to cancel or pause NACH mandates. You do not need lender approval.
Also, RBI Fair Lending Practice rules state that penal charges must stay fair. They cannot compound. During OTS talks, legal counsel can check your ledger. You can demand a 100% fee waiver. This includes all bounce charges, late fees, and penal interest.
How RBL Bank & DMI Finance Evaluate Settlement Proposals
Settlements with RBL Bank or DMI Finance follow board compromise policies under RBI norms. Once a loan turns NPA, lenders set aside 100% provisions under Ind AS 109.
Lenders evaluate deals using Net Present Value (NPV). They compare immediate cash against years in court:
Where C_t is recovery over time. The letter r is the discount rate. Deductions cover 3 to 5 years of court costs.
Because digital credit lines are unsecured, court recovery yields very low returns. When given clear hardship proof, lenders approve deals with deep debt cuts.
MoneyTap / Freo Settlement Benchmark & Haircut Matrix
| Credit Facility & Co-Lender | Delinquency Aging | Penal Fee Waiver | Core Principal Waiver | Recommended Target Offer |
|---|---|---|---|---|
| MoneyTap - RBL Bank Credit Line. | 90 – 180 Days (NPA). | 100% Full Fee Waiver. | 35% – 50% Principal Cut. | Pay 45%–55% of Principal Drawn. |
| MoneyTap - RBL Bank Credit Line. | 180+ Days (Written Off). | 100% Full Fee Waiver. | 50% – 65% Principal Cut. | Pay 30%–40% of Total Dues. |
| Freo / MoneyTap - DMI Finance Loan. | 90 – 180 Days (NPA). | 100% Full Fee Waiver. | 40% – 50% Principal Cut. | Pay 45%–50% of Core Principal. |
| Freo / MoneyTap - DMI Finance Loan. | 180+ Days (Loss Asset). | 100% Full Fee Waiver. | 55% – 65% Principal Cut. | Pay 30%–35% of Total Claim. |
| MoneyTap - Partner NBFCs. | 120+ Days (NPA Bucket). | 100% Full Fee Waiver. | 45% – 60% Principal Cut. | Pay 35%–45% of Verified Dues. |
MoneyTap (Freo) Credit Line Settlement & Legal Defense Blueprint
Defending Against Aggressive Recovery, Contact Harvesting
External debt collection agencies often break rules. They scrape phone contacts, call workplaces, or threaten family members.
These recovery actions break strict statutory rules:
- RBI Digital Lending Guidelines (2022). Regulated lenders and apps cannot access phone contacts, photos, or location data.
- RBI Recovery Agent Circular. Agents can only call between 8:00 AM and 7:00 PM. Calling relatives, friends, or employers is illegal.
- DPDP Act 2023. Misusing personal data brings heavy fines for apps and partner lenders.
Sending a legal notice to the lender's Principal Nodal Officer halts bad recovery tactics. You can also file a complaint on the RBI Ombudsman portal (cms.rbi.org.in).
Step-by-Step Guide to a Compromise Settlement with MoneyTap
A successful loan settlement follows five clear legal steps:
1Loan Ledger Forensic Audit & Sub-Loan Identification
Get the full loan statement to find each loan account number (LAN). Separate core principal from extra bounce charges and penal fees.
2Establishing Bona Fide Commercial Hardship
Gather clear proof of financial distress. Useful proofs include job loss letters, medical bills, or salary cuts. This shows genuine, non-wilful default.
3Submitting the Formal Hardship & OTS Petition
Send a formal settlement letter. Contact the Stressed Assets Desk at RBL Bank or DMI Finance. Also copy the Nodal Officer. Ask for full fee waivers.
4Institutional Negotiation & Sanction Letter Issuance
Agree on a fair amount (usually 40% to 55% of principal). Get an official OTS Sanction Letter on bank letterhead covering all sub-loans.
5Direct Bank Channel Payment & NDC Delivery
Pay the settlement amount directly to the bank via RTGS or NEFT. Collect your official No Dues Certificate within 30 days under RBI rules.
Defending MoneyTap Sec 25 PSSA & Arbitration
When defaults pass 90 to 120 days, lenders send legal notices. Knowing your legal rights prevents panic:
1. Section 25 PSSA Demand Notices. Sent when e-NACH mandates bounce. Section 25 of the Payment and Settlement Systems Act is a quasi-criminal law. It aims for debt recovery, not jail. Replying with a hardship letter and starting OTS talks halts court cases.
2. Unilateral Online Arbitration. Fintech apps often start digital arbitration. They appoint a sole arbitrator without your consent. Under Supreme Court rulings in Perkins Eastman and TRF Ltd., one-sided choices are void. Advocates can challenge this under Section 12 of the Arbitration Act.
3. National Lok Adalat Conciliation. RBL Bank and DMI Finance join quarterly National Lok Adalats under NALSA. Lok Adalats help seal compromise deals. They pass a final court decree. This decree ends the debt for good.
MoneyTap OTS Sanction Letter Forensics
Never pay on verbal promises or informal messages from collection agents. Payments made without authorized letters are often used for fees instead of closing the debt.
- Official Letterhead. The letter must use official bank letterhead. It must show RBL Bank or DMI Finance. It must list their CIN number.
- Sub-Loan Coverage. It must list every individual loan account number (LAN) under your credit line.
- Full Discharge Clause. The letter must state that this payment clears the entire debt. It must show a zero balance.
- 30-Day NDC Mandate. Under RBI Circular RBI/2023-24/60, the lender must provide the NDC in 30 days. Any delay costs them ₹5,000 per day.
MoneyTap Post-Settlement CIBIL Recovery
Settling a MoneyTap credit line updates credit bureaus (CIBIL, Experian, Equifax, CRIF High Mark). The loan status changes to 'Settled' with an outstanding balance of ₹0.
Your credit score may drop by 75 to 140 points initially. But it stops mounting default penalties and legal actions. A settled account with a ₹0 balance gives you a clean start to rebuild.
You can rebuild your credit score back to 750+ in 18 to 24 months. Use a fixed-deposit credit card. Keep card use below 20%. Pay on time every month.
Why Distressed Borrowers Choose SettleLoans
SettleLoans shields borrowers from recovery harassment. We send statutory notices. We remove unfair bounce fees. We reply to Section 25 PSSA notices. We deal directly with RBL Bank and DMI Finance. We secure 40% to 60% debt waivers and official ₹0 No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: MoneyTap (Freo) Credit Line Settlement
Who is the actual legal lender behind my MoneyTap (Freo) credit line?
MoneyTap is a tech platform and Loan Service Provider (LSP). It does not lend its own money. Regulated lenders provide the funds. The main lenders are RBL Bank Limited and DMI Finance Private Limited. Some lines come from Piramal Capital. All legal loan agreements belong to these lenders. Official OTS sanction letters and No Dues Certificates must come directly from them.
How does the MoneyTap revolving credit line trap salaried borrowers?
MoneyTap lets you take several cash withdrawals from one limit. Each withdrawal becomes a separate sub-loan. Each loan has its own monthly EMI. If you miss a payment, every sub-loan bounces. You face multiple e-NACH bounce fees (₹450 to ₹1,000 + GST each). Penal interest adds up quickly. This rapidly inflates your total loan balance.
How can borrowers stop recurring MoneyTap e-NACH bounce penalties across multiple sub-loans?
You can stop auto-debit bounce fees easily. First, submit a written mandate cancellation to your bank under NPCI rules. Second, send a hardship notice to RBL Bank or DMI Finance. Ask them to freeze mandate debit runs. Third, seek a full waiver of all bounce fees during OTS talks. RBI Fair Lending Practice rules support this waiver.
What percentage of debt waiver or haircut can be negotiated on a defaulted MoneyTap credit line?
Regulated lenders like RBL Bank and DMI Finance offer 40% to 60% debt waivers on unsecured lines. Loans overdue past 90 days reach NPA status. Accounts past 180 days count as loss assets. These older debts get the biggest principal cuts. Lenders also cancel 100% of unpaid late fees and bounce charges.
How do you protect against aggressive recovery calls, contact harvesting, and harassment from MoneyTap agents?
RBI Digital Lending Guidelines protect your data privacy. The DPDP Act 2023 also safeguards your rights. Agents cannot access your phone contacts. They cannot call your family, friends, or employer. They can only call between 8:00 AM and 7:00 PM. A legal cease-and-desist notice to the lender stops unfair recovery calls.
Can RBL Bank or DMI Finance file a criminal case or arrest a borrower for defaulting on a MoneyTap loan?
No. Default on an unsecured digital credit line is a civil matter. It is a contract breach under the Indian Contract Act, 1872. Police cannot arrest you for honest financial hardship. Lenders may send Section 25 PSSA notices for bounced mandates. These are compoundable legal matters. Legal counsel can settle them through compromise talks.
How should borrowers handle unilateral digital arbitration notices issued for MoneyTap defaults?
Fintech lenders often start online arbitration. They appoint a sole arbitrator without your consent. The Supreme Court ruled such one-sided appointments invalid in TRF Ltd and Perkins Eastman. An advocate can challenge the arbitrator under Section 12 of the Arbitration Act. This halts proceedings and redirects the dispute to settlement.
How do you verify an authentic MoneyTap / Freo settlement sanction letter?
An authentic OTS letter must use official letterhead. It must show the name of RBL Bank Limited or DMI Finance Private Limited. It must display their Corporate Identification Number (CIN). It should list all your active sub-loan account numbers. It must state the agreed settlement sum and clear payment dates. It must confirm full loan closure.
How does settling a MoneyTap credit line affect your CIBIL score and how do you obtain the No Dues Certificate?
Settling a credit line marks the account as 'Settled' with a ₹0 balance in CIBIL. Your credit score will drop initially. But it stops ongoing default marks and legal threats. Under RBI Circular RBI/2023-24/60, the lender must issue your No Dues Certificate within 30 days. Lenders must pay ₹5,000 per day if they delay.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI). Guidelines on Digital Lending (DOR.CRE.REC.66/21.07.001/2022-23). Rules stop data harvesting and govern LSPs.
- RBI Master Direction. Framework for Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24).
- RBL Bank Limited. Customer Grievance Redressal Policy. Digital lending rules and Nodal Officer details.
- DMI Finance Private Limited. Fair Practices Code. Recovery agent oversight rules and Stressed Assets Desk.
- Reserve Bank - Integrated Ombudsman Scheme. CMS Portal for app complaints, unfair fees, and delayed NDCs.