- Legal Compromise Protections. Loan default is a civil matter. Borrowers have legal rights under RBI rules. They can seek an OTS settlement.
- Direct SAMD Desk Escalation. Local branch managers hold low discount power. Real settlements are cleared by SAMD in Aluva. Zonal hubs also approve terms.
- Stopping Electronic Mandate Fees. Cancelling e-NACH mandates stops repeat bounce fees. You save ₹500 to ₹1,000 each. Legal action waives 100% of penal interest.
- Gold Loan Deficit Defense. If gold auctions leave an unpaid debt, the bank cannot seize assets. A court order is needed. You can settle shortfalls for a small fraction via OTS.
- Getting Your ₹0 NDC. Under RBI rules, Federal Bank must issue your NDC. Delivery must happen within 30 days. Delays carry a ₹5,000 daily fine.
Understanding Federal Bank's Stressed Assets Recovery
Federal Bank is based in Aluva, Kochi. It is a leading private bank in India. Its recovery setup follows a strict framework.
When loans default, authority leaves retail branches. Cases move to the central Stressed Assets Management Department (SAMD). Operating from Aluva and zonal hubs, SAMD handles bad debts. They follow RBI rules.
Distressed borrowers often face recovery calls. But default is a civil matter under the Indian Contract Act, 1872. It is not a crime. Borrowers can stop bad agent tactics. They have the legal right to seek an OTS.
Federal Bank Delinquency Lifecycle
Federal Bank tracks overdue loans under RBI IRACP norms. These stages guide your settlement strategy:
When an EMI is missed, automated SMS alerts start. Branch teams call for payment. Bounce fees and penal interest are added.
In the second month, the account moves to calling agencies. Borrowers face frequent phone calls and loan recall notices.
Risk escalates quickly. The bank issues legal notices under Section 138 NI Act. Notices also invoke Section 25 PSSA. Field visits may occur.
After 90 days, the loan becomes an NPA under RBI rules. Interest stops building up. Recovery moves to SAMD. This opens the OTS settlement window.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Stopping Repeat NACH Bounce Penalties
Loan distress grows with repeated bounce fees. Federal Bank tries multiple debit runs each month. They charge ₹500 to ₹1,000 plus GST. Your savings bank charges another ₹350 to ₹590.
These fees inflate total dues. You can stop this drain quickly:
- Mandate Stop Under NPCI Rules. Under NPCI rules, you can cancel NACH mandates. This stops all automated debits.
- Invoking RBI Penal Charges Circular (RBI/2023-24/53). Under RBI rules, banks cannot compound penal interest. Penal fees cannot be added to the principal.
- Demanding 100% Penalty Reversal During OTS. Advocates demand a 100% waiver during SAMD talks. All bounce fees and penal interest are dropped.
How Federal Bank Calculates Settlement Haircuts
Federal Bank evaluates settlements using RBI provisioning rules. Banks must set aside capital reserves against bad debts:
| Loan Stage | Delinquency Duration | Required RBI Provision | Typical OTS Haircut Potential |
|---|---|---|---|
| Standard / SMA-2. | 1 to 90 Days. | 0.40% to 5.0% Provision. | 0% to 15% (Restructure). |
| Sub-Standard Asset. | 91 to 365 Days (NPA). | 15% to 25% Provision. | 35% to 45% Debt Cut. |
| Doubtful Asset (D1 & D2). | 1 to 3 Years in NPA. | 25% to 40% Provision. | 45% to 55% Debt Cut. |
| Doubtful 3 & Loss Asset. | 3+ Years / Written Off. | 100% Provision. | 55% to 65% Debt Cut. |
For Sub-Standard loans, the bank takes heavy loss provisions. DRT court cases take 3 to 7 years. SAMD teams prefer quick cash via OTS. Long court trials take years.
C_t is future recovery. r is the discount rate. Deductions cover court fees and capital provisions.
Federal Bank Loan Settlement Process Roadmap
This visual guide maps each step of a Federal Bank settlement. It tracks default past 90 days. It covers SAMD escalation. It explains notice defense, OTS talks, and NDC delivery.
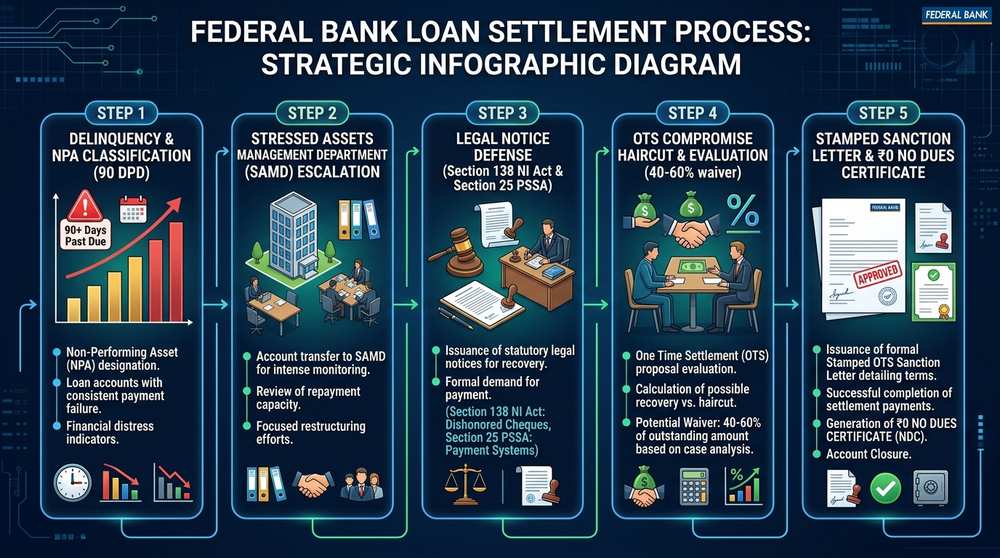
Enforcing RBI Directives Against Unlawful Recovery
Federal Bank is a regulated scheduled commercial bank. But third-party recovery agents often use harsh tactics. The RBI sets strict rules on recovery conduct. It limits outsourcing practices.
Federal Bank borrowers enjoy key statutory protections:
Strict Calling Hours (08:00 AM – 07:00 PM)
Agents may call only between 8:00 AM and 7:00 PM. Calls before 8 AM or after 7 PM are illegal. Repeat auto-dialing is also banned.
No Contact With Third Parties
Agents cannot call employers, friends, or neighbors. Sharing loan details violates DPDP laws and RBI rules.
No Office Visits
Office visits meant to shame borrowers are illegal. Field agents must show bank ID cards. They must respect your privacy.
No False Criminal Threats or Fake Notices
Agents cannot threaten police arrest or jail. Fake court notices sent on WhatsApp are illegal. Legal notices must come through registered advocates.
If agents harass you, counsel serves a notice to the Nodal Officer at Aluva. Ongoing abuse is reported to the RBI Ombudsman.
Step-by-Step Federal Bank Compromise Settlement Guide
Federal Bank loan settlement follows five clear legal steps:
Stage 1: Financial Hardship Dossier Preparation
You gather proof of financial distress. This includes job loss letters, medical bills, or salary cuts.
Stage 2: Mandate Revocation & Loan Account Audit
Advocates cancel your NACH mandate to stop bounce fees. They review your loan statement. They remove unfair penalties to find the pure principal.
Stage 3: Direct Appeal to SAMD Recovery Desks
A formal OTS file is sent to SAMD in Aluva. It can also go to the Zonal SAMD Manager. The file seeks a 40% to 60% debt waiver under RBI rules.
Stage 4: Settlement Letter Verification & Check
When approved, Federal Bank issues an official OTS letter. Advocates verify the payment amount and dates. They check waiver and ₹0 NDC terms.
Stage 5: Settlement Payment & ₹0 NDC Delivery
You pay the agreed sum into the bank loan account. Federal Bank closes the account. They return pledged papers. They deliver the No Dues Certificate within 30 days.
Defending Sec 138, Sec 25 & Gold Loan Shortfall Claims
Federal Bank often starts legal steps for overdue debts. A strong legal reply stops pressure. It opens the door to an amicable OTS.
1. Section 138 Negotiable Instruments Act & Section 25 PSSA Notices
When a cheque bounces, the bank sends a 15-day notice. It invokes Section 138 NI Act or Section 25 PSSA. These cases are 100% compoundable. An advocate reply shows true distress and offers an OTS. The matter is settled in Magistrate Court or Lok Adalat.
2. Gold Loan Auction Shortfall & Deficit Resolution
Federal Bank has a large gold loan base. If default happens, the bank auctions gold after a 14-day notice.
If the auction does not cover dues, the bank claims a shortfall. But this deficit is an unsecured civil debt. Federal Bank cannot seize assets without a court decree. Borrowers can dispute high auction fees. You can settle the shortfall for 25% to 40% via OTS.
| Resolution Channel | Governing Legal Framework | Expected Haircut Range | Resolution Timeline | Legal Finality |
|---|---|---|---|---|
| Direct SAMD OTS. | RBI Master Directions. | 40% to 60% Haircut. | 15 to 30 Days. | Binding contract with ₹0 NDC. |
| National Lok Adalat. | Legal Services Act, 1987. | 45% to 60% Haircut. | Single-day hearing. | Final court decree. |
| Sec. 138 / 25 Defense. | Magistrate Court Case. | 35% to 50% Haircut. | 1 to 3 Months. | Full case withdrawal. |
| Gold Shortfall OTS. | Contract Act Pledge Rules. | 60% to 75% Waiver. | 15 to 45 Days. | Full release of debt. |
Checking Federal Bank Settlement Letters
Never pay on verbal promises or unverified letters. Unofficial payments are treated as regular partial dues. Penal interest keeps building up.
Every genuine OTS letter must meet strict legal checks:
- Official Corporate Letterhead. The letter must come on The Federal Bank Limited letterhead. It must show the CIN and Aluva office address.
- Official Bank Seal. The letter must show the name, code, and seal. It is signed by the SAMD Manager.
- Full and Final Waiver Clause. The terms must confirm full debt waiver upon payment. No future claims can be made.
- Mandatory 30-Day NDC Delivery. Under RBI rules, Federal Bank must issue the No Dues Certificate. Delivery must take under 30 days. Delays carry a ₹5,000 daily fine.
Federal Bank Post-Settlement CIBIL Recovery
After settlement, Federal Bank updates CIBIL and other bureaus. The status becomes Settled with a ₹0 balance.
A Settled tag causes a score drop of 75 to 150 points. But it stops negative marks and court threats. A closed loan with zero dues beats an active default.
You can rebuild your score back to 750+ within 18 months. First, get a secured credit card with a ₹25,000 limit. Second, use less than 25% of your card limit. Third, pay all bills on time every month.
Why Federal Bank Borrowers Choose SettleLoans
Settling a Federal Bank loan requires expert legal handling. SettleLoans stops recovery harassment with legal notices. We defend Section 138 and Section 25 court cases. We audit statements to waive illegal fees. Our team talks directly with Federal Bank SAMD desks. We negotiate at Aluva and zonal hubs. We secure top debt cuts and your ₹0 No Dues Certificate.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: Federal Bank Loan Settlement
What is the Federal Bank loan settlement process and how does an OTS compromise work?
Federal Bank loan settlement resolves unpaid debt under RBI rules. If a loan is unpaid for 90 days, it turns into an NPA. The file moves from the branch to the SAMD desk. Borrowers submit a hardship file. SAMD reviews it and issues an OTS letter with a 40% to 60% debt waiver.
How does Federal Bank's Stressed Assets Management Department (SAMD) handle defaulted loans?
Federal Bank handles bad loans via SAMD desks in Aluva and zonal hubs. When an account turns into an NPA, SAMD officers take charge. They have the power to approve debt waivers and issue OTS letters.
What percentage of debt waiver or haircut can you realistically negotiate with Federal Bank?
Federal Bank approves debt waivers between 40% and 60% on personal and business loans. For older NPA accounts, waivers can reach 50% to 60%. The bank also waives 100% of penal interest and bounce fees.
Can Federal Bank recover shortfalls after auctioning pledged gold ornaments in a gold loan default?
If a gold auction does not cover total loan dues, the bank claims the shortfall. But this unpaid balance is an unsecured civil debt. The bank cannot seize assets without a court order. You can settle the shortfall for 25% to 40% via OTS.
How can borrowers stop Federal Bank NACH bounce charges and repeated debit attempts?
You can stop repeat debit fees easily. First, cancel the NACH mandate through your bank. Second, send a hardship letter to Federal Bank to pause debits. Third, demand a 100% waiver on all bounce charges during OTS talks.
What legal protections exist against aggressive Federal Bank recovery agents and third-party callers?
Under RBI rules, recovery agents face strict limits. They can call only between 8:00 AM and 7:00 PM. They cannot call friends, family, or employers. Abusive language and office visits are banned. A legal notice to the Nodal Officer stops bad agent behavior.
How should a borrower handle a Section 138 NI Act or Section 25 PSSA notice from Federal Bank?
A Section 138 or Section 25 notice needs an advocate reply within 15 days. The reply explains your financial distress and challenges late fees. It offers an OTS compromise. The matter is then settled before a Magistrate Court or Lok Adalat bench.
Can Federal Bank freeze your savings account in another bank for a personal loan default?
No. Federal Bank can only hold funds in its own accounts under Section 171 of the Indian Contract Act. They have no power to freeze accounts in other banks without a court order.
How does settling a Federal Bank loan impact your CIBIL score and how can you rebuild it?
Settling a loan marks your CIBIL file as Settled with a ₹0 balance. Your score drops initially by 75 to 150 points. But it stops default tags and court threats. You can rebuild your score back to 750+ within 18 months using a secured card.
What is the mandatory timeline for Federal Bank to deliver the No Dues Certificate (NDC) post-settlement?
Under RBI rules, Federal Bank must issue your No Dues Certificate within 30 days of payment. They must also return all pledged papers. If the bank delays past 30 days, they must pay ₹5,000 per day to you.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI). Master Direction on Compromise Settlements (DOR.STR.REC.20/21.04.048/2023-24).
- RBI Circular. Fair Lending Practice - Penal Charges in Loan Accounts (RBI/2023-24/53).
- The Federal Bank Limited. Customer Grievance Redressal Policy and Nodal Officers Matrix.
- Reserve Bank - Integrated Ombudsman Scheme, 2021. Online Portal for Banking Grievances.
- National Legal Services Authority (NALSA). Lok Adalat Settlement Guidelines.