- P2P Platform Setup. Innofin Solutions runs LenDenClub. App bots cannot waive debt. Real OTS deals are done with the desk.
- Stop e-NACH Charges. Stop auto-debit at your bank under NPCI rules. This stops extra fees and bank bounce costs.
- 40% to 65% Waivers. Loans are unsecured. Debts over 90 days past due get 40% to 65% principal cuts.
- Shield From Agent Calls. RBI rules ban calls to family or work. Breaking rules brings RBI action.
- Get ₹0 NDC. Under RBI Circular RBI/2023-24/60, you get your No Dues Certificate within 30 days of payment.
Deconstructing LenDenClub
LenDenClub runs under Innofin Solutions. It is an RBI-registered NBFC-P2P platform. It links small lenders with retail borrowers. Loan funds sit in a Trustee Escrow Account. In loans from Finstree, small lenders carry risk. Innofin Solutions handles loan collections.
If you miss EMIs, the app sends alerts and automated calls. App chatbots have no power to waive debt. To get an OTS deal, you must talk directly to the settlement desk at Innofin Solutions.
P2P Loan Delinquency Lifecycle
When you miss an EMI, the loan moves through set stages. It turns into an NPA after 90 days of default. The platform sends automated notices and runs auto-debits. Past 90 days, loss write-downs begin. This opens the door for OTS talks.
| Delinquency Bucket. | Aging (Days Past Due). | Platform & Agency Action. | Legal Exposure. | Settlement Haircut Window. |
|---|---|---|---|---|
| SMA-0 (Incipient Default). | 1 – 30 Days. | Automated SMS, push alerts, and IVR calls. | Nil legal action. Initial credit bureau report. | Negligible. Full payment demanded. |
| SMA-1 (Mid-Stage Delinquency). | 31 – 60 Days. | Outsourced tele-callers contact borrower. | Draft warning notices sent. CIBIL score drops. | Low. Loan tenure restructuring only. |
| SMA-2 (Pre-NPA Escalation). | 61 – 90 Days. | Field recovery agents assigned. | Section 25 PSSA demand notices dispatched. | Moderate. 100% waiver of late fees possible. |
| Substandard Asset (NPA). | 91 – 180 Days. | Stressed Asset team takes over recovery. | Magistrate summons or digital arbitration. | High (35%–50% Principal Haircut). |
| Doubtful / Loss Asset. | 181 – 365+ Days. | Technical write-off on internal ledgers. | Lok Adalat notices or permanent debt write-down. | Maximum (50%–65% Total Haircut). |
Past 180 days, legal fees cost more than the loan is worth. Innofin Solutions prefers quick cash recovery via an OTS. This lets borrowers get the highest possible debt waivers.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Stopping Predatory e-NACH & Penal Interest
Auto-debit systems run bank sweeps up to 4 times a month. Each failed attempt adds two fees. Your bank charges ₹295 to ₹590 per bounce. The platform adds late fees of 24% to 36% per year. This makes the total debt grow fast.
You can stop these fees easily. File a mandate stop form at your bank branch under NPCI rules. Under RBI rules on fair lending, lenders cannot compound penal charges. SettleLoans gets a 100% waiver on all bounce fees and penal interest during OTS talks.
P2P Stressed Asset Valuation
P2P personal loans are unsecured civil debts. They do not fall under the SARFAESI Act. To collect, lenders must go to civil court. LenDenClub uses an NPV model. They weigh quick cash today against years of slow court action.
C_t is expected recovery. r is the discount rate. Deductions include 3–5 years of court delay, legal retainers, and servicing costs.
Realistic LenDenClub Settlement Haircut Slabs by Aging & Hardship Tier
| Platform Facility Tier. | Delinquency Category. | Penal & Bounce Waiver. | Principal Haircut Range. | Target Settlement Benchmark. |
|---|---|---|---|---|
| LenDenClub Retail Personal Loan. | 90 – 180 Days (NPA). | 100% Full Waiver. | 30% – 45% Principal Waiver. | Pay 55%–70% of Core Principal. |
| LenDenClub / Finstree Co-Lending. | 181 – 365 Days (Doubtful). | 100% Full Waiver. | 45% – 60% Principal Waiver. | Pay 40%–55% of Core Principal. |
| Written-Off P2P Portfolio. | 365+ Days (Loss Asset). | 100% Full Waiver. | 55% – 65% Principal Waiver. | Pay 35%–45% of Core Disbursed Sum. |
| Critical Medical / Hardship Case. | Any Stage (Post-NPA). | 100% Full Waiver. | 50% – 65% Total Haircut. | Pay 35%–50% in Single Tranche. |
Lenders lose yields on bad loans. Getting 40% to 55% of core principal back lets them reinvest. This makes OTS deals good for Innofin Solutions once hardship is shown.
LenDenClub P2P Loan Settlement & Debt Resolution Blueprint
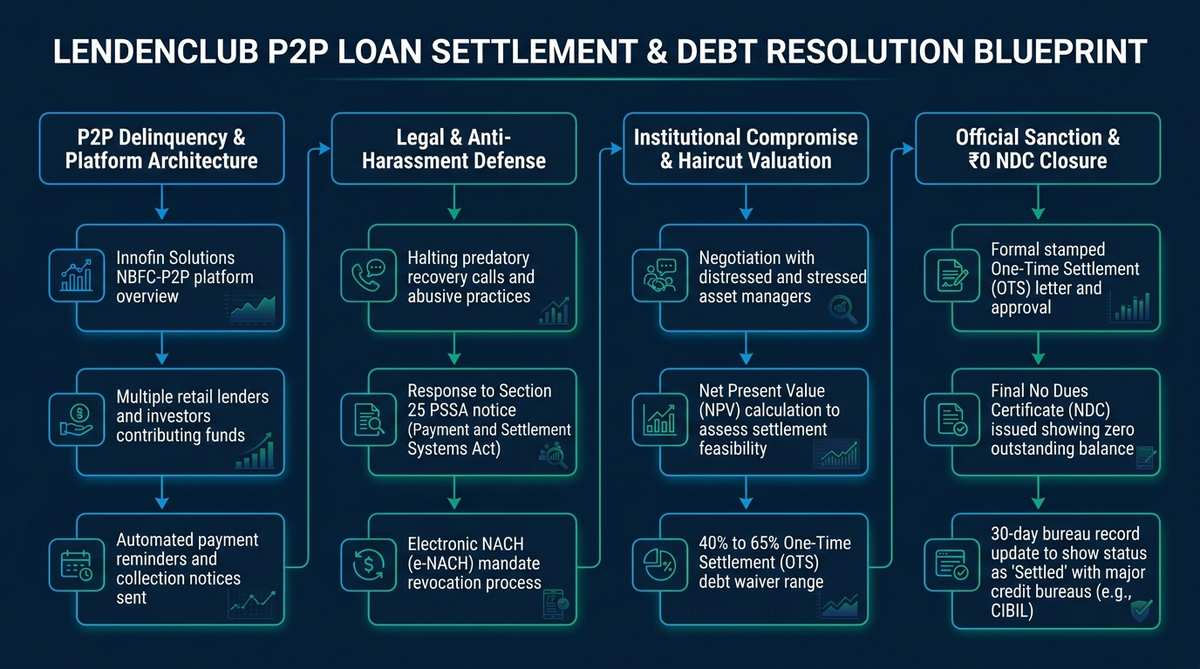
Statutory Protections Against P2P Recovery Harassment
Borrowers face harsh agent tactics after default. These include non-stop calls. Callers may phone workplaces or reach out to family. Under RBI Master Directions, these acts are illegal. Agents can only call between 8:00 AM and 7:00 PM. Third-party disclosure is banned. Apps cannot read your contacts or photos.
If agents break these rules, SettleLoans sends a legal notice. We serve the Nodal Officer of Innofin Solutions. We also file a complaint on the RBI Ombudsman portal (CMS). This stops calls within 48 hours. It gives you strong ground for OTS talks.
Step-by-Step LenDenClub Settlement Roadmap
Settling an NBFC-P2P loan needs a clear legal strategy. This prevents fake agent deals and clears your debt for good.
1Forensic Ledger Audit & Entity Identification
Audit your loan agreement and CIBIL file. Separate pure principal from bounce fees and late interest under Innofin Solutions.
2Revocation of e-NACH Mandates & Communication Routing
Stop auto-debits at your bank under NPCI rules. This prevents repeat fees. Tell the lender in writing to route calls to your advocate.
3Submission of Involuntary Hardship Dossier
Gather proof of hardship. Examples include job loss slips, hospital bills, or wage cuts. Submit an OTS plea to the settlement desk.
4Multi-Round Financial Negotiation
Counter low waiver offers with hardship proof. Guide the committee toward a 40% to 65% principal waiver.
5Forensic Verification of the Stamped OTS Sanction Letter
Check the letter on official Innofin Solutions letterhead. Verify your loan number, payment terms, and ₹0 balance clauses.
6Dedicated Escrow Remittance & Enforcement of ₹0 NDC Delivery
Pay funds directly to the Trustee Escrow Account via RTGS or NEFT. Track delivery of your ₹0 No Dues Certificate within 30 days.
Defending LenDenClub Sec 25 PSSA & Arbitration
After 60 to 90 days of default, lenders send notices under Section 25 of the Payment and Settlement Systems Act, 2007 (PSSA). This notice is for failed e-NACH debits. It is not an arrest warrant. The offense is fully compoundable in court. An advocate reply showing distress disproves bad intent. It moves the case to an amicable settlement path.
Unilateral arbitration without mutual consent is invalid. The Supreme Court confirmed this in Perkins Eastman and TRF Ltd rulings. Filing objections under Section 12(5) and Section 14 of the Arbitration Act halts proceedings. It moves the case to National Lok Adalat, where deals carry the status of a final Civil Court Decree.
| Resolution Channel. | Legal Mechanism. | Haircut Potential. | Timeline. | Enforceability. |
|---|---|---|---|---|
| Direct Platform OTS. | Bilateral settlement under RBI rules. | 40% to 60% Haircut. | 15-30 Days. | Binding contract with NDC. |
| National Lok Adalat. | Judicial conciliation before DLSA bench. | 45% to 65% Haircut. | Single session. | Civil Court Decree (Final). |
| Arbitration Defense. | Contesting unilateral digital arbitrations. | Converts to OTS. | 3-8 Months. | Section 34 / 14 challenge. |
| Section 25 PSSA Defense. | Magistrate court compoundable defense. | 35% to 55% Haircut. | 2-6 Months. | Formal criminal withdrawal. |
National Lok Adalats organized by NALSA offer the best venue for borrowers. Held quarterly across district courts, Lok Adalat benches grant broad compromise write-offs. Settlements carry the force of a final Civil Court Decree. This protects borrowers from future claims.
Authenticating the OTS Sanction Letter
Never pay money without a verified settlement letter. The letter must be on official Innofin Solutions letterhead. It must show a CIN, office address, loan number, and manager signature. Pay only into the official escrow account. Never send funds to personal UPI IDs or third-party accounts.
After you pay, RBI Circular RBI/2023-24/60 requires the lender to act. They must issue your No Dues Certificate within 30 days. They must also update credit bureaus. Lenders face a penalty of ₹5,000 per day paid to the borrower for delays beyond 30 days.
LenDenClub CIBIL Bureau Reporting & Score Trajectory
After settlement, Innofin Solutions marks the loan as 'Settled' in CIBIL with a ₹0 balance. Your credit score may drop by 75 to 120 points at first. But it stops monthly default marks. It also removes all risk of legal action.
You can rebuild your score back to 750+ in 18 to 24 months. Get an FD-backed credit card. Keep card usage below 25%. Pay bills on time to restore prime credit status.
Why Distressed LenDenClub Borrowers Trust SettleLoans
Settling a defaulted P2P loan takes skilled legal help. SettleLoans gives full legal representation for borrowers in distress. We issue legal notices to stop recovery calls. We cancel bank e-NACH mandates to stop bounce fees. We draft legal replies to Section 25 PSSA notices. We challenge one-sided arbitration cases. Our team negotiates directly with Innofin Solutions to secure top debt waivers and ₹0 No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: LenDenClub Loan Settlement
Can I negotiate and settle a LenDenClub loan directly through the LenDenClub mobile app?
No. The app cannot grant debt waivers. In-app bots and phone callers lack power to settle debt. To get an OTS waiver, your advocate must negotiate with Innofin Solutions directly.
What is the legal entity behind LenDenClub and how does Finstree relate to my loan?
LenDenClub is run by Innofin Solutions Private Limited, an RBI-registered NBFC-P2P. Finstree is a sourcing partner. All loan contracts and official settlement letters come from Innofin Solutions.
What percentage of debt waiver or haircut can be negotiated on a defaulted LenDenClub P2P loan?
LenDenClub loans are unsecured personal debts. After 90 to 180 days of default, you can negotiate a 40% to 65% principal waiver. All late fees and bounce charges are 100% waived under RBI rules.
How do I stop LenDenClub recovery agents from calling my relatives, friends, and colleagues?
Under RBI rules, recovery agents cannot call third parties. They cannot contact relatives, friends, or coworkers. A legal notice to Innofin Solutions stops all harassment quickly.
Can LenDenClub or its individual retail lenders file an FIR or get me arrested for defaulting?
No. Loan default is a civil matter under the Indian Contract Act, 1872. Police cannot file an FIR. They cannot arrest you for unpaid debt. Threats of police action are unlawful.
What legal steps should I take if I receive a Section 25 PSSA notice for bounced e-NACH on LenDenClub?
A Section 25 PSSA notice is a 15-day demand notice after a failed auto-debit. It is not an arrest warrant. A legal reply stating financial hardship stops litigation and opens OTS talks.
Is online digital arbitration initiated by LenDenClub legally binding on the borrower?
Unilateral digital arbitration without mutual consent is invalid. The Supreme Court established this in Perkins Eastman and TRF Ltd. An advocate can file objections under Section 12 and Section 14 of the Arbitration Act to halt proceedings.
How does settling a LenDenClub loan reflect on my CIBIL credit report and score?
Innofin Solutions reports the account as 'Settled' with a ₹0 balance in CIBIL. Your score may drop 75 to 120 points temporarily. You can rebuild it back to 750+ in 18 to 24 months with a secured credit card.
How can I ensure a LenDenClub settlement sanction letter is 100% genuine before making payment?
A genuine OTS letter must be on official Innofin Solutions letterhead. It must include corporate CIN and RBI registration details. It must specify your loan number and settlement amount. Pay only into the official escrow account.
What is the statutory time frame for LenDenClub to deliver my No Dues Certificate (NDC)?
Under RBI Circular RBI/2023-24/60, lenders must deliver your No Dues Certificate within 30 days. Delays beyond 30 days carry a penalty of ₹5,000 per day payable to the borrower.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Master Directions – Non-Banking Financial Company - Peer to Peer Lending Platform (Reserve Bank) Directions, 2017 (Updated August 2024).
- RBI Master Direction: Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24).
- RBI Circular: Fair Lending Practice - Penal Charges in Loan Accounts & Release of Property Documents (RBI/2023-24/60).
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Statutory Grievance Redressal for P2P Collection Harassment & Excessive NACH Levies.
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987 – National Lok Adalat Pre-Litigation Conciliation.