- Statutory Compromise Rights. Loan defaults are civil disputes under the Indian Contract Act. Students and parents have clear legal rights. Under RBI Master Directions, you can request an OTS.
- Removing Moratorium Interest. Study and grace periods add interest to your main loan. Our legal team demands its removal. We base settlement waivers on the real amount disbursed.
- Substantial 35%–60% Haircut. Loans over 90 DPD become NPAs under Ind AS 109. Credila then checks Net Present Value (NPV) recovery cash flows. They approve deep debt waivers for fast one-time payment.
- Co-Borrower & Collateral Protection. Section 60 CPC shields parents from workplace visits and pension seizure. We turn SARFAESI notices into fair compromise deals.
- Mandatory 30-Day Deed & NDC Release. Under RBI Circular RBI/2023-24/60, Credila must return original deeds within 30 days of payment. They must also clear CERSAI records and issue a ₹0 No Dues Certificate.
HDFC Credila Underwriting & Education Loan Structure
HDFC Credila Financial Services Limited is a major higher education NBFC. It works under RBI NBFC-ND-SI rules. The company funds thousands of students in India, the USA, UK, Canada, and Europe.
Credila gives student loans based on future income and parent guarantees. It offers unsecured loans up to ₹50 Lakhs to ₹75 Lakhs. It gives secured loans above ₹1.5 Crores against house property or fixed deposits. Money goes directly to colleges or student forex cards.
Job loss, visa curbs, OPT limits, layoffs, or health issues can hurt earnings. When this happens, Credila starts recovery steps. But a student loan default is only a civil dispute under the Indian Contract Act, 1872. Under RBI rules, you have clear rights to stop agent calls and settle via a formal OTS.
The Anatomy of Moratorium Interest Capitalization
The hardest part of student debt is compound interest during the study break. Standard terms include 24 to 36 months of college, plus a 6 to 12 month grace period. Floating interest rates range from 11.5% to 15.25% per year.
Most students pay little or no interest while studying. At the end of the grace period, Credila adds all unpaid interest to the principal. This often adds ₹10 Lakhs to ₹20 Lakhs to your loan balance.
When regular EMIs start, you pay fresh interest on top of past interest. If a graduate faces job delays, missed EMIs bring late fees and penal interest of 24% to 36% per year.
Within two years, a ₹35 Lakh loan can grow to ₹55 Lakhs or ₹65 Lakhs. During OTS talks, our advocates audit the loan ledger. We require Credila to remove added interest and penal fees under RBI Fair Lending rules. This anchors your settlement discount to the original money borrowed.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
HDFC Credila Delinquency Lifecycle
Under RBI IRACP norms and Ind AS 109 rules, HDFC Credila groups unpaid loans by Days Past Due (DPD). Knowing these stages helps you time your settlement for top savings.
In early stages (SMA-0 and SMA-1), Credila sends automated call alerts. When an account passes 90 days overdue, it turns into an NPA. Credila must then lock up capital on its books. At this point, the lender prefers an OTS deal to clear the bad debt.
| Delinquency Stage | Overdue Days (DPD) | HDFC Credila Institutional Actions | Legal & Judicial Exposure | Settlement Haircut Potential |
|---|---|---|---|---|
| SMA-0 (Early Alert) | 1 – 30 Days | Automated calls, SMS alerts, repeated NACH debit runs. | No court case; early credit bureau reporting. | Very low (Credila asks for full EMI dues). |
| SMA-1 (Mid Delinquency) | 31 – 60 Days | Regular calls to student and parent; field visits. | Demand letters; credit score drops for both. | Low (Loan term change or EMI pause). |
| SMA-2 (Pre-NPA Escalation) | 61 – 90 Days | Field agent visits; formal loan recall letter. | Section 25 PSSA / Section 138 NI Act notices. | Moderate (Waiver on penal fees possible). |
| NPA (Substandard Asset) | 91 – 180 Days | Moved to Stressed Assets desk; capital provisions booked. | Section 25 PSSA court summons; SARFAESI 13(2) notices. | High (35%–45% Haircut achievable). |
| Doubtful / Loss Asset | 181 – 365+ Days | 50% to 100% loss booked; technical write-off. | Arbitration claims, civil suits (Order 37 CPC), Lok Adalat. | Maximum (45%–60% Haircut achievable). |
When an unsecured student loan is written off, Credila treats the debt as a loss. A lump-sum cash settlement brings money back to their books. This gives credit officers strong reasons to grant deep debt waivers.
HDFC Credila One-Time Settlement (OTS) Policies
Under RBI rules, HDFC Credila follows a board-approved debt settlement policy. Compromise decisions use Net Present Value (NPV) recovery models, not agent promises.
For unsecured student loans, students may still seek jobs and parents have modest savings. Credila's credit desk checks if fast cash beats 3 to 7 years in court, lawyer fees, and locked capital.
Where C_t is expected recovery cash, r is the discount rate, and deductions cover 3 to 5 years of court delays and legal fees.
Realistic HDFC Credila Settlement Haircut Slabs by Product & Aging
| Loan Type | Overdue Days | Fee & Interest Waiver | Principal Waiver | Settlement Target |
|---|---|---|---|---|
| Unsecured Study Loan Abroad | 90 – 180 Days (NPA) | 100% Late Fee Waiver | 30% – 45% Principal Waiver | Offer 40%–50% of Total Dues |
| Unsecured Study Loan Abroad | 181 – 365+ Days (Doubtful) | 100% Moratorium Interest Cut | 45% – 60% Principal Waiver | Offer 35%–40% of Base Loan |
| Unsecured Indian Study Loan | 90 – 180 Days (NPA) | 100% Penal Fee Waiver | 30% – 40% Principal Waiver | Offer 45%–55% of Total Dues |
| Unsecured Indian Study Loan | 180+ Days (Written Off) | 100% Penal & Bounce Waiver | 45% – 55% Principal Waiver | Offer 35%–45% of Total Dues |
| Secured Property Study Loan | 180+ Days (SARFAESI Active) | 100% Penal & Legal Fee Cut | 20% – 35% Principal Waiver | Offer 65%–75% of Total Dues |
HDFC Credila Education Loan Settlement & Co-Borrower Protection Blueprint
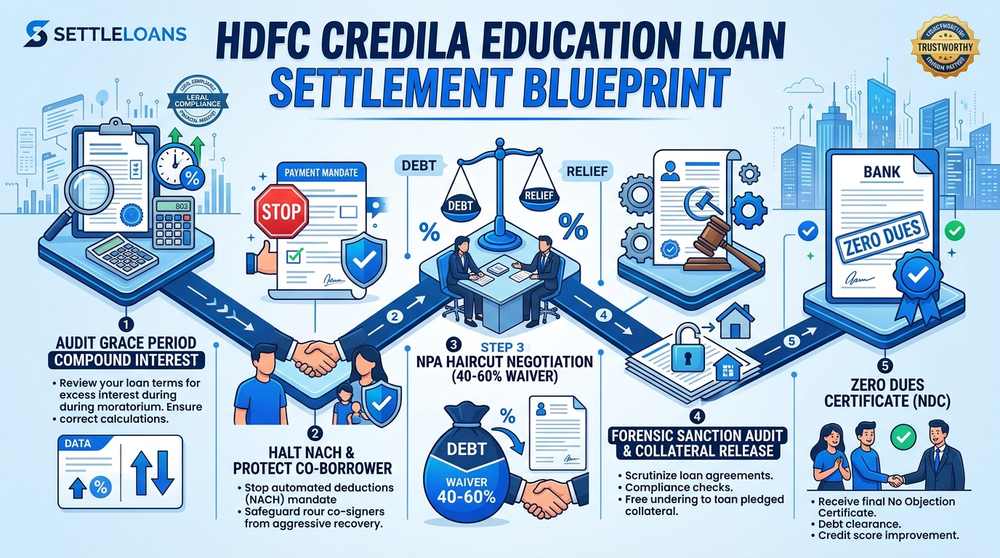
Protecting Parent Co-Borrowers from Recovery Pressure
Most students have no past credit record. So Credila asks parents to sign as joint co-borrowers. Under Section 128 of the Indian Contract Act, 1872, guarantors share equal debt duty.
Still, debt duty does not allow agent abuse. Agents often call retired parents in India while the student is abroad. They make daily calls. They make false threats. They visit offices and claim pensions can be taken.
RBI Master Directions on Recovery Agents set firm rules. Agents cannot call before 08:00 AM or after 07:00 PM. They cannot call relatives. They cannot use harsh words. All agents must carry IIBF DRA cards and Credila IDs.
Under Section 60 CPC, pensions, PF funds (PPF/EPF), family goods, and basic pay cannot be attached. A legal notice to Credila and an RBI CMS complaint stops harassment fast.
Step-by-Step HDFC Credila Settlement Roadmap
Settling an HDFC Credila loan safely requires a clear, step-by-step legal plan:
1Forensic Financial Audit & Hardship Dossier Compilation
Show true money hardship. If abroad, gather visa papers, marks cards, layoff letters, and rent receipts. In India, gather tax slips, pay slips, hospital bills, or pension slips.
2Revoking e-NACH Mandates & Establishing Legal Representation
Tell your bank in writing under NPCI rules to stop e-NACH debits. This ends bounce fees. Send a legal notice so all calls go to your lawyer.
3Submitting Structured OTS Petition to Stressed Assets Desk
Send an OTS letter to Credila's Stressed Assets team under RBI Master Directions. Ask to drop added grace period interest. Offer 25% to 35% of the base loan to start.
4Managing Counter-Demands & Credit Committee Approval Matrix
Credila may first offer only 10% to 20% off. Our lawyer replies that funds come from family aid. This moves the Credit Desk to a 40% to 60% waiver.
5Rigorous Forensic Audit of the Official OTS Sanction Letter
Make sure Credila gives an OTS letter on official letterhead. It must list your loan number, settlement sum, and due dates. It must state that all claims are closed.
6Direct Account Remittance, Collateral Retrieval & ₹0 NDC Mandate
Pay the settlement sum directly to your Credila loan via RTGS or NEFT. Get your ₹0 No Dues Certificate. Get your property deeds back. Clear CERSAI records within 30 days.
Navigating Credila Sec 138, Sec 25 PSSA & SARFAESI
When a study loan is unpaid past 60 to 90 days, Credila starts legal steps. The path depends on whether the loan is unsecured or backed by property.
For unsecured loans, Credila issues Section 25 PSSA notices for NACH bounce and Section 138 NI Act notices for cheque bounce. These are 15-day demand letters, not arrest warrants. Replying via a lawyer shows real hardship and sets up OTS talks.
For secured loans, Credila issues demand notices under SARFAESI Section 13(2). Under Section 13(3A), you have 60 days to file a reply. Asking for an OTS in your reply pauses the auction and starts deal talks.
Credila also joins quarterly National Lok Adalat sittings under the Legal Services Authorities Act, 1987. In Lok Adalat, bank teams carry 40% to 60% waiver power. The signed award acts as a Civil Court Decree. It cannot be appealed.
| Resolution Way | Legal Path | Waiver Range | Time Needed | Court Status |
|---|---|---|---|---|
| Direct NBFC OTS | Compromise deal under RBI rules. | 35% – 60% Debt Waiver | 15 to 30 Days | Private deal with ₹0 NDC. |
| National Lok Adalat | Lok Adalat talk before a judge. | 40% – 60% Debt Waiver | Single-day talk | Civil Court Decree. No appeal. |
| SARFAESI 13(3A) Conciliation | Legal reply to stop house auction. | 20% – 35% Debt Waiver | 30 to 60 Days | Mortgage release & deed return. |
| Section 25 / 138 Defense | Defense in court for bounced payments. | 35% – 50% Debt Waiver | 2 to 6 Months | Case closed and withdrawn. |
Authenticating HDFC Credila OTS Sanction Letters
Never pay money on verbal agent claims. If you pay without an official letter, Credila puts the cash toward late fees. Your default stays open on credit files.
Check that your OTS letter is on official HDFC Credila letterhead. It must show their CIN (U67190MH2006PLC159411), office address, loan number, authorized sign, and stamp.
The letter must state that paying the agreed sum clears the full debt. For secured loans, it must promise to return deeds and lift CERSAI marks. Under RBI Circular RBI/2023-24/60, Credila must return deeds within 30 days or pay ₹5,000 per day.
HDFC Credila Post-Settlement CIBIL Trajectory
Since study loans have joint signers, settling updates files for both student and parent. Bureaus list the loan as 'Settled' or 'Post-Write-off Settled' with a ₹0 balance.
Your credit score drops 70 to 120 points at first. You must wait 12 months for new unsecured loans. But a settled status ends monthly default marks on your file.
You can rebuild your score past 750 in 18 to 24 months. Take these four steps:
- • Get a fixed-deposit secured card.
- • Keep card use below 25%.
- • Pay all bills and EMIs on time.
- • Check credit files every 3 months to ensure the loan shows closed.
Why Distressed HDFC Credila Borrowers Trust SettleLoans
Settling a Credila loan takes good math, legal skill, and firm talks. SettleLoans halts agent abuse against parents with legal notices. We defend Section 138 and Section 25 notices. We also pause SARFAESI claims. We talk directly with Credila Credit Desks to get top debt waivers and ₹0 No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: HDFC Credila Education Loan Settlement
What is the HDFC Credila education loan settlement process?
The HDFC Credila loan settlement process is a formal compromise resolution under RBI rules. If you miss payments for 90 days, your account becomes an NPA. You then submit a hardship letter to Credila's Stressed Assets team. Most borrowers secure a 35% to 60% debt waiver for an upfront one-time payment.
How does compound interest during the moratorium affect Credila defaults?
Unpaid simple interest builds up during college and grace periods. Credila adds this interest to your main balance once EMIs start. This extra interest quickly increases your total debt. During OTS talks, we request removing this capitalized interest so you settle on the original disbursed amount.
Can HDFC Credila harass parent co-borrowers or attach pensions?
No. RBI rules and Section 60 CPC protect parents from abuse. Agents cannot call at odd hours, visit workplaces, or threaten arrest. They cannot touch pensions, PF funds, or basic pay. A formal legal notice stops unlawful agent visits right away.
What debt waiver percentage can be negotiated with HDFC Credila?
Unsecured student loans in NPA status usually settle with a 35% to 60% waiver. Secured loans backed by house property settle with a 20% to 35% waiver. The exact discount depends on property value and your financial hardship.
How are secured HDFC Credila loans resolved and property title deeds released?
You can reply to a SARFAESI Section 13(2) notice with a Section 13(3A) petition for an OTS compromise. Under RBI circular rules, Credila must release your original property title deeds within 30 days of full payment.
What legal notices does HDFC Credila issue and how should you reply?
Credila sends Section 138 NI Act notices for bounced cheques and Section 25 PSSA notices for NACH returns. They also send loan recall letters. Legal counsel replies within 15 days to show genuine hardship and open OTS or Lok Adalat talks.
Can an HDFC Credila loan default lead to arrest or travel bans?
No. A loan default is a civil dispute under the Indian Contract Act. The police cannot arrest you or stop you from traveling abroad. Cheque and NACH bounce cases are bailable matters handled in court by advocates.
How does settling an HDFC Credila loan impact CIBIL scores?
Credila reports both student and co-borrower accounts as 'Settled' with a zero balance. Your credit score may fall by 70 to 120 points at first. But it ends negative monthly marks. You can rebuild your credit score back to 750+ within 18 to 24 months.
Who within HDFC Credila has authority to approve an OTS?
Recovery agents have no power to offer discounts. Only Credila's Zonal Stressed Assets Desk or Credit Committee can approve an OTS. You must get an official stamped sanction letter on company letterhead before you pay.
What is the penalty if HDFC Credila delays the No Dues Certificate?
Under RBI Circular RBI/2023-24/60, HDFC Credila must provide a No Dues Certificate and return property deeds within 30 days of payment. Delays beyond 30 days attract a fine of ₹5,000 per day paid directly to the borrower.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements (DOR.STR.REC.20/21.04.048/2023-24).
- RBI Circular RBI/2023-24/60: Release of Property Documents on Loan Repayment.
- HDFC Credila Financial Services Limited: Fair Practices Code & Grievance Redressal Policy.
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Complaint Portal for Recovery Agent Misconduct.
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987 — Lok Adalat.