- Prime Bank Automated Filters: Tier-1 retail banks use automated filters. These tools reject files with 'Settled&apos. or 'Written Off&apos. tags instantly.
- The HFC Approval Channel: NBFCs and HFCs use manual underwriting. They evaluate your current income and SARFAESI property security.
- 24–36 Month Cooling Window: You must build a clean track record for 24 to 36 months. Use secured credit cards and pay on time before applying.
- Status Conversion to 'Closed': Pay the balance haircut to your original lender. They will issue a No Dues Certificate and update CIBIL to 'Closed'.
- Application Structuring: Add a co-applicant with good credit. Put down 25% to 35% margin money and keep your FOIR under 45%.
Why Tier-1 Commercial Banks Instantly Reject Post-Settlement
Many borrowers want to buy a home after settling past debts. Yet, major banks like SBI, HDFC, ICICI, and Axis Bank often reject these loan files. They use automated Straight-Through Processing (STP) systems. These systems pull data from CIBIL, Experian, Equifax, and CRIF High Mark. If the system spots a 'Settled&apos. or 'Written Off&apos. remark, it rejects the file immediately. A human loan officer never even reviews it.
Large banks follow strict Reserve Bank of India provisioning norms. They treat past loan settlements as a direct loss. To them, a past haircut means high credit risk. They may reject long-term home loan requests even if your income is strong now. To get approved, you must explore flexible lending channels.
How Credit Information Companies Record Compromise
Under the Credit Information Companies (Regulation) Act, 2005 (CICRA), banks must report loan statuses accurately. A loan is marked as 'Closed&apos. only if you pay the full dues. In a One-Time Settlement (OTS), the lender reports it as 'Settled&apos. or 'Post-Write-off Settled'. A 'Closed&apos. tag means zero loss for the bank. A 'Settled&apos. tag shows that the lender took a loss on unpaid dues.
Settlement remarks stay on credit bureau records for up to seven years. Your three-digit CIBIL score can recover within 24 to 36 months if you pay on time. However, the 'Settled&apos. tag still triggers automated bank rejections. That is why credit rebuilding and manual underwriting are essential.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Why Secured Residential Mortgages Present Lower Risk
Post-settlement buyers have one big advantage: home loans are secured by property. Personal loans and credit cards have no collateral. If a borrower defaults, banks must file civil suits to recover money. In contrast, home loans fall under the SARFAESI Act, 2002. Under Section 13, lenders can take possession and auction the mortgaged home without slow civil court trials.
Home loans use safe Loan-to-Value (LTV) ratios of 65% to 75%. This lowers the lender's risk of financial loss. Housing Finance Companies rely on this physical collateral. They approve home loans for past settled borrowers who have steady income today.
The Rigorous Two-Year Discipline Roadmap to Rebuild Your
After a settlement, CIBIL scores often drop to 550–650. Applying for fresh loans right away causes hard inquiries and hurts your score. Instead, follow a 24-to-36-month rebuilding plan. Open a fixed deposit of ₹50,000 to ₹1,00,000 to get a secured credit card. Keep your card usage under 25% of the limit. Pay off all bills in full on time to rebuild your score.
Avoid costly instant loan apps and BNPL credit during this recovery phase. Maintain 24 straight months of zero-delay payments. This proves your financial discipline. It can lift your CIBIL score back to 720–760.
Visual Roadmap: From Unsecured Loan Settlement to Residential Mortgage Sanction
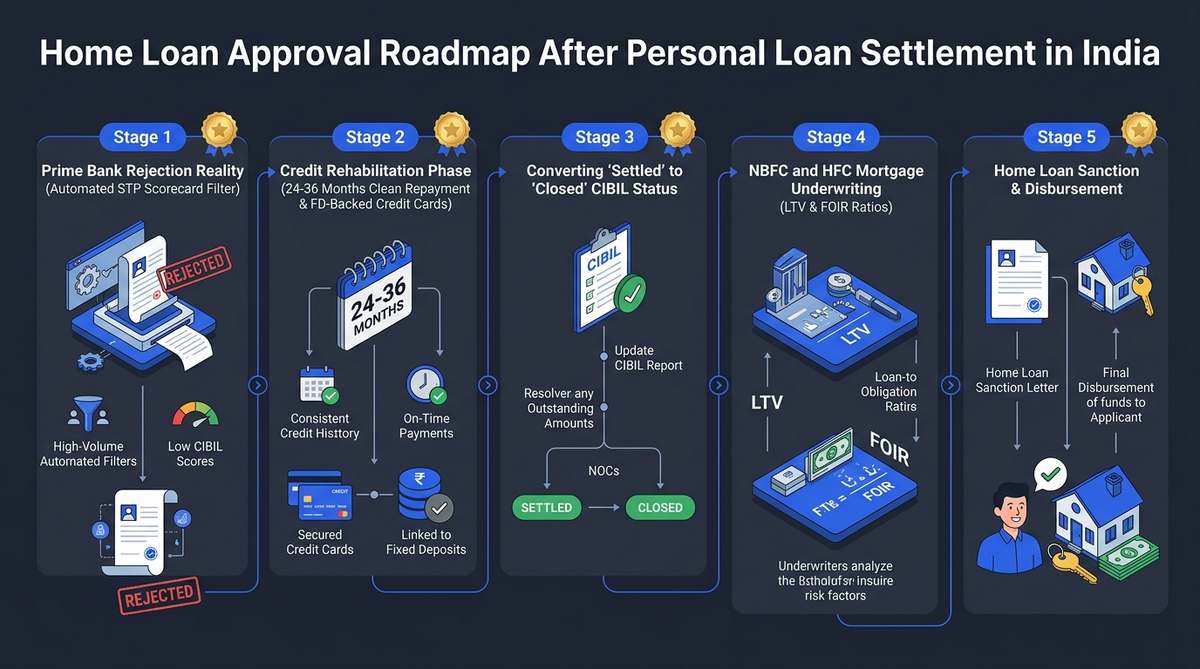
This visual guide outlines your key steps. First, understand bank automated filters. Next, rebuild your credit score. Then, convert your status from 'Settled&apos. to 'Closed&apos. or apply through specialized HFCs.
Converting CIBIL Status to Closed
You can get prime bank home loans at lower repo-linked rates (8.35%–8.75%). To do this, convert your 'Settled&apos. status to 'Closed'. Banking rules allow you to pay back the waived balance amount.
Contact your original lender's Stressed Assets desk. Ask for the exact calculation of the waived amount. Pay this balance through bank channels. The bank will issue a fresh No Dues Certificate. Under Section 21 of CICRA, they will update CIBIL, Experian, Equifax, and CRIF High Mark to 'Closed&apos. within 30 to 45 days. This restores your eligibility for prime home loans.
Navigating NBFC and Housing Finance Company (HFC) Manual
If you cannot repay the waived balance, look at specialized NBFCs and Housing Finance Companies. Lenders like Piramal, PNB Housing, Aadhar, Tata Capital, Home First, and Shriram Housing offer good options. Their loan managers review each case manually. They check your recent bank statements, stable cash flow. And property titles.
Initial HFC interest rates may be 1.5% to 3% higher (10.25%–12.50%). But paying home loan EMIs on time for 36 months can boost your score above 780. You can then transfer the loan to a prime bank at lower interest rates.
Forensic Solvency Math
HFC credit teams check your debt-to-income balance closely. They usually cap your Fixed Obligation to Income Ratio (FOIR) at 40% to 45% of your net monthly income.
Lenders verify your income with audited tax returns. They test your ability to pay EMIs. You should also contribute 25% to 35% as down payment.
Comparative Analysis
Here is how different lenders assess home loan applications after a settlement:
| Lending Channel. | Approval Feasibility. | Mandatory Cooling Period. | Minimum CIBIL Score. | Permissible LTV Cap. | Indicative Interest Spread. |
|---|---|---|---|---|---|
| Prime Commercial Banks (SBI, HDFC, ICICI, Axis). | Very Low (<. 5%) unless converted to 'Closed' | 48 to 60 Months (or post-conversion). | 750+ (No negative remarks). | Up to 80%–85%. | 8.35% – 8.85% p.a. (Repo Linked). |
| Upper-Layer Corporate NBFCs (Tata Capital, Bajaj, Aditya Birla). | Moderate to High (55%–70%) via manual review. | 24 to 36 Months of clean history. | 680 – 730. | Up to 75%. | 9.50% – 11.00% p.a. |
| Specialized Affordable HFCs (Piramal, PNB Housing, Aadhar). | High (75%–85%) with documented cash flows. | 18 to 24 Months. | 630 – 680 (Manual Underwriting). | 65% – 75%. | 10.50% – 12.50% p.a. |
| Joint Co-Applicant Route (Credit-healthy primary co-borrower). | Very High (85%–95%) across institutions. | Immediate to 12 Months. | 760+ (Primary Co-Applicant). | Up to 80%. | 8.50% – 9.50% p.a. |
Applying with a credit-worthy co-applicant is the fastest route to approval. It helps you secure lower interest rates.
Step-by-Step Settlement Blueprint
Prepare your documents before you apply. Gather your Settlement Letter, No Dues Certificate, and 24 months of bank statements. Keep 3 years of ITR or Form 16 ready. Do not apply on multiple loan websites. Too many credit checks hurt your score. Work with loan experts who connect directly with manual credit desks.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: Getting a Home Loan After Loan Settlement
Can I get a home loan in India after settling a personal loan?
Yes. Large banks may reject initial applications. However, NBFCs and Housing Finance Companies (HFCs) approve home loans after 24 to 36 months of clean repayments. You can also qualify faster by converting your status from 'Settled' to 'Closed'.
Why do Tier-1 banks like SBI, HDFC, and ICICI reject home loans after settlement?
Large banks use automated screening systems. These tools automatically reject applications with 'Settled' or 'Written Off' tags without manual review.
How long should I wait after a loan settlement before applying for a home loan?
You should wait 24 to 36 months. Use this time to build a clean repayment record on secured credit cards before applying.
Can I convert my CIBIL status from 'Settled' to 'Closed' to qualify for a home loan?
Yes. Pay the remaining balance to the original lender. The lender will issue an updated No Dues Certificate and update CIBIL to 'Closed' within 30 days.
Which financial institutions offer home loans to applicants with past settled loans?
HFCs and NBFCs like Piramal, PNB Housing, Aadhar Housing, Tata Capital, Home First, and Shriram Housing offer loans. They assess files through manual underwriting.
How does having a credit-healthy co-applicant help in getting a home loan?
Adding a co-applicant with a 750+ CIBIL score adds household income. This lowers lender risk and improves your chances of approval with better interest rates.
What minimum CIBIL score is required for a home loan after loan settlement?
Specialized HFCs accept CIBIL scores between 650 and 720. You need a stable income and a higher down payment of 25% to 35%.
Does a home loan lender have lower risk because the property is mortgaged?
Yes. Home loans are secured under the SARFAESI Act, 2002. If a borrower defaults, the lender has the legal right to recover dues by auctioning the property.
What is the impact of multiple home loan rejections on my credit score?
Multiple loan applications create hard inquiries that lower your credit score. Pre-screening through loan experts helps prevent unwanted score drops.
What documentation is vital when applying for a mortgage post-settlement?
Key documents include your Settlement Letter, No Dues Certificate, 24 to 36 months of bank statements, 3 years of ITR or Form 16, and income proof.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- National Housing Bank (NHB): Housing Finance Companies (HFCs) Regulatory Framework and Fair Practices Guidelines
- Credit Information Companies (Regulation) Act, 2005 (CICRA): Data Reporting, Account Status Rectification &. Dispute Redressal Standards
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Redressal of Credit Information Reporting Delays &. No Dues Certificate Violations
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987. Compoundable Conciliation Framework