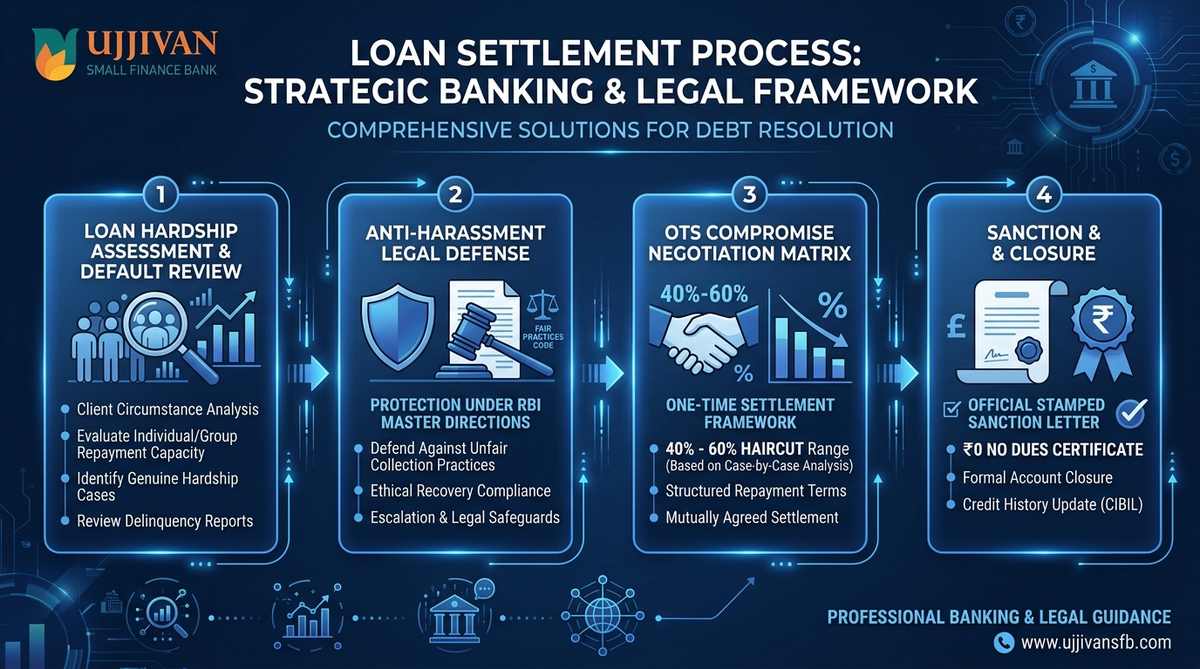
- Statutory OTS Rights: Loan default is a civil matter under the Indian Contract Act, 1872. Distressed borrowers have a right to an RBI compromise OTS.
- Anti-Harassment Shield: RBI 2022 Microfinance Directives ban coercive center meetings. Agents cannot call or visit outside 08:00 AM to 07:00 PM.
- Halting NACH fines: Cancelling e-mandates stops repetitive bank bounce fees. You can get a 100% waiver on all bounce charges.
- 40%–60% Principal Haircuts: Overdue NPA accounts qualify for large debt waivers under Ujjivan SFB board-approved settlement rules.
- 30-Day ₹0 NDC Mandate: Under RBI Circular RBI/2023-24/60, the bank must issue an authentic No Dues Certificate within 30 days.
Understanding Ujjivan Small Finance Bank's Credit
Ujjivan SFB holds a license under Section 22 of the Banking Regulation Act, 1949. It gives personal loans, MSE business credit. And micro loans. If you miss an EMI, recovery starts fast. The bank uses auto-calls. It sends repeated NACH debit hits. Kendra managers also visit in person.
Job loss or medical costs can hurt your budget. Bounce charges and calls cause heavy stress. Remember, loan default is only a civil matter under the Indian Contract Act, 1872. RBI rules protect your basic rights. You can stop bad agent behavior. You can check your loan fees. You can also settle your loan via an official One-Time Settlement (OTS).
Ujjivan SFB Delinquency Lifecycle: SMA to NPA
Ujjivan SFB follows RBI IRACP norms and Ind AS 109 rules. It groups overdue loans by Days Past Due (DPD). Understanding these stages helps you time your settlement for maximum savings.
Early SMA stages focus on clearing unpaid EMIs. After 90 days of default, the loan becomes a Substandard NPA. The bank must now block funds for loan loss provisions. This encourages the bank to agree to a compromise settlement.
| default Classification. | Overdue Days (DPD). | Ujjivan SFB Operational Actions. | Statutory &. Legal Exposure. | Compromise Haircut Scope. |
|---|---|---|---|---|
| SMA-0 (Initial Default). | 1 – 30 Days. | Automated IVR calls, daily SMS alerts. And repeated NACH auto-debit attempts. | No legal action. initial bureau DPD reporting starts. | Negligible (Bank asks for immediate EMI payment). |
| SMA-1 (Mid-Level Arrears). | 31 – 60 Days. | Phone calls from collections, Kendra branch visits. And loan warning notices. | Statutory warning letters. credit score starts to decline. | Low (Tenure changes or EMI pauses considered). |
| SMA-2 (Pre-NPA Alert). | 61 – 90 Days. | Branch manager calls, agency visits. And final loan recall notices. | Section 25 PSSA or Section 138 NI Act 15-day demand notices. | Moderate (Discussions for waiver of penal interest begin). |
| Substandard NPA. | 91 – 180 Days. | Account moves to Stressed Assets Desk. mandatory bank provisioning starts. | Court summons under Section 25 PSSA. Lok Adalat pre-conciliation notices. | High (35%–50% Principal Haircut). |
| Doubtful / Loss Asset. | 181 – 365+ Days. | Heavy provisions set aside. internal write-off review by Credit Committee. | Arbitration notices, civil recovery suits (Order 37 CPC), and Lok Adalat. | Maximum (50%–60% Debt Haircut). |
In Doubtful status, the bank sets aside 50% to 100% of the loan amount. A settlement offers instant cash to the bank. Thus, the Credit Committee readily approves high waivers.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
RBI Protections Against Coercive Collection
Small Finance Banks follow strict RBI guidelines. Under the RBI Microfinance Directions (2022) and Fair Practices Code, agents cannot use force.
Agents may only contact you from 08:00 AM to 07:00 PM. They cannot call relatives, friends, or coworkers. They cannot shout or insult you. All agents must hold IIBF DRA certificates. If agents break rules, file a complaint with Ujjivan SFB's Nodal Officer. You can also report them to the RBI CMS portal.
Stopping Ujjivan SFB Bounce Charges & NACH Hits
Repeated NACH hits cause double bounce fees from your bank and Ujjivan SFB. Under RBI Fair Lending rules (2023), banks cannot compound penal interest. They cannot add penalty fees into your principal.
You can stop these fees easily. Submit a stop-mandate form to your bank under NPCI rules. During settlement talks, your lawyer can get 100% of these bounce fees waived.
Ujjivan SFB One-Time Settlement (OTS)
Ujjivan SFB reviews settlement offers using Net Present Value (NPV) under RBI Master Directions (DOR.STR.REC.20/21.04.048/2023-24). Unsecured loans have no collateral. Hence, instant cash recovery helps the bank avoid long, costly court battles.
Here C_t means estimated cash recovery over time t. The symbol r is the discount rate. Deductions cover court fees, lawyer costs. And blocked bank capital under Ind AS 109 rules.
Realistic Ujjivan SFB Settlement Haircut Slabs by Product & Aging
| Credit Facility Type. | default Aging Category. | Penal &. Bounce Waiver. | Principal Haircut Range. | Recommended Opening Offer. |
|---|---|---|---|---|
| Ujjivan Unsecured Personal Loan. | 90 – 180 Days (Substandard NPA). | 100% Full Waiver. | 30% – 45% Principal Waiver. | Offer 40%–50% of Core Ledger Dues. |
| Ujjivan Unsecured Personal Loan. | 181 – 365+ Days (Doubtful Asset). | 100% Full Waiver. | 45% – 60% Principal Waiver. | Offer 35%–40% of Core Ledger Dues. |
| Ujjivan Micro &. Small Enterprise (MSE) Loan. | 90 – 180 Days (Substandard NPA). | 100% Full Waiver. | 30% – 45% Principal Waiver. | Offer 45%–55% of Principal Outstanding. |
| Ujjivan Micro &. Small Enterprise (MSE) Loan. | 180+ Days (Written-Off / Doubtful). | 100% All Penal Charges. | 50% – 65% Principal Waiver. | Offer 30%–35% of Total Principal Dues. |
| Ujjivan Group / Micro-Banking Loan. | 90 – 365+ Days (Insolvent Group / JLG). | 100% Full Waiver. | 45% – 65% Principal Waiver. | Offer 30%–40% of Pro-Rata Liability. |
Ujjivan Small Finance Bank Loan Settlement & Legal Defense Blueprint
Step-by-Step Guide to a Compromise Settlement with Ujjivan
Settling a defaulted loan with Ujjivan Small Finance Bank involves six simple steps:
1Hardship Dossier Compilation
Gather proof of money loss. Collect medical bills, job layoff letters, or low bank records. This shows genuine hardship under RBI rules.
2Mandate Revocation & Formal Communication
Stop e-NACH auto-debits at your bank to avoid return fees. Send a written letter to Ujjivan SFB. Route all talks through your lawyer.
3Submitting Compromise Proposal
Send an OTS letter to Ujjivan SFB Stressed Assets Desk. Quote RBI settlement rules. Offer 25% to 35% of dues with zero penal fees.
4Credit Committee Negotiation
Our legal team negotiates firmly with the bank. We show funds come from family help. We push for 40% to 60% principal waivers.
5Forensic Sanction Letter Audit
We inspect the bank sanction letter. We verify the loan number, agreed amount, due date. And full debt discharge.
6Remittance & ₹0 NDC Enforcement
Pay the settled sum straight to your Ujjivan SFB loan account. Under RBI rules (RBI/2023-24/60), the bank must issue your No Dues Certificate in 30 days.
Navigating Ujjivan Bank Sec 25 PSSA & Lok Adalat
Ujjivan SFB may send Section 25 PSSA notices for failed NACH debits. They may also send Section 138 NI Act notices for bounced cheques. These are not arrest warrants. A timely legal reply within 15 days helps start settlement talks.
If the bank names a private arbitrator on its own, your lawyer can object. Section 12 and 14 of the Arbitration Act and Supreme Court rulings (Perkins Eastman and TRF Ltd.) protect you. Settle at a National Lok Adalat to get a final court order with 40% to 60% debt relief.
| Resolution Avenue. | Legal Mechanism. | Haircut Potential. | Typical Timeline. | Judicial Finality. |
|---|---|---|---|---|
| Direct SFB OTS. | Compromise agreement under RBI Master Directions. | 40% – 60% Debt Haircut | 15 to 30 Days. | Binding private contract with ₹0 NDC. |
| National Lok Adalat. | Judicial conciliation before sitting judge and panel. | 45% – 60% Debt Haircut | Single-day session. | Civil Court Decree (Zero appeal). |
| Arbitration Defense. | Contesting one-sided arbitrator appointments. | Variable (Converts to OTS). | 3 to 9 Months. | Subject to Section 34 challenge. |
| Section 25 / 138 Defense. | Magistrate court compoundable actions defense. | 35% – 50% Debt Haircut | 2 to 6 Months. | Formal withdrawal and case disposal. |
Authenticating Ujjivan SFB Settlement Letters
Never pay money based on oral promises or phone chats. Always demand an official OTS letter. Check the Ujjivan SFB letterhead, CIN number, reference code. And branch seal.
The letter must confirm full debt closure. Under RBI Circular RBI/2023-24/60, the bank must give your No Dues Certificate in 30 days. Any delay costs the bank ₹5,000 per day paid to you.
Ujjivan Bank Post-Settlement CIBIL Recovery
After you pay, Ujjivan SFB marks your file as 'Settled' with a ₹0 balance in credit bureaus (CIBIL, Experian, Equifax, CRIF High Mark). This ends default marks and removes all legal threats.
You can raise your credit score past 750 in 18 to 24 months. Use a fixed-deposit credit card. Keep card spends below 25%. Pay all bills on time every month.
Why Distressed Ujjivan SFB Borrowers Trust SettleLoans
Settling loan debt needs skilled legal help. SettleLoans stops agent calls and home visits with legal notices. We handle Section 25 PSSA court notices. We block illegal arbitration. We talk with Ujjivan SFB Stressed Assets teams to win up to 60% waivers and valid ₹0 No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: Ujjivan Small Finance Bank Loan Settlement
What is the Ujjivan Small Finance Bank loan settlement process and how does it work?
Ujjivan SFB loan settlement is a formal process. It follows RBI Master Directions on Compromise Settlements. After 90 days of default, a loan turns into an NPA. You then submit a hardship letter to the Stressed Assets Desk. The bank checks the case using Net Present Value (NPV). Next, Ujjivan SFB issues a stamped OTS Sanction Letter for a reduced sum. Paying this amount clears all dues. The bank then gives you a No Dues Certificate (NDC).
How does RBI regulate Ujjivan SFB recovery practices on group and microfinance loans?
The RBI Microfinance Directions (2022) ban harsh recovery. Agents cannot visit you before 08:00 AM or after 07:00 PM. They cannot use foul words or hold public protests. They cannot call relatives or disturb your work. If agents break rules, complain to Ujjivan SFB's Principal Nodal Officer. You can also file a case on the RBI CMS portal.
Can Ujjivan Small Finance Bank file criminal charges or arrest a defaulting borrower?
No. Unsecured loan default is a civil matter under the Indian Contract Act, 1872. Police cannot arrest you or file an FIR for loan default. The bank may send notices under Section 25 PSSA for failed auto-debits. These are court notices that can be settled easily through advocate help and an OTS.
What percentage of debt waiver or haircut can you realistically negotiate with Ujjivan SFB?
You can get a 40% to 60% waiver on total loan dues. The discount depends on default age and income loss. When a loan is overdue past 180 to 365 days, the bank sets aside high provisions. This allows the bank to give deep principal waivers and waive 100% of all extra fees.
How can borrowers halt repeated Ujjivan SFB NACH bounce charges and debit sweeps?
Stop bounce charges in three easy steps. First, submit a stop-mandate form to your bank under NPCI rules. Second, write to Ujjivan SFB to pause auto-debits due to hard times. Third, ask for a 100% waiver of all bounce charges during OTS talks under RBI rules.
What should you do if you receive a Section 25 PSSA or arbitration notice from Ujjivan SFB?
Reply to a Section 25 PSSA demand notice within 15 days. State your financial troubles and propose an OTS. If the bank starts private arbitration alone, challenge it under Section 12 and 14 of the Arbitration Act. Use Supreme Court rulings (Perkins Eastman and TRF Ltd.) to move the case to Lok Adalat or direct settlement.
How are group loan (JLG) defaults handled when other group members refuse or cannot pay?
In group loans (JLG), field agents often try group pressure. But RBI 2022 rules strictly ban social shaming. If group members default, hire a loan lawyer. Your lawyer will split your share, show your financial proof, and settle your part directly with Ujjivan SFB.
Who within Ujjivan Small Finance Bank has the legal authority to sanction an OTS?
Call center staff and recovery agents cannot approve loan waivers. Large waivers of 40% to 60% need approval from Ujjivan SFB's Stressed Assets Desk, Regional Credit Committee, or Zonal Head. The approval must be a stamped letter on bank letterhead.
How does settling an Ujjivan SFB loan impact your CIBIL score and credit history?
After you pay the settlement, Ujjivan SFB reports your loan as 'Settled' with a ₹0 balance to CIBIL, Experian, Equifax, and CRIF High Mark. Your score drops initially by 75 to 150 points. But it stops overdue marks and ends legal risk. You can rebuild your score past 750 in 18 to 24 months.
How long does Ujjivan Small Finance Bank take to issue the No Dues Certificate post-settlement?
Under RBI Circular RBI/2023-24/60, Ujjivan SFB must issue your No Dues Certificate (NDC) within 30 days of full payment. If the bank delays without a valid reason, it must pay you ₹5,000 per day of delay.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Master Direction: Regulatory Framework for Microfinance Loans, 2022 &. Guidelines on Recovery Agents
- Ujjivan Small Finance Bank Limited: Customer Grievance Redressal Policy, Fair Practice Code &. Principal Nodal Officer Matrix
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online Portal for Complaints on Bank Harassment, Excessive Bounce Fees &. NDC Delays
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987. National Lok Adalat Conciliation Framework