- Civil Dispute Rights: Loan default is a civil issue under the Indian Contract Act, 1872. Banks cannot arrest you. They cannot seize assets without court orders.
- Local Court Defense: We defend Section 138 NI Act notices in local courts. We defend Section 25 PSSA summonses too. We turn them into OTS terms.
- DLSA Lok Adalat Decrees: National Lok Adalats grant binding Civil Court Decrees. Borrowers get 40% to 60% principal waivers.
- Waiver of Penal Charges: Under RBI rules, banks waive 100% of penal interest. They also waive e-NACH bounce fees.
- Guaranteed ₹0 NDC: Under RBI Circular RBI/2023-24/60, banks must issue your NDC in 30 days. Daily fines apply if they delay.
Debt Landscape & Crisis in Vijayawada
Vijayawada and Guntur form the trade hub of Andhra Pradesh. Business thrives in Gollapudi Market and Guntur Mirchi Yard. Auto Nagar hosts major transport hubs. The CRDA corridor houses salaried professionals. When payments stall, cash flow drops fast. Many traders and workers struggle with high EMIs.
Traders rely on credit lines from major banks like HDFC, ICICI, Axis, and SBI. When market payments stall, debt piles up fast. Fleet owners face freight slowdowns. Salaried staff face pressure from cards and personal loans.
Unpaid unsecured debt is a civil breach under the Indian Contract Act, 1872. Borrowers hold rights under RBI Master Directions and High Court rulings. You can stop collection harassment. You can audit penal charges and secure a One-Time Settlement (OTS).
Statutory Civil Protections & RBI Anti-Harassment Directives
When EMIs bounce, banks assign accounts to collection agencies. In Vijayawada, agents often cross legal lines. They call repeatedly. They visit shops in Gollapudi or Auto Nagar during work hours. Some try calling relatives or bosses.
The RBI Master Direction on Recovery Agents sets clear rules to protect borrowers:
- Strict Calling Hours: Agents may only call between 8:00 AM and 7:00 PM.
- No Workplace Intrusion: Calling employers, coworkers, or relatives is illegal.
- No Threats or Force: Agents cannot use threats, abuse, or sit-ins.
- Mandatory ID: Agents must carry bank ID cards and valid DRA certificates.
Loan default is not a crime. Banks cannot file police FIRs for unpaid debts. The Supreme Court confirmed that civil debt cannot be turned into criminal cases. If agents cross legal lines, our lawyers issue cease-and-desist notices to bank nodal officers. We also file complaints with the RBI Ombudsman.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Delinquency Lifecycle & Bank Balance-Sheet Accounting
Overdue loans follow RBI asset classification rules (IRACP) and Ind AS 109. Financial institutions track overdue loans across Days Past Due (DPD) tiers. Knowing this timeline helps lawyers negotiate when banks are most ready to settle.
In SMA-0 and SMA-1 stages, banks demand full dues. After 90 days, the loan becomes an NPA. The bank must set aside cash reserves. Its focus shifts from monthly collection to bad-debt recovery.
| default Category. | Overdue Days (DPD). | Bank Recovery Actions in Vijayawada. | Local Judicial &. Legal Exposure. | Target OTS Haircut Range. |
|---|---|---|---|---|
| SMA-0 (Early Stage). | 1 – 30 Days. | Automated reminder SMS. Payment reminder calls. | No court cases. Early credit bureau reporting. | Low. Bank demands full EMI payment. |
| SMA-1 (Mid Stage). | 31 – 60 Days. | Agent calls. Loan recall warning letters. | Warning letters. Credit score drops. | Low. Loan restructuring may be discussed. |
| SMA-2 (Pre-NPA Stage). | 61 – 90 Days. | Final loan recall notice. Legal action warnings. | Section 138 / Section 25 notice warnings. | 15% – 25% Principal Waiver. |
| NPA – Sub-Standard. | 91 – 365 Days. | Recovery agency handoff. Demand legal notices. | Section 138 summons. DLSA Lok Adalat notices. | 35% – 50% Principal Waiver. |
| Doubtful &. Loss Asset. | 365+ Days / Written-off. | Assigned to Zonal Stressed Assets desks. | Arbitration notices. Final Lok Adalat session. | 50% – 65% Principal Waiver. |
In Doubtful or write-off stages, banks absorb loan losses. An upfront lump-sum brings instant cash. This motivates bank committees to approve 50% to 60% principal waivers.
NPV Valuation Mechanics in Vijayawada
Banks review settlement offers using RBI NPV rules. Unsecured debts carry no collateral. Banks compare instant cash against slow court battles.
Civil suits under Order 37 CPC take 3 to 7 years in court. They require heavy legal fees and tie up bank capital. An immediate settlement delivers higher net cash value.
Here, C_t is recovered cash. The letter r is discount rate. Deductions cover court costs and locked capital.
Realistic Settlement Haircut Slabs by Product & Aging in Vijayawada
| Credit Facility Category. | default Aging. | Penal &. Bounce Waiver. | Principal Haircut Range. | Target Settlement Offer. |
|---|---|---|---|---|
| Unsecured Personal Loan. | 90 – 180 Days (NPA). | 100% Full Waiver. | 30% – 45% Principal Waiver. | Pay 40%–50% of Core Dues. |
| Unsecured Personal Loan. | 181 – 365+ Days (Doubtful). | 100% Full Waiver. | 45% – 60% Principal Waiver. | Pay 35%–40% of Core Dues. |
| Unsecured Business Loan (Traders/Fleet). | 90 – 180 Days (NPA). | 100% Full Waiver. | 30% – 45% Principal Waiver. | Pay 45%–55% of Drawn Dues. |
| Credit Card Debt &. Instant App Loans. | 180+ Days (Written Off). | 100% All Penal Charges. | 50% – 65% Principal Waiver. | Pay 30%–35% of Total Dues. |
Vijayawada Loan Settlement & Debt Defense Roadmap
Defending Sec 138 & Sec 25 in Vijayawada
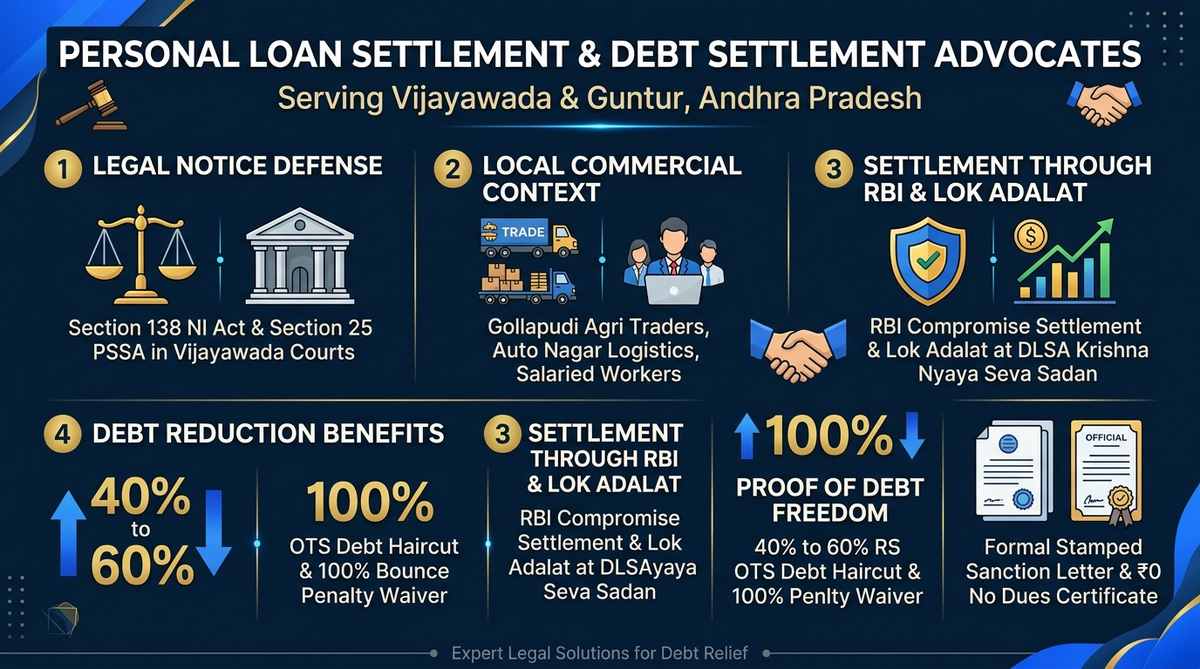
Defaults past 60 to 90 days trigger legal demand notices. Lenders issue notices under Section 138 of the Negotiable Instruments Act, 1881 for bounced cheques. They also use Section 25 of the PSSA for failed NACH mandates. Some lenders send arbitration notices naming sole arbitrators in distant cities.
A 15-day legal notice is not an arrest warrant. It gives you time to reply and settle. If ignored, lenders file cases in local Magistrate Courts. A formal legal reply establishes financial hardship. It stops auto-debit sweeps and opens settlement talks.
one-sided arbitration without consent is illegal. The Supreme Court confirmed this in Perkins Eastman and TRF Ltd. Our advocates challenge biased arbitrators under Section 12 and Section 14 of the Arbitration Act. This halts unfair hearings and brings the bank to terms.
Settling via National Lok Adalat in Vijayawada
National Lok Adalat is a fast, safe way to settle debts. It is run quarterly by the District Legal Services Authority (DLSA Krishna and DLSA Guntur) under the Legal Services Authorities Act, 1987.
Senior bank officers attend Lok Adalat with direct settlement authority. Under RBI rules, they can offer large debt waivers. Borrowers often get 40% to 60% principal write-offs. Banks also waive 100% of penal interest and legal costs.
The settlement signed before the bench becomes an official Lok Adalat Award. Under Section 21 of the Legal Services Authorities Act, 1987, it equals a Civil Court Decree. It is final. No appeal lies against it. It ends all Section 138 and Section 25 cases permanently.
Negotiating Loan Settlements in Vijayawada
Securing an optimal One-Time Settlement follows six clear, legal steps:
1Comprehensive Financial Hardship Dossier Compilation
Collect clear proof of financial distress. Traders and fleet owners can share tax returns and loss sheets. Bank records also help prove distress. Salaried staff can share job loss letters, pay cuts, or medical bills.
2Revoking e-NACH Mandates & Issuing Legal Anti-Harassment Notices
Stop active e-NACH mandates at your bank under NPCI guidelines. This prevents repeated bounce fees. Our legal team also sends formal notices to recovery desks. This stops direct home and office visits under RBI rules.
3Submitting Formal Hardship Petition to Zonal Stressed Assets Desks
Submit a formal settlement offer to the bank Stressed Assets desk. We cite RBI Master Directions. We offer 25% to 35% of total dues.
4Managing Counter-Demands & Structuring Credit Committee Approvals
Banks usually offer a small discount at first. We show that funds come from friendly family loans. This guides the Credit Committee to approve 40% to 60% waivers.
5Rigorous Forensic Audit of the OTS Sanction Letter
Do not make payments without an official approval letter. Our advocates inspect the bank letterhead, account numbers. And due dates. We ensure terms for full debt closure.
6Direct Account Remittance & Enforcing ₹0 NDC Delivery
Pay the agreed settlement sum via RTGS or NEFT. Under RBI circular RBI/2023-24/60, the bank must issue your ₹0 NDC within 30 days.
Sanction Letter Audit & NDC in Vijayawada
Beware of fake settlement scams by rogue collection agents. Some agents issue fake letters to collect cash. If you pay without official approval, the bank treats it as partial payment. The loan stays open. Penalty interest keeps growing.
Always demand an official OTS letter on bank letterhead. It must show registered office details and branch seals. It must confirm that the loan will close with zero balance.
After payment, credit bureaus mark your account as 'Settled' with a ₹0 balance. Your credit score drops at first. However, monthly default marks stop for good. Rebuild your score above 750 in 18 to 24 months with a secured card.
Comparative Resolution Matrix in Vijayawada
Compare common legal debt relief options in Vijayawada and Guntur:
| Resolution Pathway. | Legal Mechanism. | Haircut Potential. | Typical Timeline. | Judicial Finality. |
|---|---|---|---|---|
| Direct Bank OTS. | Compromise pact under RBI Master Directions. | 40% – 60% Debt Haircut | 15 to 30 Days. | Binding agreement with ₹0 NDC. |
| National Lok Adalat. | Settlement before DLSA Krishna or Guntur bench. | 45% – 60% Debt Haircut | Single-day session. | Civil Court Decree (Non-appealable). |
| Arbitration Defense. | Challenge sole arbitrator under Section 12. | Converts to bank OTS. | 3 to 9 Months. | Subject to Section 34 challenge. |
| Section 138 / 25 Defense. | Court defense in compoundable cheque bounce cases. | 35% – 50% Debt Haircut | 2 to 6 Months. | Formal case withdrawal and closure. |
Why Borrowers in Vijayawada Choose SettleLoans
Handling recovery agents and legal notices requires strong legal support. SettleLoans protects borrowers across Andhra Pradesh. We stop harassment with legal notices. We defend Section 138 and Section 25 cases in local courts. We represent you in DLSA Lok Adalat sessions. Our advocates negotiate directly with bank Stressed Assets desks for maximum debt waivers and verified ₹0 NDCs.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Vijayawada
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Vijayawada can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Gandhinagar, Near Sub Collector Office, Vijayawada, Andhra Pradesh - 520003
Jurisdiction: Exercises criminal and civil jurisdiction over electronic mandate defaults under Section 25 PSSA and summary recovery suits across Krishna and NTR districts.
Address: Nyaya Seva Sadan, Metropolitan Court Premises, Gandhinagar, Vijayawada - 520003
Lok Adalat Conciliation: Special dispute benches offer legally binding compromise decrees for agricultural and unsecured personal loan defaults under Andhra Pradesh legal aid provisions.
FAQs: Personal Loan Settlement in Vijayawada
Why do borrowers in Vijayawada need specialized debt settlement advocates instead of local recovery middlemen?
Unsecured debt is a civil contract issue. Middlemen lack legal power to settle loans. Certified advocates send legal replies to bank nodal officers. They defend Section 138 and Section 25 PSSA court notices. They negotiate 40% to 60% OTS debt waivers directly with bank committees.
How does the commercial ecosystem in Vijayawada and Guntur influence bank settlement negotiations?
Trade delays in Gollapudi and Mirchi Yard cause sudden cash crunches. Lenders know these delays are not willful defaults. Sharing GST filings and bank records helps bank committees approve big debt write-offs.
What legal protections exist against aggressive bank recovery agents visiting homes or workplaces in Vijayawada?
Under RBI rules, recovery agents may only call between 8:00 AM and 7:00 PM. Visiting shops to intimidate is illegal. Calling family or employers is also barred. Borrowers can report violations to the RBI Ombudsman.
Can a private bank or NBFC file a police FIR or arrest a borrower for personal loan default in Vijayawada?
No. Loan default is a civil issue under the Indian Contract Act, 1872. Police cannot register FIRs or arrest borrowers for unpaid loans. Section 138 NI Act and Section 25 PSSA cases are bailable matters in magistrate courts.
How do National Lok Adalats organized by DLSA Krishna and Guntur resolve personal loan disputes?
DLSA Krishna and Guntur hold quarterly National Lok Adalats. Bank officers attend with full authority to offer 40% to 60% debt waivers. The Lok Adalat award is final. It acts as a Civil Court Decree.
What percentage of loan waiver can borrowers in Vijayawada realistically negotiate on personal loans?
For accounts overdue past 90 days, borrowers can secure a 40% to 60% principal waiver. Banks also waive 100% of penal interest, late fees, and bounce charges.
How should borrowers in Vijayawada respond to Section 138 NI Act or Section 25 PSSA legal notices?
Do not ignore Section 138 or Section 25 notices. An advocate files a formal reply within 15 days. This reply proves financial hardship and starts OTS negotiations.
How can borrowers prevent continuous NACH auto-debit bounce charges across Vijayawada bank accounts?
You can stop NACH bounce fees by giving a written cancellation to your bank under NPCI rules. Our advocates also demand a full waiver of past bounce fees during OTS talks.
How does personal loan settlement affect credit bureau scores and what is the recovery timeline in Andhra Pradesh?
Your loan status updates to 'Settled' with a ₹0 balance. The score drops initially. However, using a secured credit card restores your score above 750 within 18 to 24 months.
What is the statutory deadline for banks to issue the No Dues Certificate (NDC) post-settlement in Vijayawada?
Under RBI Circular RBI/2023-24/60, banks must deliver an NDC within 30 days of payment. Any delay requires the bank to pay ₹5,000 daily compensation.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- High Court of Andhra Pradesh: Judicial Directives on Civil Debt Recovery, Section 138 NI Act Conciliation &. Lok Adalat Precedents
- Andhra Pradesh State Legal Services Authority (APSLSA): DLSA Krishna &. Guntur National Lok Adalat Dispute Resolution Framework
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online CMS Portal for Andhra Pradesh Banking &. Recovery Agent Harassment Complaints
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987. Pre-Litigation Conciliation Guidelines