- Legal Compromise Rights: Loan default is a civil matter under the Indian Contract Act, 1872. Borrowers can seek an RBI One-Time Settlement (OTS).
- Harassment Shield: Aggressive collection tactics violate the RBI Fair Practices Code. We stop them with legal cease-and-desist notices.
- 45%–65% Debt Waivers: After 90 days of default, banks must set aside cash reserves. Lenders offer 45% to 65% principal waivers to settle bad loans.
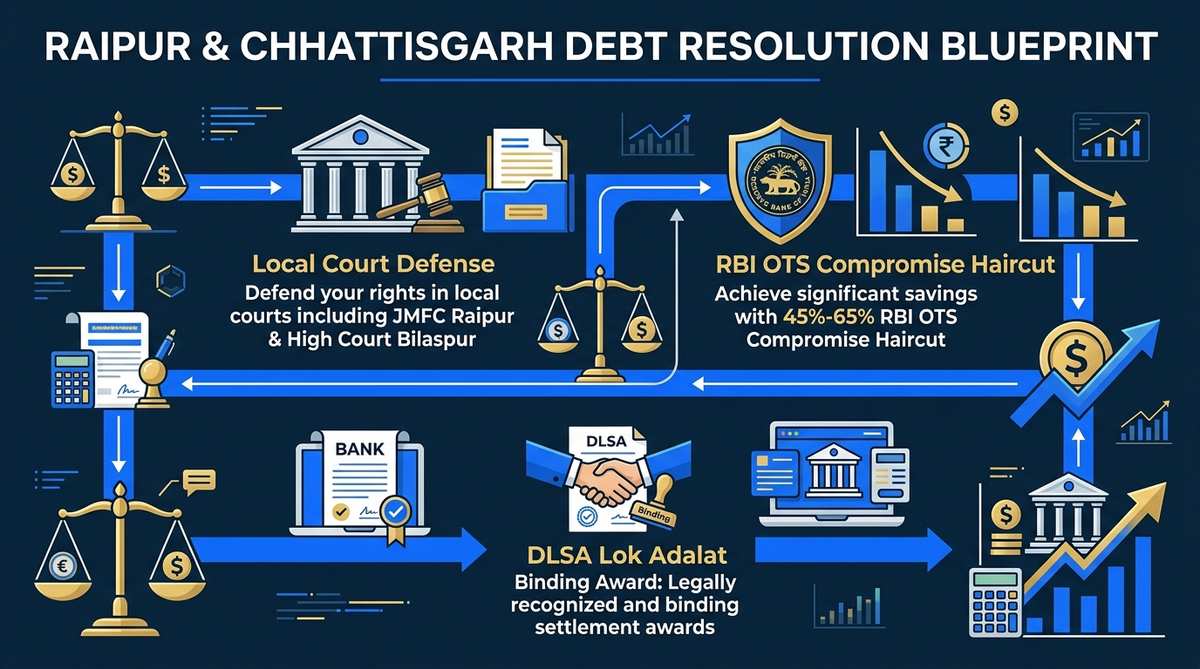
- Raipur Court Defense: Our advocates handle Section 138 NI Act and Section 25 PSSA notices in JMFC Raipur. We secure binding Lok Adalat decrees.
- Guaranteed ₹0 NDC: Under RBI Circular RBI/2023-24/60, banks must deliver your No Dues Certificate in 30 days or pay ₹5,000 daily fines.
Debt Default Dynamics in Raipur & Bhilai
Raipur is the business center of Chhattisgarh. It connects with Bhilai-Durg and Bilaspur. The area has steel mills in Urla and Siltara. It also has cloth markets in Pandri and Gol Bazar. Many residents in Shankar Nagar and Devendra Nagar use personal loans and credit cards.
Shifts in business cycles can cause cash shortages. When earnings fall, borrowers struggle to pay EMIs. Late fees and NACH bounce charges add up quickly. Defaulting due to financial loss is purely a civil matter. Borrowers can use RBI compromise settlements to resolve debts legally.
Delinquency Timeline & NPA Rules in Raipur
Overdue loans follow strict RBI (IRACP) rules and Ind AS 109. Lenders track loans in Special Mention Account tiers. These tiers are SMA-0 (1–30 days), SMA-1 (31–60 days), and SMA-2 (61–90 days). After 90 days, the loan turns into a Non-Performing Asset (NPA).
| default Stage. | Overdue Duration. | Regulatory Accounting Status. | Typical Institutional Actions. | Settlement Leverage. |
|---|---|---|---|---|
| SMA-0. | 1 – 30 Days. | Standard Asset. internal risk flag. | Automated SMS, phone calls, payment reminders. | Low (Restructuring or tenure extensions). |
| SMA-1. | 31 – 60 Days. | Early Warning. heightened credit risk. | Frequent calls, repeated NACH mandate presentations. | Moderate (Waiver of penal interest and late fees). |
| SMA-2. | 61 – 90 Days. | Imminent Default. balance sheet stress. | Demand notices, field agent visits. | Increasing (Initial compromise settlement proposals). |
| Gross NPA. | 91 – 180 Days. | Sub-Standard Asset. 15% reserve required. | Section 138 NI Act and Section 25 PSSA notices. | High (35%–50% Principal Haircut). |
| Doubtful / Loss. | 181 – 365+ Days. | High-Provisioning. technical write-off. | Civil recovery suits (Order 37 CPC), Lok Adalat. | Maximum (50%–65% Principal Waiver). |
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Defending Against Recovery Harassment in Raipur
Recovery agents in Raipur often use harsh tactics. Borrowers face unannounced visits and false threats. Under RBI rules on recovery agents, collectors must follow strict rules:
- Strict Permissible Hours: Agents can only call or visit between 8:00 AM and 7:00 PM.
- No Third-Party Contact: Contacting bosses, coworkers, neighbors, or relatives violates RBI privacy rules.
- No Threats or Force: Abusive language and false police threats are illegal under the Bharatiya Nyaya Sanhita (BNS).
- Mandatory Identification: Agents must carry valid bank ID cards and formal authorization letters.
Lenders also present NACH mandates repeatedly against empty accounts. This causes heavy bounce fees. Under NPCI rules, you can ask your bank in Raipur to cancel the e-NACH mandate. In settlement talks, our lawyers demand a 100% waiver of all bounce fees.
RBI Compromise Rules & NPV in Raipur
Under RBI Master Direction DOR.STR.REC.20/21.04.048/2023-24, banks set compromise policies. Unsecured loans have no collateral under SARFAESI. Banks compare settlement offers to the Net Present Value (NPV) of court recovery.
Where C_t is estimated recovery, r is discount rate. And deductions cover legal costs and locked capital.
Court cases in Raipur take years to resolve. They cost banks high legal fees and lock up capital in bad loan reserves. An immediate 45% to 65% settlement gives banks better net value than long court battles.
Realistic Loan Settlement Haircut Slabs for Raipur & Chhattisgarh Borrowers
| Debt Category. | default Bucket. | Penal &. Bounce Waiver. | Principal Haircut Range. | Optimal Settlement Target. |
|---|---|---|---|---|
| Unsecured Personal Loan. | 90 – 180 Days (NPA). | 100% Complete Waiver. | 35% – 50% Principal Waiver. | Pay 45%–55% of Core Principal. |
| Unsecured Personal Loan. | 180 – 365+ Days (Written Off). | 100% Complete Waiver. | 50% – 65% Principal Waiver. | Pay 35%–45% of Core Principal. |
| Credit Card Outstanding. | 90 – 180+ Days (NPA). | 100% Interest &. Late Fees. | 55% – 70% Total Waiver. | Pay 30%–40% of Total Dues. |
| MSME Business Credit Line. | 90 – 180 Days (NPA). | 100% All Penal Charges. | 35% – 50% Principal Waiver. | Pay 45%–55% of Disbursed Dues. |
| Fintech Instant Loan App. | 60 – 180+ Days (Default). | 100% Compound Fees. | 50% – 65% Principal Waiver. | Pay 35%–45% of Net Principal. |
Raipur Personal Loan Settlement & Lok Adalat Legal Defense Blueprint
Sec 138 NI Act & Sec 25 Defense in Raipur Courts
During long defaults, lenders file cases in the District Court Complex near Kalibadi. These go before the Judicial Magistrate First Class (JMFC) in Raipur. Lenders file under Section 138 of the NI Act for cheques. They file under Section 25 of the PSSA for failed NACH debits.
A court summons is not an arrest warrant. Under the CrPC and Bharatiya Nagarik Suraksha Sanhita (BNSS), these are bailable matters. Our advocates represent you in court. We secure bail without jail risk. We challenge wrongful charges and seek formal settlement.
Under Section 147 of the NI Act, courts can record mutual settlements. The High Court of Chhattisgarh at Bilaspur supports civil settlement for loan disputes.
Settling via National Lok Adalat
The DLSA Raipur holds National Lok Adalats each quarter at the District Court. Under the Legal Services Authorities Act, 1987, Lok Adalat offers a legal platform to compromise.
Our lawyers present proof of your financial hardship. The bench helps negotiate fair debt waivers. Once signed, the panel issues a Lok Adalat Award. This award has the force of a Civil Court Decree under Section 21 of the Act. It closes the loan permanently.
6-Phase Debt Settlement Protocol in Raipur
SettleLoans executes a disciplined 6-phase resolution strategy tailored to Chhattisgarh's legal and commercial landscape:
1Financial Forensic Audit
We audit your loan agreements and statements. We separate the true principal from unfair penal charges and illegal fees.
2Anti-Harassment Legal Shield
We issue formal legal notices under the RBI Fair Practices Code. This redirects all collection calls to your appointed lawyer.
3Halting NACH Auto-Debits
We help you cancel e-NACH mandates at your bank under NPCI rules. This stops ongoing bounce fees and protects your funds.
4Zonal Committee Negotiations
We bypass recovery agents and negotiate directly with bank Zonal Committees using documented hardship files under RBI rules.
5Sanction Letter Verification
Our banking lawyers audit the OTS sanction letter. We check official letterheads, correct loan details. And legal case withdrawal clauses.
6Direct Remittance & ₹0 NDC Enforcement
You pay the settlement sum directly to your loan account via RTGS/NEFT. We secure your zero-balance No Dues Certificate within 30 days.
Sanction Letter Audit & NDC in Raipur
Borrowers must avoid fake settlement letters from recovery agents. Your lawyer verifies key terms before you pay:
- Official Bank Letterhead: The letter must display the bank CIN, official address. And authorized seal.
- Clear Account Details: It must state the borrower PAN, loan account numbers. And total dues.
- Exact Settlement Terms: It must show the agreed payment amount, payment modes. And strict deadlines.
- Legal Case Withdrawal Clause: The letter must confirm the withdrawal of all court cases upon payment.
Under RBI Circular RBI/2023-24/60, banks must issue your NDC within 30 days. Any delay brings a penalty of ₹5,000 per day payable to you.
Post-Settlement CIBIL Recovery in Raipur
Settling a loan updates your credit bureaus to 'Settled' with a ₹0 balance. This causes an initial drop of 75 to 150 points. However, monthly default marks and legal risks stop immediately.
You can rebuild your CIBIL score above 750 in 18 to 24 months with good habits:
- Secured Credit Card: Get a card backed by a small fixed deposit.
- Low Credit Usage: Keep your monthly card usage between 15% and 25% of the credit limit.
- Timely Payments: Pay 100% of your card bill on time every month.
- Check Credit Reports: Review your credit profile to verify that your old loan balance shows zero.
Why Borrowers in Raipur & Chhattisgarh Choose SettleLoans
Disputes and court notices need skilled legal support. SettleLoans helps workers and business owners across Raipur, Bhilai, Durg, and Bilaspur. We stop harassment. We defend court notices in JMFC court. We also attend DLSA Lok Adalat to secure maximum loan waivers.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Raipur
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Raipur can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Collectorate Parisar, Ghadi Chowk, Raipur, Chhattisgarh - 492001
Jurisdiction: Covers Section 138 and Section 25 PSSA summons for Raipur, Durg, and Bhilai commercial borrowers, with DRT Jabalpur exercising debt recovery appellate oversight.
Address: ADR Building, Old High Court Premises, Collectorate Chowk, Raipur - 492001
Lok Adalat Conciliation: Under Chhattisgarh SLSA directives, conducts pre-litigation bank compromise settlements with up to 65% principal haircuts for distressed industrial borrowers.
FAQs: Personal Loan Settlement in Raipur
Why do borrowers in Raipur need specialized debt settlement services rather than dealing with recovery agents?
Third-party collection agents work on commission. They have no legal authority to reduce your debt. A debt settlement lawyer in Raipur knows RBI compromise rules. We protect your legal rights. We defend Section 138 and Section 25 notices in Raipur courts. We deal directly with bank zonal desks to win 45% to 65% OTS waivers.
Can recovery agents visit my shop in Gol Bazar, Pandri, or residence in Shankar Nagar without notice?
No. Under the RBI Fair Practices Code, recovery agents cannot visit your shop or home without prior written notice. They can only call between 8:00 AM and 7:00 PM. They cannot use abusive words or harass staff and neighbors. We serve cease-and-desist notices and file complaints with the RBI Ombudsman if agents break these rules.
What percentage of debt waiver can salaried employees and business owners in Raipur negotiate under an RBI OTS?
Unsecured loans past 90 days of default qualify for RBI compromise terms. Banks in Chhattisgarh routinely approve 45% to 65% principal waivers. They also write off 100% of late fees, penal interest, and NACH bounce charges. The final waiver depends on loan aging and financial hardship.
How does the Raipur District Legal Services Authority (DLSA) National Lok Adalat facilitate loan settlements?
The Raipur DLSA holds quarterly National Lok Adalats at the District Court Complex near Kalibadi. Judges and conciliators help borrowers and lenders reach an agreed settlement. The resulting Lok Adalat Award acts as a final civil court decree under Section 21 of the Legal Services Authorities Act, 1987. It ends the debt permanently.
Can a borrower in Chhattisgarh face police arrest or an FIR for defaulting on an unsecured personal loan?
No. Loan default is a civil dispute under the Indian Contract Act, 1872. Police stations in Raipur, Bhilai, or Bilaspur cannot arrest you or file an FIR for unpaid loans. If recovery agents threaten police action, your lawyer can issue notices for criminal intimidation under the Bharatiya Nyaya Sanhita (BNS).
What legal steps should I take if I receive a Section 138 NI Act or Section 25 PSSA court summons from JMFC Raipur?
Lenders often file cases under Section 138 of the NI Act or Section 25 of the PSSA in JMFC court in Raipur. You must hire a lawyer to enter an appearance and secure bail if needed. We establish your financial hardship, dispute unfair fees, and guide the case into an OTS settlement.
How can borrowers in Raipur stop recurring bank charges from bounced e-NACH mandates?
Under NPCI rules and RBI directives, you have the right to cancel e-NACH mandates at your bank branch in Raipur. This stops repeated bounce charges on your account. During loan settlement talks, our lawyers demand a 100% waiver of all accumulated bounce fees.
How does an unsecured personal loan settlement impact my CIBIL score in Chhattisgarh, and how can it be repaired?
After settlement, the lender marks your account as 'Settled' with ₹0 balance across CIBIL and other bureaus. Your score drops initially by 75 to 150 points. However, monthly default marks stop immediately. You can rebuild your CIBIL score to 750+ within 18 to 24 months with a secured credit card.
What forensic checks are necessary to verify an authentic bank OTS settlement letter in Raipur?
Before paying, your lawyer verifies key details in the OTS sanction letter. It must be on official bank letterhead with correct loan numbers and names. It must state the exact payment amount and due dates. It must confirm the withdrawal of court cases and promise a zero-balance NDC within 30 days under RBI rules.
What statutory recourse is available if a bank in Raipur fails to deliver the No Dues Certificate within 30 days?
Under RBI Circular RBI/2023-24/60, lenders must issue your No Dues Certificate within 30 days of payment. They must also update credit bureaus. If the lender delays without a valid reason, it must pay you compensation of ₹5,000 per day.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Master Circular: Fair Practices Code for Non-Banking Financial Companies (NBFCs) &. Commercial Banks
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online Portal for Complaints on Recovery Harassment &. Excessive NACH Charges
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987. National Lok Adalat Conciliation Framework
- High Court of Chhattisgarh (Bilaspur): Case Law Precedents on Debt Recovery, Order 37 CPC &. Section 138 NI Act