- Stop Agent Harassment. RBI rules ban unannounced visits to Satpur or Ambad workshops. Agents cannot threaten or shame you.
- 40% to 70% OTS Waivers. Settle overdue personal loans, credit cards, and business credit lines with big principal cuts and zero penal fees.
- District Court Defense. Experienced advocates defend Section 138 NI Act and Section 25 PSSA cases at Old Agra Road Court to secure bail.
- Binding Lok Adalat Orders. Settlements made at the Nashik DLSA Lok Adalat carry the power of a final civil court decree.
- Official No Dues Certificate. Get an official ₹0 No Dues Certificate within 30 days under RBI rules to clear your credit file.
1. Debt Distress Geography in Nashik & North Maharashtra
Nashik is a key industrial and farming center in Maharashtra. It hosts major auto parts clusters in Satpur, Ambad, and Sinnar MIDC. These units supply large car makers. It also holds aerospace units near Ozar. However, payment delays from big buyers often cause cash shortages for local parts makers.
When factory bills go unpaid for 90 to 120 days, business owners take high-interest loans and credit cards to keep running. At the same time, grape farmers and wine makers in Dindori and Niphad face bad weather and crop losses. These sudden events wipe out cash flows and create heavy debt.
Salaried workers in Gangapur Road, Indira Nagar, and College Road also face job cuts or medical costs. When loan EMIs stop, recovery agents start calling and visiting homes. Legal loan settlement services in Nashik give you direct legal protection. Advocates step in to stop harassment and negotiate formal debt cuts under RBI rules.
Loan defaults in Nashik often stem from factory payment delays or crop loss. Hiring a debt advocate ensures your true financial hardship is presented to the bank with proper proof.
2. Delinquency Timeline & NPA in Nashik
Understanding how banks classify bad loans helps you time your settlement talks. Under RBI rules, an overdue loan moves through three Special Mention Account (SMA) stages before turning into a Non-Performing Asset (NPA) at 90 days past due (DPD).
Bank sends payment reminders, adds late fees, and makes phone calls.
Auto-debits bounce with extra fees. External recovery agents get assigned.
Account moves to the SARB team. The bank sends Section 138 and Section 25 notices.
Under Ind AS 109 accounting rules, banks in Nashik must set aside capital reserves for bad loans. When a loan becomes an NPA, the bank must lock up 15% to 100% of the loan amount from its profits. Holding unpaid debt hurts the bank balance sheet.
Bank managers have internal targets to clear bad loans before quarterly audits. Instead of chasing old debt for years, banks prefer a fast cash settlement. A skilled lawyer starts settlement talks when bank pressure to clear bad loans is highest. This secures the largest debt cuts for you.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Borrower Legal Protections in Nashik
Many borrowers in Nashik face harsh calls from recovery agents. Agents often visit factories in Ambad and Satpur MIDC or homes in Indira Nagar. But loan default is strictly a civil contract matter under the Indian Contract Act, 1872. It is not a crime.
The RBI Master Circular on Recovery Agents sets clear rules that all lenders must follow:
- Calling Hours. Agents can only call you between 8:00 AM and 7:00 PM.
- Workplace Privacy. Agents cannot visit your office or home without written notice. They cannot discuss your debt with neighbors or staff.
- No Threats or Abuse. Threats of police arrest or fake court summons are crimes under the Bharatiya Nyaya Sanhita (BNS).
Banks also hit borrowers with high bounce fees of ₹450 to ₹600 for repeated NACH presentations. Under NPCI rules, you can ask your bank branch to stop active NACH debits. During settlement talks, our lawyers demand a 100% waiver of all bounce charges.
When a lawyer sends a formal notice of representation, all direct recovery visits must stop immediately under RBI rules. The bank must route all future talks through your legal counsel. This shields your family and brings peace of mind.
4. NPV Valuation & OTS Haircuts in Nashik
Bank One-Time Settlements follow RBI Master Directions on Compromise Settlements. Bank credit committees do not grant waivers based on emotion. They use a financial formula called Net Present Value (NPV).
When a lawyer submits an OTS offer, the bank compares two choices. It checks if taking an immediate discounted lump sum is better than fighting a slow 5-year court case under Order 37 CPC.
Where C_t is expected recovery, r is the bank discount rate, and deductions cover court fees, lawyer costs, and locked NPA reserves under Ind AS 109.
Unsecured personal loans have no property collateral. Taking a borrower to civil court takes 4 to 7 years. The bank must spend large sums on court fees and lawyers with no guaranteed outcome.
When our advocates submit proof of your job loss or business hardship, the bank sees clear logic. Getting 30% to 60% cash today gives the bank a higher Net Present Value than waiting years in court. This math supports the 40% to 70% debt waivers we secure for clients.
5. Resolution Blueprint in Nashik
This blueprint shows the full legal journey from debt default to advocate talks, Lok Adalat orders, and final ₹0 No Dues Certificates for Nashik borrowers:
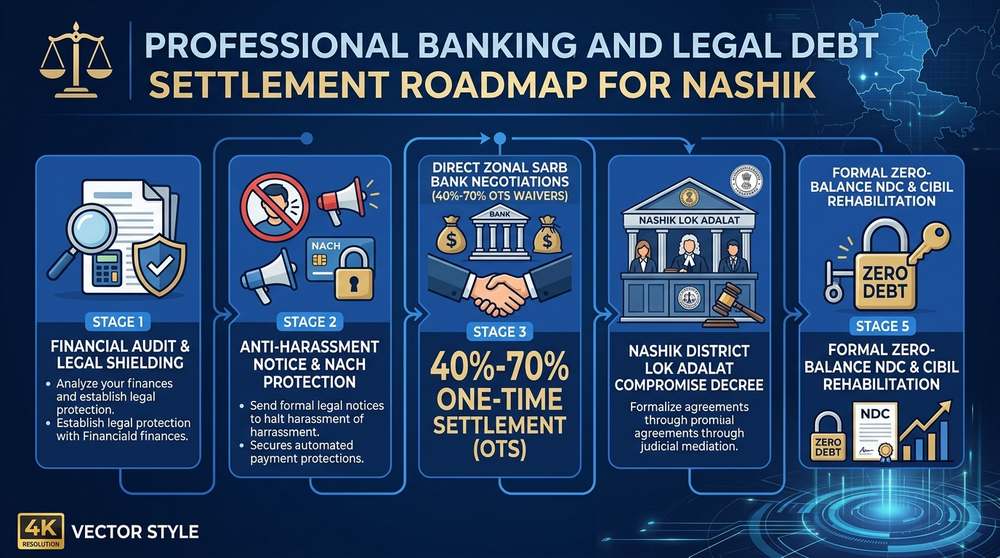
This process replaces recovery agent pressure with formal legal talks. Your lawyer deals directly with authorized bank committees to reach a fair settlement.
6. Judicial Defense in Nashik District Courts
When a loan is unpaid for over 120 days, lenders may file cases in court. In Nashik, these cases go to the Judicial Magistrate First Class (JMFC) Courts at the Old Agra Road Court Complex near CBS.
Lenders generally file two types of court actions:
Section 138 of the Negotiable Instruments Act, 1881 (Cheque Bounce)
If security cheques bounce, the bank sends a 15-day notice before filing a case. Our Nashik advocates file a Vakalatnama, obtain bail, and apply under Section 147 of the NI Act to move the dispute to Lok Adalat for full closure.
Section 25 of the Payment and Settlement Systems Act, 2007 (NACH Bounce)
When electronic NACH debits fail, lenders file cases under Section 25 PSSA. Our advocates show genuine financial distress and guide the case toward a mutual OTS agreement.
In civil suits under Order 37 CPC, our lawyers file for Leave to Defend. We challenge excessive penal interest and push the bank to settle out of court.
A qualified lawyer checks every notice for legal errors. Challenging defective notices creates legal pressure on the bank, prompting it to offer a quick settlement.
7. Nashik District Legal Services Authority DLSA Lok Adalat
The District Legal Services Authority (DLSA) at the Old Agra Road Court Complex runs quarterly Lok Adalats under MSLSA and NALSA. Lok Adalat is the safest legal path to close a loan dispute permanently.
During Lok Adalat sessions, a sitting judge and a lawyer mediator oversee talks between your advocate and bank managers. When both sides agree on a discounted amount, they sign a Joint Compromise Memo.
A Lok Adalat award acts as a final civil court decree under Section 21 of the Legal Services Authorities Act, 1987. No appeal can be filed against it. Court fees are refunded in full, and all pending Section 138 NI Act or Section 25 PSSA cases are dismissed for good.
This court order gives you full protection against future recovery claims or debt sales to ARCs. Once you pay the agreed sum, the debt is closed permanently under Indian law.
8. 5-Stage Settlement Protocol in Nashik
Resolving defaulted personal loans and business debt follows a 5-step legal process to get maximum debt cuts while keeping you safe:
Stage 1: Financial & Debt Audit
Our team audits your loan papers, bank statements, and bounce charges to remove wrongful fees added by the lender.
Stage 2: Cease-and-Desist Notice
We send formal legal notices under RBI Fair Practice rules to bank heads. This stops agent visits and directs all calls to counsel.
Stage 3: Bank SARB Negotiations
Advocates negotiate directly with bank credit committees in Nashik, using hardship proof to win 40% to 70% principal waivers.
Stage 4: Sanction Letter Audit & Payment
We verify the bank OTS sanction letter for complete legal accuracy. You then pay directly into your loan account via RTGS or NEFT.
Stage 5: ₹0 NDC & Credit Bureau Update
We ensure your official ₹0 No Dues Certificate arrives within 30 days under RBI rules and verify zero-balance status on CIBIL.
Through all five stages, you stay legally protected. Every step is backed by formal legal documents to erase your debt for good.
9. Forensic Audit of Nashik OTS Letters
Distressed borrowers must be careful with fake settlement letters issued by rogue agents. SettleLoans checks every OTS document before you pay any money.
Every genuine bank OTS letter in Nashik must meet six mandatory checkpoints:
10. CIBIL Trajectory in Nashik
Understanding your credit score after settlement helps you plan your recovery. When you settle an unsecured loan, the lender reports the account to CIBIL, Experian, and CRIF as "Settled" with a balance of ₹0.
While your score drops temporarily to 550–650, it stops active default reporting. Borrowers in Nashik can rebuild their score above 750 over 18 to 24 months with simple steps:
- Secured Credit Cards. Open a ₹30,000 fixed deposit to get a secured credit card. Use under 25% of the limit and pay on time each month.
- Check Credit Reports. Check your CIBIL report 45 days after settlement to confirm that outstanding dues show as ₹0.
- On-Time Payments. Pay utility bills and small consumer loans on time to build a strong payment track record.
Credit bureaus give more weight to recent on-time payments than old write-offs. By paying promptly, settled borrowers in Nashik regain eligibility for business and home loans within two years.
11. Debt Resolution Matrix in Nashik
Review resolution paths and expected OTS waivers for borrowers across Nashik and North Maharashtra:
| Debt Type | Overdue Days | Legal Forum | Target OTS Waiver | Time Taken |
|---|---|---|---|---|
| Unsecured Personal Loans | 90 to 180+ Days | Section 25 PSSA / JMFC Court | 45% to 65% Waiver | 45 to 90 Days |
| Credit Card Balances | 120 to 240+ Days | Arbitration / Civil Suit | 50% to 70% Waiver | 30 to 60 Days |
| Fintech Loan Apps | 60 to 120+ Days | Legal Demand Notice | 50% to 65% Waiver | 20 to 45 Days |
| Auto & MSME Credit Lines | 90 to 180+ Days | Section 138 NI Act / Order 37 CPC | 40% to 60% Waiver | 60 to 120 Days |
| Lok Adalat Orders | Pre-Trial / JMFC Case | DLSA Nashik Lok Adalat | 45% to 65% Waiver | Single Hearing Day |
12. SettleLoans Legal Defense & Debt Advisory in Nashik
SettleLoans is India's leading legal debt resolution service. Our Nashik legal team brings deep knowledge in banking rules, bank SARB talks, and court defense at the Old Agra Road Court Complex. We have helped over 1,200 borrowers across Maharashtra stop recovery harassment and secure maximum debt waivers.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Nashik
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Nashik can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Old Agra Road, Central Bus Stand (CBS) Area, Nashik, Maharashtra - 422002
Jurisdiction: Adjudicates loan default summary suits and Section 138 cases for manufacturing units, grape processing enterprises, and retail borrowers.
Address: ADR Building, New District Court Campus, CBS, Nashik - 422002
Lok Adalat Conciliation: Under Maharashtra SLSA, facilitates direct bank compromise settlement conferences, eliminating recovery agency harassment.
13. Frequently Asked Questions on Nashik Loan Settlement
Why do auto-ancillary engineers and agro-business owners in Nashik require specialized loan settlement services?
How does an advocate defend against Section 138 NI Act or Section 25 PSSA court summons in Nashik?
Can bank recovery agents visit industrial workshops in Ambad MIDC or homes in Indira Nagar without permission?
How does the District Legal Services Authority (DLSA) Lok Adalat in Nashik formalize loan settlements?
What percentage of debt waiver can borrowers in Nashik realistically achieve through an OTS?
Can Nashik City Police arrest a borrower for defaulting on an unsecured personal loan?
How do you stop recurring NACH mandate bounce charges across bank accounts in Nashik?
What essential forensic checks must be conducted on a bank OTS sanction letter in Nashik?
How long does a bank take to deliver the No Dues Certificate (NDC) after loan settlement in Maharashtra?
Official Statutory & Regulatory References
- Reserve Bank of India (RBI): Master Directions on Compromise Settlements and Technical Write-offs (Circular RBI/2023-24/40)
- RBI Integrated Ombudsman Portal (CMS): Official Escalation for Recovery Agent Harassment & Banking Malpractice
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987 — National Lok Adalat Conciliation
- District & Sessions Court Nashik (eCourts): Case Status, Causelists & JMFC Old Agra Road CBS Listings
- High Court of Bombay: Jurisprudential Precedents on Section 138 NI Act, Order 37 CPC & Civil Debts