- Statutory Harassment Shielding. RBI rules ban unannounced visits to MIHAN offices or Sitabuldi shops. Agents cannot use abusive language or disclose your debt.
- Substantial OTS Debt Waivers. Unsecured loans qualify for 40% to 70% principal waivers. Banks also waive 100% of penal fees and late charges.
- Nyay Mandir Court Defense. Our advocates defend against Section 138 and Section 25 notices. We secure bail and prevent arrest warrants in Nagpur courts.
- Binding Lok Adalat Decrees. DLSA Lok Adalat awards act as civil decrees under Section 21. They are final, binding, and cannot be appealed.
- Forensic Zero-Balance NDC Guarantee. Direct talks with bank SARB wings ensure genuine sanction letters. You receive a ₹0 NDC within 30 days under RBI rules.
1. Debt Distress Geography in Nagpur & Vidarbha
Nagpur is the main commercial hub of Central India. It hosts tech firms in MIHAN. It has trading hubs in Sitabuldi and Gandhibagh. Tech layoffs and pay cuts hit families hard. Business slowdowns add stress. Salaried staff and traders face heavy debt. Personal loans and credit cards pile up.
MSME units in Butibori and Hingna MIDC face cash flow drops. Raw material costs rose quickly. Delayed client payments created cash crunches. Business owners take personal loans to cover daily expenses. High compound interest turns small debts into large debt traps.
Unguided borrowers often face aggressive recovery calls. Small token payments only feed penal interest. They never reduce principal debt. Hiring a loan settlement lawyer in Nagpur protects your family. Our advocates document your financial hardship. We negotiate an official settlement under RBI rules.
Nagpur loan defaults stem from real business or job shocks. Our advocates present your hardship directly to bank committees. We provide solid documentary proof.
2. Delinquency Timeline & NPA Mechanics
Knowing how banks classify overdue loans helps you time settlement talks. Under RBI rules, unpaid loans move through SMA stages. At 90 days, they turn into NPAs.
Automated SMS alerts, late fees, and calls from bank branch staff.
Multiple NACH bounce charges and assignment of third-party recovery agencies.
Account moves to Zonal SARB desks. Lenders draft notices under Section 138 and Section 25.
Under Ind AS 109, banks must reserve capital for bad loans. For Substandard or Doubtful loans, banks lock 15% to 100% capital. This locked money hurts bank profits. It gives our advocates strong leverage to negotiate deep principal waivers.
Banks want to clean their balance sheets before fiscal audits. Rather than holding non-earning bad loans, banks prefer quick cash recovery. We time your settlement petition to secure the highest possible waivers.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Borrower Legal Protections in Nagpur
Many borrowers in Nagpur face aggressive recovery tactics. Agents visit MIHAN offices or Sitabuldi shops. They visit homes in Dharampeth. Loan default is a civil matter under the Indian Contract Act, 1872. It is not a crime.
The RBI Fair Practices Code sets strict rules. Agents in Nagpur must follow them:
- Restricted Calling Hours. Agents can call only between 8:00 AM and 7:00 PM. Late night and early morning calls are illegal.
- Workplace & Privacy Safeguards. Agents cannot enter your workplace, shop, or home without prior notice. They cannot reveal debt details to coworkers or neighbors.
- Prohibition of Intimidation. Abusive words and arrest threats break the law. Fake legal notices violate Bharatiya Nyaya Sanhita (BNS).
Lenders often present NACH auto-debits multiple times a month. This causes repeated bounce fees of ₹450 to ₹600. You can stop active e-mandates. NPCI and RBI rules give you this right. During settlement talks, we demand full waiver of bounce fees.
When we issue a legal notice, all agent harassment stops. Lenders must route all calls and letters through our legal office. This protects your family and dignity.
4. NPV Valuation & OTS Haircuts in Nagpur
One-Time Settlements follow the RBI Master Direction of June 2023. Bank credit committees do not act on emotion. They use Net Present Value (NPV) financial recovery models.
The bank compares quick cash against slow court cases. Order 37 CPC suits at Nagpur Civil Court take years.
Here, C_t is future recovery. The letter r is discount rate. Deductions cover court delays, legal fees, and capital costs.
Unsecured personal loans have no attached property or collateral. Winning a civil decree in court takes four to seven years. It costs banks heavy legal fees.
When we submit hardship proof, the bank sees clear financial logic. Getting 30% to 60% cash today gives high value. It beats waiting years in court. This enables 40% to 70% debt waivers.
5. Visual Resolution Roadmap in Nagpur
The roadmap below shows 5 settlement steps. Learn how to settle debt in Nagpur. Learn how to handle notices, negotiate with SARB desks, and secure an NDC:
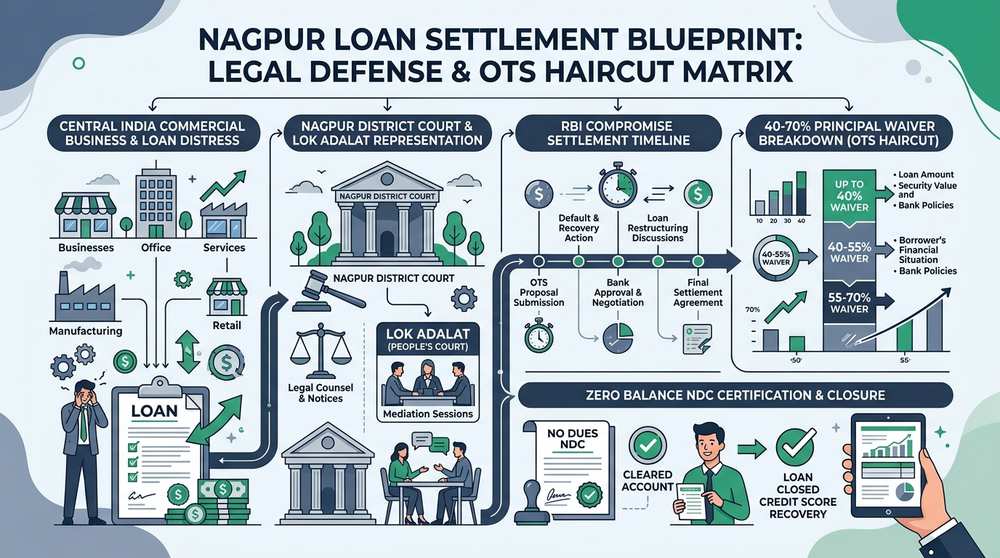
This roadmap replaces collection agent pressure with formal legal talks. Our advocates negotiate directly with authorized bank credit committees.
6. Judicial Defense in Nagpur District Courts
When defaults exceed 120 days, lenders take legal steps. In Nagpur, banks file cases before the JMFC at Nyay Mandir.
Lenders deploy two main legal actions:
Section 138 of the Negotiable Instruments Act, 1881 (Cheque Dishonour)
If a cheque bounces, the lender sends a 15-day notice. Then, they file a criminal complaint. Our advocates file a Vakalatnama and secure bail. We challenge court jurisdiction. We apply for Lok Adalat transfer under Section 147.
Section 25 of the Payment and Settlement Systems Act, 2007 (Electronic Mandate Dishonour)
When NACH auto-debits bounce, lenders file Section 25 PSSA complaints. We prove lack of criminal intent. We document financial distress. We guide your case to a compromise settlement.
In Order 37 CPC summary suits, our advocates file for Leave to Defend. We challenge illegal compound interest. We guide the bank to an out-of-court OTS.
Our advocates challenge flawed notices and incorrect interest calculations. This active defense motivates bank managers to settle quickly.
7. Nagpur District Legal Services Authority DLSA Lok Adalat
Nagpur DLSA holds regular Lok Adalats. Benches sit at Nyay Mandir in Civil Lines. Under MSLSA and NALSA rules, Lok Adalat is the safest settlement path.
A judge and mediator guide the talks. Your advocate negotiates with bank heads. Once both sides agree, they sign a Joint Compromise Memo.
A Lok Adalat award equals a civil decree under Section 21. No appeal lies against it. All court fees are 100% refunded. Pending Section 138 and Section 25 cases get dismissed.
This gives you full protection against future recovery or ARC debt sales. Once paid, your debt is permanently closed under law.
8. 5-Stage Settlement Protocol in Nagpur
Settling bank loans requires a structured 5-stage legal protocol:
Stage 1: Forensic Financial & Debt Audit
We audit loan statements and penal charges. We check NACH bounce fees to find true baseline debt.
Stage 2: Cease-and-Desist Notice & Legal Insulation
We issue formal legal notices to bank nodal officers. This halts recovery calls and routes all talks through our office.
Stage 3: Direct SARB & Credit Committee Negotiations
Our advocates negotiate directly with bank SARB wings in Nagpur. We use hardship evidence to secure 40% to 70% principal waivers.
Stage 4: Stamped Sanction Letter Audit & Direct Remittance
We audit the OTS sanction letter for complete legal validity. You pay directly into your official loan account via RTGS/NEFT.
Stage 5: ₹0 No Dues Certificate & Credit Bureau Updation
We secure your ₹0 NDC in 30 days. This follows RBI rules. We verify credit bureau zero-balance updates.
This 5-stage process ensures legal safety. It permanently closes all debt liabilities.
9. Forensic Audit of OTS Letters in Nagpur
Never pay recovery agents on verbal promises. Fake settlement letters are common. SettleLoans audits every document before you pay.
Every valid OTS sanction letter must pass six checks:
10. CIBIL Score Rehabilitation in Nagpur
Credit bureaus record settled accounts as "Settled" with ₹0 balance. This stops monthly default marks.
A settled mark temporarily lowers your score to 550–650. But it halts active NPA default reports. You can rebuild credit to 750+ within 12 to 18 months:
- Secured Fixed Deposit Credit Cards. Open a fixed deposit to get a secured credit card. Use under 25% of the limit. Pay bills on time.
- Credit Bureau Audit & Dispute Resolution. Check credit reports 45 days after settlement. Verify that your balance reflects ₹0.
- Diversified Timely Credit Repayments. Pay utility bills and consumer loans on time. This restores your credit score.
Credit bureaus value recent good repayment history. Disciplined card use helps you qualify for home loans in two years.
11. Nagpur Debt Resolution Matrix
Compare debt categories, legal forums, and expected OTS waiver ranges in Nagpur:
| Debt Category | Typical Delinquency Stage | Primary Legal Notice / Forum | Expected OTS Haircut | Resolution Timeline |
|---|---|---|---|---|
| Unsecured Personal Loans | 90–180+ DPD (Substandard/Doubtful NPA) | Section 25 PSSA / Nyay Mandir JMFC Court | 45% – 65% Principal Waiver | 45 to 90 Days |
| Revolving Credit Card Dues | 120–240+ DPD (Written-Off Portfolio) | Arbitration Notice / Summary Civil Suit | 50% – 70% Total Waiver | 30 to 60 Days |
| Digital NBFC & Fintech Apps | 60–120+ DPD (Loss Asset Category) | Digital Legal Notice / Demand Notice | 50% – 65% Principal Waiver | 20 to 45 Days |
| Unsecured MSME Business Lines | 90–180+ DPD (Stressed Business Credit) | Section 138 NI Act / Order 37 CPC | 40% – 60% Principal Waiver | 60 to 120 Days |
| Lok Adalat Compromise Awards | Pre-Litigation / Pending JMFC Summons | DLSA Nagpur Lok Adalat Bench | 45% – 65% Final Decree | Same-Day Lok Adalat Session |
12. SettleLoans Legal Defense in Nagpur
SettleLoans is India's premier debt defense advisory. Our Nagpur team brings deep SARB and Nyay Mandir court defense experience. We helped 1,200+ borrowers stop harassment. We secured major OTS savings.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Nagpur
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Nagpur can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Nyay Mandir, Civil Lines, Nagpur, Maharashtra - 440001
Jurisdiction: Principal trial court for Vidarbha covering Section 138 NI Act complaints, logistics MSME defaults, and private finance company summons.
Address: ADR Centre, Nyay Mandir Premises, Civil Lines, Nagpur - 440001
Lok Adalat Conciliation: Convenes regular National Lok Adalat benches to resolve defaulted credit lines, protecting borrowers from coercive recovery.
13. Frequently Asked Questions on Nagpur Loan Settlement
Why do salaried professionals and business owners in Nagpur need a dedicated personal loan settlement lawyer?
How does an advocate defend against Section 138 NI Act or Section 25 PSSA summons in Nagpur courts?
Can recovery agents visit retail shops in Sitabuldi or tech offices in MIHAN without prior permission?
How does the District Legal Services Authority (DLSA) Lok Adalat in Nagpur settle loan defaults?
What percentage of debt waiver can borrowers in Nagpur realistically achieve through an OTS?
Can Nagpur City Police arrest a borrower for defaulting on an unsecured personal loan?
How do you stop recurring NACH mandate bounce charges across bank accounts in Nagpur?
What essential forensic checks must be conducted on a bank OTS sanction letter in Nagpur?
How long does a bank take to deliver the No Dues Certificate (NDC) after loan settlement in Maharashtra?
Official Statutory & Regulatory References
- Reserve Bank of India (RBI). Master Directions on Compromise Settlements and Technical Write-offs (Circular RBI/2023-24/40)
- RBI Integrated Ombudsman Portal (CMS). Official Escalation for Recovery Agent Harassment & Banking Malpractice
- National Legal Services Authority (NALSA). Legal Services Authorities Act, 1987 — National Lok Adalat Conciliation
- District & Sessions Court Nagpur (eCourts). Case Status, Causelists & JMFC Nyay Mandir Civil Lines Listings
- High Court of Bombay (Nagpur Bench). Jurisprudential Precedents on Section 138 NI Act, Order 37 CPC & Civil Debts