- Civil Contract Nature. Unsecured loan default is a civil dispute under the Indian Contract Act, 1872. Police in Bhopal cannot arrest you for debt defaults.
- Workplace Anti-Harassment. RBI rules strictly ban recovery visits to Mantralaya, Satpura Bhawan, schools, or shops. Agents cannot call third parties.
- 45% to 65% Debt Waivers. When loans become NPAs after 90 to 180 days, banks set aside funds and approve deep OTS cuts.
- Arera Hills Court Defense. Our advocates handle Section 138 NI Act and Section 25 PSSA summons. We secure binding settlements at DLSA Lok Adalat.
- Official No Dues Certificate. Under RBI Circular RBI/2023-24/60, banks must issue your No Dues Certificate in 30 days. Delays cost ₹5,000 per day.
The Economic Reality of Debt Distress in Bhopal
Bhopal is the capital hub of Madhya Pradesh. Many people work in Vallabh Bhawan (Mantralaya) and Satpura Bhawan. Others work at BHEL Bhopal, AIIMS, and local colleges. Busy markets run in MP Nagar, New Market, and Govindpura.
Banks gave many personal loans across Bhopal. When health crises or pay delays happen, EMIs bounce. Banks then add heavy penal charges. Recovery agents start calling homes and workplaces.
Loan default is a civil dispute under the Indian Contract Act, 1872. It is not a crime. Under RBI rules, borrowers facing hardship can stop harassment. You can negotiate a legal One-Time Settlement (OTS).
NPA Delinquency Lifecycle in Bhopal
Under RBI IRACP and Ind AS 109 rules, banks track overdue loans by days. Early overdue stages are SMA-0 and SMA-1. After 90 days, the loan becomes an NPA. The bank freezes interest and locks capital reserves. This creates strong motivation for banks to settle.
| Delinquency Stage | Overdue Days (DPD) | Lender Recovery Strategy in Bhopal | Legal Exposure & Court Notices | Settlement Haircut Potential |
|---|---|---|---|---|
| SMA-0 (Early Overdue) | 1 – 30 Days | SMS alerts and automated calls. | Zero court action; credit score drops. | No cuts. Banks demand full EMI. |
| SMA-1 (Mid Delinquency) | 31 – 60 Days | Frequent agent calls and loan recall notices. | Warning letters sent to borrower. | Low cuts. Banks offer loan tenure extension. |
| SMA-2 (Pre-NPA Escalation) | 61 – 90 Days | Agent visits to home or office. | 15-day notices under Section 138 NI Act or Section 25 PSSA. | Moderate cuts. Penal fees can be waived. |
| NPA (Substandard Asset) | 91 – 180 Days | Account sent to Zonal Stressed Assets desk. | Court summons from JMFC court; Lok Adalat notices. | High cuts (35% to 50% principal waiver). |
| Doubtful / Written-Off Asset | 181 – 365+ Days | Bank writes off the bad debt. | Civil suits under Order 37 CPC and Lok Adalat decrees. | Maximum cuts (50% to 65% principal waiver). |
Once a loan is written off, the bank has booked the loss. An immediate cash OTS gives the bank fresh funds. This makes Zonal Credit Committees approve large principal cuts.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Defending Against Harassment in Bhopal
Borrowers across Arera Colony, Shahpura, MP Nagar, and Kolar Road face aggressive collection agents. Agents often threaten office visits or shop disruptions. The RBI Fair Practices Code sets strict rules:
- Allowed Hours. Agents may only call or visit between 8 AM and 7 PM.
- No Third-Party Calls. Calling office bosses, colleagues, or relatives is illegal.
- Zero Abuse. Abusive language and public shaming violate RBI rules.
- Mandatory ID. Agents must show ID cards and bank authorization letters.
Repeated NACH auto-debit presentations create heavy bounce fees. Under NPCI rules, you can instruct your bank to cancel the e-NACH mandate. Our advocates also get 100% of bounce fees waived during OTS talks.
RBI Compromise Rules & NPV in Bhopal
Under RBI Master Direction DOR.STR.REC.20/21.04.048/2023-24, banks maintain compromise policies. Personal loans have no collateral to seize under SARFAESI. Banks use Net Present Value (NPV) math to evaluate settlement offers:
Where C_t is expected recovery and r is discount rate. Deductions cover 3 to 5 years of legal costs and locked NPA funds.
Our advocates prove that long court trials cost banks money. A fast cash settlement gives banks higher net value. This helps win large principal waivers.
Realistic Loan Settlement Haircut Slabs for Bhopal & MP Borrowers
| Debt Category | Delinquency Bucket | Penal & Bounce Waiver | Principal Haircut Range | Optimal Settlement Target |
|---|---|---|---|---|
| Unsecured Personal Loan | 90 – 180 Days (NPA) | 100% Complete Waiver | 35% – 50% Principal Waiver | Pay 45%–55% of Core Principal |
| Unsecured Personal Loan | 180 – 365+ Days (Written Off) | 100% Complete Waiver | 50% – 65% Principal Waiver | Pay 35%–45% of Core Principal |
| Credit Card Outstanding | 90 – 180+ Days (NPA) | 100% Interest & Late Fees | 55% – 70% Total Waiver | Pay 30%–40% of Total Dues |
| MSME Unsecured Business Loan | 90 – 180 Days (NPA) | 100% All Penal Charges | 35% – 50% Principal Waiver | Pay 45%–55% of Disbursed Dues |
| Fintech Instant Loan App | 60 – 180+ Days (Default) | 100% Compound Fees | 50% – 65% Principal Waiver | Pay 35%–45% of Net Principal |
Bhopal Personal Loan Settlement & Lok Adalat Legal Defense Blueprint
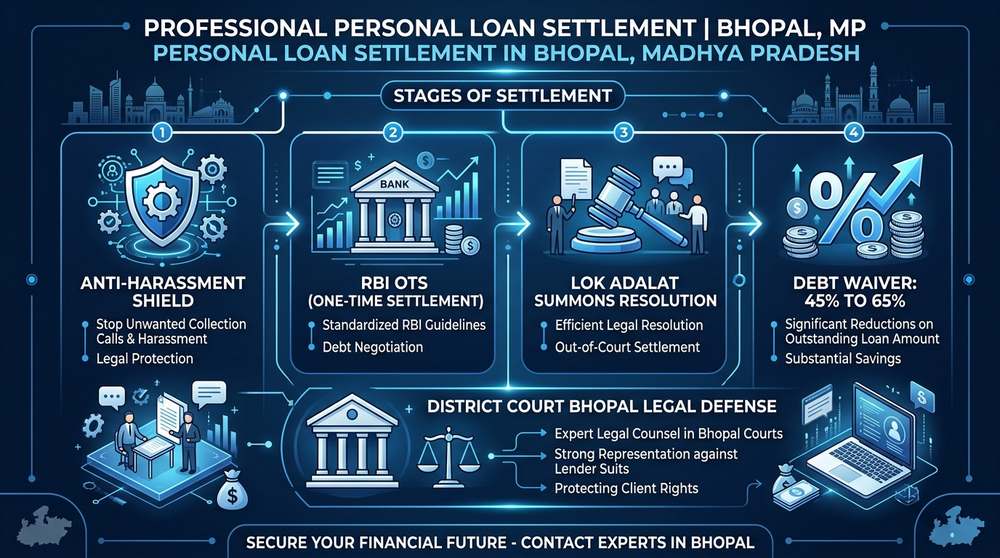
Sec 138 NI Act & Sec 25 Defense in Bhopal Courts
Lenders may file cases before the JMFC at Arera Hills District Court. These include Section 138 cheque bounce cases. They also file Section 25 PSSA cases for NACH bounce.
A court summons is not an arrest warrant. Under CrPC and BNSS rules, these are bailable offenses. They are compoundable in nature. Our advocate represents you in court. Counsel secures bail quickly. We show proof of genuine financial hardship. Then, we seek referral to the Lok Adalat for settlement.
Some lenders start unilateral arbitration in distant cities. Under Supreme Court rulings in Perkins Eastman and TRF Ltd., such actions are illegal. Unilateral arbitrator appointments have no legal standing. Your advocate challenges jurisdiction under Section 12 and Section 14 of the Arbitration Act. This halts biased arbitration.
Resolving Defaults via Bhopal DLSA Lok Adalat
DLSA Bhopal holds National Lok Adalats every quarter at Arera Hills. They provide a trusted forum to settle unpaid debts. Bank officers attend with special settlement authority. They can grant 45% to 65% debt waivers.
A Lok Adalat settlement offers key legal benefits:
- Civil Court Decree Status. Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat Award has the force of a civil decree.
- Final and Binding. Once signed, the award cannot be challenged or appealed.
- Case Dismissal. All Section 138, Section 25 PSSA, and recovery cases close permanently.
- Court Fee Refund. Banks get court fees refunded. This encourages them to offer larger debt waivers.
Step-by-Step Settlement Roadmap in Bhopal
Our structured six-phase roadmap helps you secure the best settlement terms:
1Hardship Dossier & Forensic Financial Audit
Collect proof of income loss, medical expenses, or business slowdown. This proves genuine hardship under RBI compromise rules.
2NACH Mandate Cancellation & Representation Notice
Stop e-NACH auto-debits to avoid recurring bounce penalties. Send a formal legal notice directing lenders to communicate only with your lawyer.
3Submitting Compromise Petition to Stressed Assets Desk
File a formal compromise proposal with the bank zonal stressed assets desk in Bhopal or Indore. Start offers at 25% to 35% of principal dues.
4Strategic Negotiation & Credit Committee Approval
Our advocates counter bank demands using loan recovery norms. We negotiate to win 45% to 65% debt waivers from credit committees.
5Forensic Audit of the OTS Sanction Letter
Check the settlement letter on official bank letterhead. Ensure all account numbers, waiver sums, and case withdrawal terms are accurate.
6Remittance & 30-Day ₹0 NDC Delivery Enforcement
Pay the agreed settlement sum directly into the bank loan account. Enforce delivery of the No Dues Certificate within 30 days under RBI circular RBI/2023-24/60.
Sanction Letter Audit & NDC in Bhopal
Recovery agents may send fake or unauthorized settlement letters. To protect your money, our legal team verifies every document:
- Bank Letterhead. The letter must appear on official corporate letterhead with proper bank details and CIN.
- Accurate Details. The notice must state your name, PAN, loan account number, and total outstanding balance.
- Clear Payment Terms. It must state the exact settlement amount, due dates, and official bank payment modes.
- Full Liability Release. It must confirm full loan closure and withdrawal of all pending court cases.
Under RBI Circular RBI/2023-24/60, lenders must issue a No Dues Certificate (NDC) within 30 days of full payment. They must update bureau records. If a lender delays beyond 30 days, they must pay ₹5,000 per day in compensation.
Post-Settlement CIBIL Recovery in Bhopal
After settlement, credit bureaus (CIBIL, Experian, Equifax, CRIF) mark the loan as 'Settled' with a ₹0 balance. Your score may drop 75 to 150 points at first. But this ends overdue interest charges and stops legal action.
Bhopal borrowers can rebuild their credit score to 750+ in 18 to 24 months with simple steps:
- Secured Credit Card. Open a fixed deposit of ₹25,000 to ₹50,000 to get a secured credit card.
- Low Card Usage. Keep your credit usage below 25% of the total limit.
- Timely Payments. Pay your full credit card bill on time every month.
- Credit Audits. Check credit reports to ensure the settled account shows a ₹0 balance.
Why Distressed Borrowers in Bhopal Choose SettleLoans
Handling loan recovery pressure requires experienced legal support. SettleLoans helps civil servants, teachers, traders, and MSME owners across Bhopal, Sehore, Raisen, Vidisha, and Hoshangabad. We stop harassment. We defend court notices at Arera Hills. We represent clients at DLSA Lok Adalat sessions to secure maximum debt waivers.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
District Courts & DLSA Helpdesk in Bhopal
Distressed borrowers facing recovery pressure, arbitration summons, or Section 138 NI Act notices in Bhopal can access statutory legal defense through the local District Court and District Legal Services Authority (DLSA):
Address: Arera Hills, Near Jail Road, Bhopal, Madhya Pradesh - 462011
Jurisdiction: Chief Judicial Magistrate courts oversee loan recovery complaints and Section 25 PSSA notices for state employees and private borrowers.
Address: ADR Bhavan, District Court Premises, Arera Hills, Bhopal - 462011
Lok Adalat Conciliation: Under MP State Legal Services Authority (MPSLSA), conducts specialized debt settlement benches ensuring zero ongoing bank claims.
FAQs: Personal Loan Settlement in Bhopal
Why do borrowers in Bhopal need specialized loan settlement advocates instead of dealing with recovery agents?
Collection agents work on commission. They cannot grant loan waivers. A settlement advocate uses RBI Master Directions to defend your rights. We stop agent visits. We defend Section 138 NI Act or Section 25 PSSA cases in Arera Hills District Court. We negotiate directly with bank credit committees for 45% to 65% debt waivers.
Can bank recovery agents visit government offices in Mantralaya, Satpura Bhawan, or BHEL Bhopal?
No. RBI rules strictly ban recovery visits to government offices, colleges, or workplaces. Agents cannot contact co-workers or supervisors. If agents violate rules, our advocates send legal notices and file complaints with the RBI Ombudsman.
What percentage of loan waiver can salaried employees and business owners in Bhopal expect in an OTS?
For unsecured loans and credit cards overdue past 90 days (NPA status), banks in Bhopal approve 45% to 65% principal cuts. Banks also waive 100% of late fees, penal interest, and NACH bounce charges.
How does the District Legal Services Authority (DLSA) National Lok Adalat in Bhopal resolve loan disputes?
Bhopal DLSA holds quarterly Lok Adalats at the Arera Hills District Court Complex. Judicial benches help borrowers and bank officers reach compromise settlements. The final agreement becomes a Lok Adalat Award. Under the Legal Services Authorities Act 1987, this award acts as a final civil court decree.
Can a borrower in Bhopal be arrested by police for defaulting on a personal loan or credit card?
No. Unsecured loan default is a civil contract dispute under the Indian Contract Act, 1872. Police in Bhopal cannot register FIRs or arrest you for loan defaults. False police threats by agents count as criminal intimidation under the BNS.
How should a borrower in Bhopal respond to a Section 138 NI Act or Section 25 PSSA summons from JMFC Arera Hills?
When cheques or NACH auto-debits bounce, lenders file cases under Section 138 NI Act or Section 25 PSSA at Arera Hills court. You should hire an advocate to appear on your behalf. We secure bail. We prove financial hardship and refer the case to Lok Adalat for an agreed OTS.
How do you stop recurring electronic NACH mandate bounce charges across Bhopal bank branches?
Under NPCI rules, you can instruct your home bank in Bhopal to cancel or freeze the e-NACH mandate. During settlement talks, our advocates also get a 100% waiver of all accumulated bounce charges.
How does personal loan settlement affect CIBIL scores in Bhopal, and how can credit be rebuilt?
The bank reports your loan as 'Settled' with ₹0 dues to credit bureaus. This stops penal fees and default marks. You can rebuild your credit score to 750+ in 18 to 24 months with a secured credit card and timely payments.
What essential forensic checks must be conducted on a bank OTS sanction letter in Bhopal?
Before you pay, our advocates verify the letter. It must be on official bank letterhead with CIN. It must state your full name and loan account number. It must list the agreed amount and payment dates. It must confirm withdrawal of all court cases. And it must guarantee a ₹0 No Dues Certificate within 30 days under RBI Circular RBI/2023-24/60.
What compensation is a bank in Madhya Pradesh liable to pay if it delays the No Dues Certificate beyond 30 days?
Under RBI Circular RBI/2023-24/60, lenders must issue your No Dues Certificate within 30 days of full settlement. If delayed, the bank must pay compensation of ₹5,000 per day directly to the borrower.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Master Circular: Fair Practices Code for Non-Banking Financial Companies (NBFCs) & Commercial Banks
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online Portal for Complaints on Recovery Harassment & Excessive NACH Charges
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987 — National Lok Adalat Conciliation Framework
- High Court of Madhya Pradesh: Principal Seat at Jabalpur Case Law Precedents on Debt Recovery, Order 37 CPC & Section 138 NI Act