- Zero Payments to Extortionists: Paying 7-day rogue apps never settles the debt; blackmailers escalate extortion demands across multiple fake virtual accounts.
- Immediate Cybercrime.gov.in & 1930 Filing: Lodge an electronic complaint under Cyber Extortion / Privacy Violation to generate a legal acknowledgement timestamp.
- Chakshu & Sanchar Saathi Blocking: Report threatening WhatsApp handles and virtual SIM numbers to trigger national telecom-level IMEI blacklisting.
- Statutory Immunity & Zero CIBIL Impact: Unregistered foreign shell APKs have no legal standing in Indian civil courts and zero access to credit information companies (CIBIL/Experian).
1. Anatomy of Instant Loan App Scams: 7-Day Traps, APK
Bharat mein pichle teen varshon ke dauran digital financial fraud ka sabse bhayanak aur aakramak roop instant loan apps ke madhyam se ubhar kar samne aaya hai. Lakho nirdosh borrowers jinhe aapatkalin medical kharchon, school fees ya daily liquidity ki zaroorat hoti hai, social media advertisements jaise Instagram, Facebook, Telegram aur shady third-party websites par "Aadhaar Card Par 5 Minute Mein ₹50,000 Loan" jaise lubhavne daawon ke jaal mein phas jate hain. Yeh apps Google Play Store ki security screening ko bypass karne ke liye aksar direct Android Application Package (APK) download links provide karti hain ya deceptive utility apps (jaise calculator, wallpaper tools ya battery savers) ke roop mein store par secretly list hoti hain.
Jaise hi koi user is malicious APK file ko apne mobile phone par install karta hai, yeh application operating system ke deep core access permissions mangti hai. Ismein user ki complete Contacts Directory, Gallery Photos, SMS Logs, Call Records, Real-time GPS Location aur Microphone access shamil hote hain. Yadi user in permissions ko reject karta hai, toh app aage credit evaluation process ko block kar deti hai. Installation ke agle hi pal, pura device data stealth background sync ke zariye foreign servers (visheshkar China, Cambodia, Myanmar aur Hong Kong ke AWS aur Alibaba Cloud clusters) par clone kar liya jata hai.
Iske baad shuru hota hai 7-Day Micro-Credit Trap. Example ke roop mein, borrower ko ₹5,000 ka loan approve dikhaya jata hai, lekin actual bank transfer sirf ₹2,800 se ₹3,200 ka kiya jata hai jabki baki rakam ko 'Processing Fee' aur 'Verification Charges' ke naam par upfront deduct kar liya jata hai. 7 din pure hone se pehle hi—chhathe (6th) din ki subah se hi—automatic recovery bots aur abusive call centers dwara ₹5,000 se lekar ₹8,000 tak ki instant repayment ke threatening messages aane shuru ho jate hain.
2. Cyber Blackmail Tactics: Morphed Pornographic Photos, WhatsApp Contact Spamming & Social Lynching
Instant loan app syndicates ki recovery strategy banking ya civil law par adharit nahi hoti, balki pure Psychological Terrorism & Cyber Blackmail par tiki hoti hai. Jab victim high interest rates ya unconscionable processing charges ka virodh karta hai ya payment karne mein asamarth hota hai, toh recovery operatives organized stage-wise harassment workflow execute karte hain.
Phase 1: Abusive Cold-Calling via Virtual VoIP Routing. Pehle charan mein victim ko subah 6 baje se lekar raat ke 2 baje tak lagatar abusive calls kiye jate hain. Yeh calls local Indian telecom SIMs se nahi, balki virtual private networks (VPN) aur automated VoIP dialers ke madhyam se spoofed international numbers (+84, +62, +92, +44) se aate hain, jisse caller ID tracking complex ho jati hai.
Phase 2: Contact List Hijacking & Defamatory Group Creation. Doosre charan mein scammers victim ke chori kiye gaye contact list par aakraman karte hain. Victim ke maa-baap, patni, bhai, behen, office ke HR manager aur purane dosto ko WhatsApp par derogatory messages bheje jate hain jinme victim ko 'Fraudster', 'Thief', ya 'Rapist on the Run' likhkar badnaam kiya jata hai. Scammers parivar ke members ko shamil karke WhatsApp groups bana dete hain aur wahan abusive language post karte hain.
Phase 3: AI-Morphed Pornographic Collages. Teesre aur sabse khatarnak charan mein, scammers victim ki gallery se chori ki gayi normal selfies ya Aadhaar/PAN photo ko Artificial Intelligence deepfake tools aur basic Photoshop editing ke zariye nude bodies, pornography aur vulgar text ke sath morph karte hain. Is morphed photo ko victim ke WhatsApp par bhejkar ultimatum diya jata hai: '30 minute mein ₹10,000 bhejo, varna yeh photo tumhare sasural, boss aur Facebook par viral kar denge.'
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
3. Immediate Emergency Action: Filing on Cyber Crime Portal (cybercrime.gov.in) & 1930 Helpline
Yadi aap ya aapka koi parijana instant loan app ke cyber blackmail aur morphed photos ka shikar ho raha hai, toh panic mein aakar galat kadam uthane ya paise transfer karne ke bajaye Bharat Sarkar ke National Cyber Crime Reporting Portal aur Indian Cybercrime Coordination Centre (I4C) ke statutory mechanism ko turant activate karein.
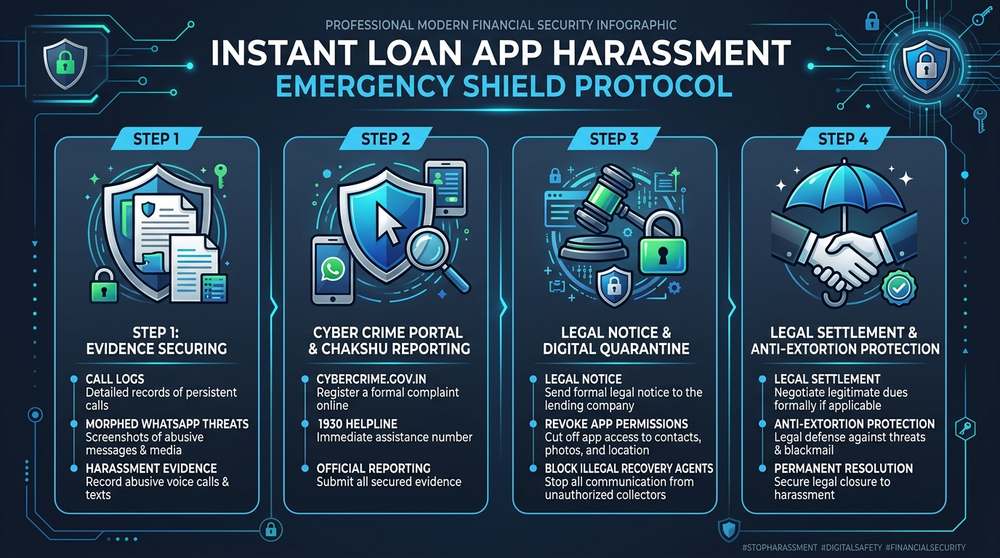
Niche diye gaye 4-step emergency protocol ko bina kisi vilamb ke follow karein:
Dial 1930 National Cyber Financial Helpline Immediately
Apne phone se turant 1930 dial karein. Agar aapne dar ke maare scammers ke kisi UPI handle ya bank account mein paise transfer kiye hain, toh 1930 helpline banking fraud network ke sath coordinate karke beneficiary bank account ko turant freeze (lien) karwa sakti hai, jisse paisa wapas milne ki sambhavna banti hai.
Preserve Unaltered Digital Forensics & Evidence
Krodh ya sharm mein aakar WhatsApp chats ko delete na karein. Threatening messages, audio voice notes, morphed images, payment demand QR codes aur call history ka date aur time ke sath full screenshot lein. WhatsApp chat ko 'Export Chat with Media' option ke zariye apne secure email par backup lein.
Lodge Formal Complaint on cybercrime.gov.in
Official portal cybercrime.gov.in par login karein. Yadi victim mahila hai ya morphed nude photos shamil hain, toh 'Report Cyber Crime against Women/Children' tab chunein jahan bina naam ujagar kiye anonymous complaint darj karne ka vikalp hota hai. Anya mamlon mein 'Report Other Cyber Crime' select karke Sub-Category mein 'Cyber Extortion / Blackmailing' chunein.
Secure the Cyber Acknowledgment Number & Police Cyber Cell Visit
Complaint submit karne par prapt 15-digit Cyber Crime Acknowledgment Receipt (PDF) ko download karein. Is acknowledgement copy ke sath apne local district Cyber Crime Police Station mein formal written application submit karke regular FIR (under BNS & IT Act) darj karwayen.
4. Chakshu & Sanchar Saathi Protocol: Blacklisting Suspect Numbers & RBI Sachet Filing
Cyber police station ke alawa Bharat Sarkar ke Department of Telecommunications (DoT) aur Reserve Bank of India (RBI) ne scam syndicates ke infrastructure ko disable karne ke liye do powerful national digital platforms launch kiye hain jinka upayog har victim ko anivarya roop se karna chahiye.
Platform 1: Chakshu on Sanchar Saathi Portal (sancharsaathi.gov.in). Chakshu facility aam nagrikon ko fraud SMS, WhatsApp threats aur unauthorized fake calling numbers ko sidhe telecom regulatory authority ko report karne ka adhikar deti hai. Portal par jakar category mein 'Fraudulent Communication related to Instant Loan Apps' chunein aur jis number se dhamki bhare message aaye hain, uska screenshot upload karein. DoT is complaint par 48 ghante ke andar suspicious SIM card ko pan-India deactivate kar deta hai aur us SIM se jude mobile handset ke IMEI ko central equipment identity register (CEIR) mein black-list kar deta hai.
Platform 2: RBI Sachet Portal (sachet.rbi.gov.in). Sachet portal Reserve Bank of India ka wo surveillance mechanism hai jo illegal, un-registered entities aur fake lending apps ke khilaf State Level Coordination Committee (SLCC) ko alert karta hai. Jab aap Sachet portal par fraudulent app ka naam, developer package ID aur transaction screenshots submit karte hain, toh RBI is data ko Ministry of Electronics and Information Technology (MeitY) aur Google Security Teams ko send karta hai, jisse us loan app ko Play Store aur Indian internet ecosystem se permanently ban karwaya jata hai.
Where faster digital quarantine and timely cybercrime.gov.in FIR registration reduce extortion leverage to zero by legally eliminating social blackmail power.
Instant Loan App Harassment: 4-Stage Emergency Shield Blueprint
6. Statutory Criminal Law Protections: Bharatiya Nyaya Sanhita (BNS), IT Act 2000 & RBI Master Rules
Aam borrowers ko kanoon ki jankari na hone ke kaaran loan recovery agents unhe darane mein safal ho jate hain. Bharat ka kanooni framework borrowers ko cyber extortion aur illegal recovery practices ke khilaf aakarshak aur majboot suraksha pradan karta hai. Scammers dwara kiye jane wale tamam aakraman Bharatiya Nyaya Sanhita (BNS) aur Information Technology Act, 2000 ke antargat non-bailable criminal offences hain:
1. Bharatiya Nyaya Sanhita (BNS) Section 308 (Extortion & Blackmail): Jab koi recovery agent morphed photo viral karne ya parivar ko badnaam karne ki dhamki dekar paise demand karta hai, toh yeh BNS Section 308 ke tehat seedhe extortion ka aparadh hai jismein 3 se 7 varsh tak ki kathor jail aur jurmane ka pravadhan hai.
2. BNS Section 351 & Section 356 (Criminal Intimidation & Defamation): Phone par gaali-galoch karna, jaan se marne ki dhamki dena ya contact list mein false derogatory messages circulate karna criminal intimidation aur criminal defamation ke antargat aate hain.
3. BNS Section 79 (Outraging the Modesty of Women): Yadi victim mahila hai aur uski photo ko obscene tareeqe se morph kiya gaya hai ya uske parivar ki mahilaon ko abusive calls kiye gaye hain, toh yeh non-bailable offence ban jata hai jismein police ko turant bina warrant ke arrest karne ka adhikar hota hai.
4. Information Technology Act, 2000 (Sections 66E, 67, and 43A): Section 66E ke tahat bina permission kisi vyakti ki privacy violate karke body images capture ya transmit karna punishable hai. Section 67 ke tahat electronic roop mein obscene content publish karne par 5 saal tak ki jail hoti hai. Section 43A ke tehat unauthorized data scraping ke liye heavy civil damages lagaye jate hain.
5. RBI Digital Lending Master Directions (2022/2024): Reserve Bank of India ke mandatory regulatory circulars ke anusaar, koi bhi regulated entity (Bank ya NBFC) borrower ke mobile contacts, media files, call logs ya biometric storage ko access nahi kar sakti. Loan disbursement aur recovery sirf borrower ke bank account mein direct transactions ke zariye hona chahiye bina kisi third-party aggregator ya shady recovery agents ke hastakshep ke.
7. Digital Quarantine & Contact Defense: How to Neutralize Social Stigmatization
Blackmailers ki sabse badi takat hoti hai victim ka 'Social Shame & Isolation'. Unka pura model is baat par depend karta hai ki victim sharm aur badnaami ke darr se chupchap paise deta rahega aur kisi ko batayega nahi. Is social leverage ko todne ke liye aapko turant ek strategic Contact Shield Broadcast execute karna chahiye.
Action 1: Immediate Social Media & WhatsApp Alert Status. Apne WhatsApp status, Facebook post aur family groups mein turant yeh sandesh broadcast karein:
English: "Important Security Notice: My mobile device was recently targeted by a malicious cyber phishing application that unlawfully scraped my contact directory. Unidentified international cyber extortionists are circulating morphed fake photos, abusive messages, and illegal monetary demands using virtual numbers. Please do not entertain, respond, or pay any money to these scammers. Report and block any such numbers immediately. A formal criminal complaint and FIR have been registered with the National Cyber Crime Reporting Portal (cybercrime.gov.in). Thank you for your support."
Hindi: "Zaroori Soochana: Mera phone ek cyber virus application dwara hack ho gaya tha jisse meri contact list chori ho gayi hai. Cyber apradhi fake morphed photos aur abusive messages bhejkar paise ki mang kar rahe hain. Kripya kisi bhi suspicious number ya sandesh par dhyan na dein aur na hi koi paisa transfer karein. Unhe turant block karein. Is mamle mein Cyber Crime Police aur cybercrime.gov.in par formal FIR darj kar di gayi hai."
Jab aapke tamam rishtedar, dosto aur colleagues ko pehle se pata chal jata hai ki yeh ek cyber fraud attack hai, toh blackmailers dwara call karne par wo unhe sidhe gaali dekar block kar dete hain. Scammers ko jaise hi ehsas hota hai ki victim dar nahi raha hai aur social circle alert ho chuka hai, unka blackmail model fail ho jata hai aur wo agle 24 se 48 ghante mein calls band karke naye targets ki taraf move ho jate hain.
Action 2: Device Hardening & Permission Revocation. Apne phone ki Settings > Apps > App Permissions mein jakar suspicious apps ki storage, camera, contacts aur location access disable karein. Rogue apps ko permanently uninstall karein aur device par ek certified mobile antivirus security scan run karein.
8. Differentiating RBI-Registered NBFC Apps vs Illegal Shell Apps: Forensics & Sanction Checks
Bharat mein do alag-alag categories ke digital lending apps operate karte hain, aur dono se nipatne ka kanooni tareeqa bilkul alag hota hai.
Category 1: Unregistered Chinese / Rogue 7-Day Shell Apps. Yeh apps (jaise CashAdvance, RupeeStar, FastLoan, SuperPocket aadi) kisi bhi Indian financial regulatory body ke sath registered nahi hoti hain. Inka loan tenure sirf 7 din ka hota hai aur weekly interest 100% se 300% tak hota hai. Inke paas koi legitimate loan agreement, Key Fact Statement (KFS), ya grievance officer nahi hota. Yeh apps CIBIL score par reporting nahi kar sakti hain aur inka ekmatra udeshya extortion hota hai. Inhe ek paisa bhi wapas na karein aur sidhe criminal FIR darj karein.
Category 2: RBI-Regulated NBFC / Fintech Platforms. Yeh platforms (jaise Navi, KreditBee, MoneyView, Paysense, LazyPay aadi) RBI ke sath registered NBFCs ke lending service providers (LSP) hote hain. Inka loan tenure minimum 3 se 24 mahine ka hota hai, proper sanction letter aur KFS provide kiya jata hai, aur repayments direct designated escrow bank accounts mein hoti hain.
Yadi kisi registered NBFC ka third-party collection agency agent aapko ya aapke contacts ko harass kar raha hai, toh use criminal blackmailer treat karne ke bajaye RBI Master Directions on Fair Practices Code ke tehat formal legal notice issue kiya jata hai. NBFC ke Principal Nodal Officer aur RBI Ombudsman ko evidence ke sath complain karne par agency ke khilaf strict penalties lagti hain aur borrower ko 40% se 60% tak ke discount par One-Time Settlement (OTS) pradan kiya jata hai.
9. Comparative Evaluation: Illegal Chinese Apps vs RBI-Regulated Digital NBFCs
Niche di gayi comparative matrix table aapko rogue 7-day instant loan apps aur authentic RBI-registered digital lenders ke beech ke kanooni status, extortion level, credit score impact aur recommended legal response ko spasht roop se darshati hai:
| Feature / Evaluation Factor | Illegal 7-Day Chinese Loan Apps | Unregistered P2P / Web APKs | RBI-Registered Fintech NBFCs |
|---|---|---|---|
| Regulatory Approval | None (100% Illegal Syndicate) | Unlicensed Private Lenders | Registered with Reserve Bank of India |
| Loan Tenure & APR | 6 to 7 Days (300%–500% APR) | 15 to 30 Days (60%–120% APR) | 3 to 36 Months (14%–36% APR) |
| Harassment & Blackmail | Morphed Nude Photos, Family Calls | Aggressive WhatsApp Spamming | Third-Party Calls (Regulated Hours Only) |
| CIBIL / Credit Bureau Impact | 0% (Cannot Report to Bureau) | 0% (No Bureau Access) | Reports Overdue Status (NPA on Default) |
| Court Litigation Standing | Zero Court Standing (Illegal) | Unenforceable Contracts | Can Issue Section 138 / CPC Notices |
| Recommended Legal Defence | Stop Payments + 1930 + Chakshu FIR | Cease & Desist Notice + Cyber Report | Advocate Reply + Nodal Officer + OTS Settlement |

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
Frequently Asked Questions: Instant Loan App Harassment & Legal Shielding
Instant loan app harassment se bachne ke liye sabse pehla emergency step kya hai?
Kya 7-day Chinese loan apps police FIR ya court case darj kar sakti hain?
Morphed photo blackmail hone par contact list ko kaise inform karein?
Cybercrime portal (cybercrime.gov.in) par loan app ki complaint kaise file karein?
Sanchar Saathi ke Chakshu portal par fraudulent numbers kaise report karein?
Kya fake instant loan apps mera CIBIL score kharab kar sakti hain?
Agar loan kisi RBI-registered NBFC app se liya hai aur recovery agent harass kar raha hai toh kya karein?
Recovery agents ke virtual international VoIP numbers ko kaise block karein?
Kya extorted loan amount ka bhugtan karna band karne se koi legal problem hogi?
SettleLoans legal desk cyber loan harassment victims ki kaise madad karti hai?
- National Cyber Crime Reporting Portal – Ministry of Home Affairs (MHA) & I4C
- Sanchar Saathi & Chakshu Portal – Department of Telecommunications (DoT) Fraud Reporting
- RBI Sachet Portal – Reserve Bank of India Surveillance against Unregistered Entities
- RBI Master Directions on Digital Lending Guidelines 2022/2024 & Fair Practices Code
- RBI Integrated Ombudsman Scheme – Online Portal for Banking & Digital Lending Grievances