- MSME Lending Focus: Indifi funds e-commerce sellers and cloud kitchens. The loans are unsecured and high-risk.
- Harassment Defense: Agent threats are illegal. A formal legal notice stops calls and workplace visits fast.
- Cancel NACH Bites: You can block auto-debits under NPCI rules. This prevents heavy bank return fees.
- Large Debt Waivers: Prove business loss to the lender. Secure up to a 60% principal discount legally.
- Binding Zero NDC: Under RBI guidelines, the lender must issue your No Dues Certificate in 30 days.
Digital Loans for Fast-Growing MSMEs
Indifi offers digital working capital. It targets online small businesses. Amazon sellers use it for stock. Cloud kitchens use it for daily ops. Travel agents use it for bookings.
These are unsecured business loans. They do not require hard collateral. The lender relies on your digital sales data. When sales dip, problems start.
Missing an EMI is a civil dispute. It falls under the Indian Contract Act. It is not a crime. Legal settlements are available.
When Revenue Contracts Sharply
Online sales can be volatile. Platform algorithms change. Orders dry up fast. Your daily cash flow takes a hit.
Then, your Indifi EMI bounces. The bank charges a return fee. Indifi adds late payment fines. The debt grows larger every month.
| Default Stage | Days Past Due | Lender Action | Legal Exposure | Settlement Offer |
|---|---|---|---|---|
| SMA-0 Stage | 1 – 30 Days | Automated calls and SMS alerts. | Minor score drop. No legal risk. | No discount yet. |
| SMA-1 Stage | 31 – 60 Days | Recovery agents start calling daily. | CIBIL drops further. Notices arrive. | Low. Only penal fee waiver. |
| SMA-2 Stage | 61 – 90 Days | Aggressive threats and fake notices. | Section 25 demand notices sent. | Moderate discount starts. |
| NPA Stage | 91 – 180 Days | Case moves to the legal desk. | Arbitration and Lok Adalat notices. | High. 40% to 50% waiver possible. |
| Write-Off Stage | 181+ Days | Account written off the books. | Court case filings. | Maximum. Up to 60% waiver possible. |
Once an account becomes an NPA, lenders prefer cash. A fast lump-sum payment ends the case. You earn a solid debt discount.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Stop Bank Bounce Penalties
Every bounced EMI hurts. Banks deduct ₹250 to ₹590 per failure. It drains your working capital fast.
You can block these auto-debits. Ask your bank to cancel the e-NACH mandate. NPCI rules allow this right. We help you wave off all bounce fees during settlement.
Indifi Settlement Slabs
Lenders hate long legal battles. They cost money. They lock up bank capital.
Lenders prefer a quick cash settlement over a multi-year court battle.
Expected Haircut Slabs for MSMEs
| Business Type | Default Duration | Penal Fee Waiver | Principal Discount | Final Offer Ratio |
|---|---|---|---|---|
| E-Commerce Seller | 90 – 180 Days | 100% Cleared | 35% to 45% | Pay 55% to 65% |
| E-Commerce Seller | 181+ Days | 100% Cleared | 50% to 60% | Pay 40% to 50% |
| Cloud Kitchen / Diner | 90 – 180 Days | 100% Cleared | 40% to 50% | Pay 50% to 60% |
| Cloud Kitchen / Diner | 181+ Days | 100% Cleared | 55% to 65% | Pay 35% to 45% |
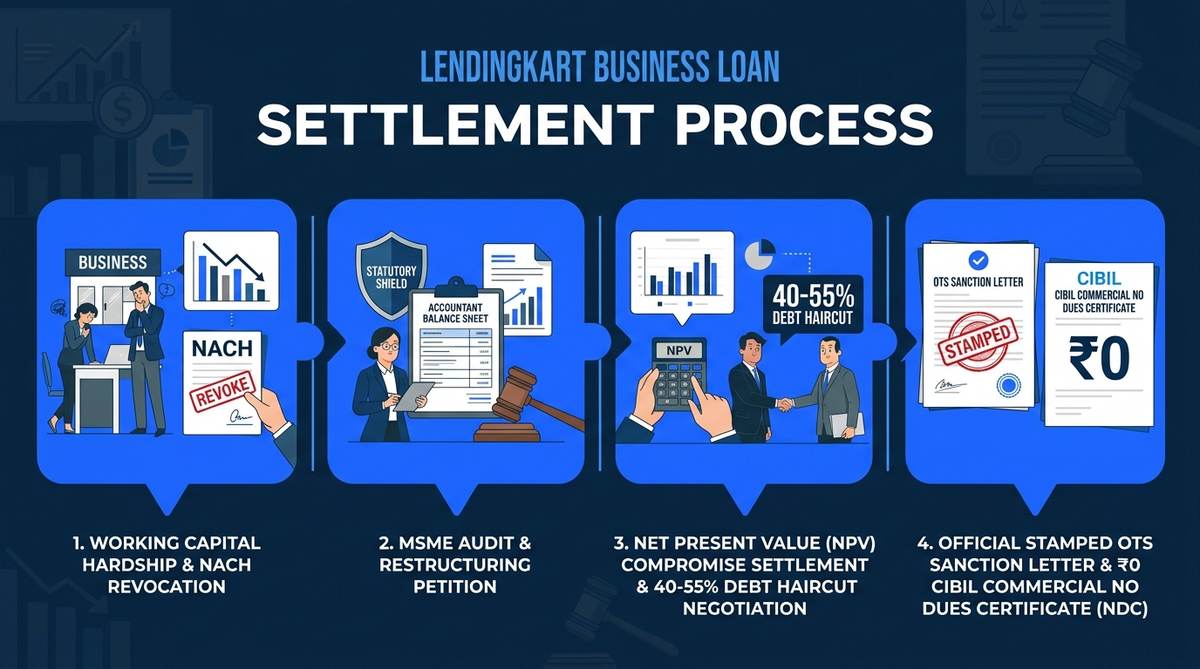
Indifi Business Loan Resolution Framework
Defending Against Recovery Abuse
Agents may call you fifty times a day. They send fake police notices on WhatsApp. They threaten to visit your shop.
This behavior violates RBI digital lending rules. Agents cannot use abusive language. They cannot call your contacts. A formal legal notice stops them immediately.
How to Settle Your Indifi Loan
Follow these simple steps for a legally binding debt settlement:
1Loan Document Audit
Check your sanction letter. Find the exact principal amount. Strip away all illegal late fees.
2Block Mandates & Harassment
Cancel the e-NACH mandate at your bank. Send a Cease and Desist notice to stop agent calls.
3Submit Hardship Proof
Show proof of business loss. Share dropping sales charts or medical bills. Request an official settlement.
4Negotiate The Haircut
Our team talks to the bank. We push for a 40% to 60% principal waiver.
5Verify The Sanction Letter
Review the official letterhead. Ensure all loan details are correct. Confirm the final discharge terms.
6Pay Directly & Get NDC
Pay the amount into the official bank account. Receive your No Dues Certificate within 30 days.
Managing Indifi Legal Action
After 90 days, lenders send Section 25 PSSA demand notices. These are warning letters, not arrest warrants. A lawyer can reply and defuse the situation.
Often, cases go to the National Lok Adalat. It is a legal fast-track court. Settlements here hold civil court power. You can easily secure a 50% discount.
| Resolution Path | Legal Framework | Typical Waiver | Timeline | Final Status |
|---|---|---|---|---|
| Direct Bank OTS | RBI Settlement Rules | 45% – 60% | 15 to 30 Days | Stamped ₹0 NDC. |
| Lok Adalat | Legal Services Act | 50% – 65% | Single Day | Civil Court Decree. |
| Arbitration Pushback | Arbitration Act | Turns to OTS. | 3 to 6 Months | Case dismissed safely. |
| Section 25 Defense | PSSA, 2007 | 40% – 50% | 2 to 4 Months | Notice withdrawn. |
Verify the Letter & Secure NDC
Beware of fake letters made by agents. Always demand a settlement letter on the official letterhead. Check the loan ID and final payment dates.
RBI rules force lenders to give you an NDC quickly. They have 30 days after full payment. If they fail, they owe you ₹5,000 every single day.
Fixing Your Business Credit Score
Settlement marks your CIBIL account as 'Settled'. The balance becomes ₹0. Your score drops at first. This is normal.
The settlement stops fresh default hits. Your legal risks vanish. You can rebuild your score over 18 months using small secured business cards.
How SettleLoans Defends MSMEs
We protect small businesses from aggressive collections. We send strong legal notices. We cancel costly auto-debits. We negotiate deep discounts with the lenders.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: Indifi Business Loan Settlement
Can Indifi business loans be settled legally?
Yes. Indifi business loans are unsecured. If you face genuine business losses, lenders offer legal One-Time Settlements (OTS). You can negotiate debt waivers up to 60%.
How can I stop daily collection calls from Indifi agents?
You can send a formal legal notice. RBI rules ban agents from harassing borrowers. A Cease and Desist letter stops the endless calls and WhatsApp threats quickly.
What happens when my Indifi loan EMI bounces?
Your bank charges a NACH bounce fee. Indifi also adds penal charges. The loan account goes into default. It hurts your business CIBIL score.
Can Indifi file a police FIR for loan default?
No. A business loan default is a civil matter. It is a breach of contract. Police do not register FIRs for unpaid loans. Arrest threats are totally illegal.
How do I cancel my Indifi e-NACH mandate?
You must inform your bank. Provide a written request to cancel the mandate. NPCI rules allow you to stop auto-debits to save bounce charges.
What is an Indifi Lok Adalat settlement?
Lok Adalat is a legal forum. It resolves civil disputes quickly. You can settle your Indifi loan here. The settlement acts as a binding civil court decree.
How much discount can I get on an Indifi loan settlement?
Discounts depend on the default age. If your loan is a Non-Performing Asset (NPA), you may get a 40% to 60% principal waiver. All late fees get removed.
Will an Indifi settlement ruin my MSME CIBIL score?
Yes, it lowers your score initially. The status shows as 'Settled'. However, it stops further legal action. You can rebuild your score later with secured credit.
Should I pay money to an Indifi recovery agent?
Never pay cash to agents. Do not send money to personal UPI IDs. Always pay directly into the official lender loan account. Keep solid proof.
When will I get my Indifi No Dues Certificate?
Lenders must issue the No Dues Certificate (NDC) within 30 days of full payment. This is an RBI rule. Delays lead to a penalty of ₹5,000 per day.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Guidelines on Digital Lending (RBI/2022-23/111 DOR.CRE.REC.66/21.07.001/2022-23)
- RBI Master Direction: Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Master Circular: Fair Practices Code for Non-Banking Financial Companies (NBFCs) &. Digital Lending Service Providers
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online CMS Portal for FinTech harassment, Excessive fines &. NDC Redressal
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987. National Lok Adalat settlement Framework