- Legal Settlement Rights. Loan default is a civil matter under the Indian Contract Act, 1872. You can settle under RBI rules.
- Protection for Parents. Section 60 CPC protects pensions and PF. Basic family pay is safe. RBI rules ban home visits.
- Remove Study Interest. Legal talks remove extra study interest. Waivers apply to the original loan sum.
- Realistic 40% to 60% Waivers. Unsecured NPA loans can get 40% to 60% principal waivers under RBI rules.
- Guaranteed ₹0 NDC Delivery. Under RBI rules (RBI/2023-24/60), Avanse must issue your NDC and return property papers in 30 days.
Understanding Avanse Financial Services
Avanse is a major student loan lender. They fund college degrees in India, the US, UK, Canada, Australia, and Europe. They offer unsecured loans up to ₹75 Lakhs and secured loans on property. These loans feature a study grace term plus a 6 to 12-month grace window.
Simple interest adds up during college years. When EMIs start, unpaid interest joins the principal balance. The total loan balance grows fast. A ₹40 Lakh loan can grow into ₹60 Lakh. Job loss or visa cuts make large EMIs hard to pay.
Default leads to bank bounce fees and penal interest of 24% to 36% per year. But default from job loss is a civil matter under the Indian Contract Act, 1872. Under RBI rules, you have the legal right to settle. You can get an official One-Time Settlement (OTS).
Shielding Co-Borrower Parents
Parents sign as co-signers on most Avanse loans. Under Section 128 of the Indian Contract Act, 1872, they share debt duty. If a student loses a job abroad, recovery agents often target parents in India with pressure calls. Civil law gives strong legal protection to parent co-signers. Section 60(1) of the Code of Civil Procedure, 1908 (CPC) shields family income and retirement funds: Pensions and PF are 100% safe from court attachment under Section 60(1)(g) and Section 60(1)(k) CPC. Under Section 60(1)(i) CPC, basic living funds and two-thirds of salary cannot be attached. Personal clothes, kitchen items. and house rental rights are legally protected. RBI rules ban calls before 8:00 AM or after 7:00 PM. Agents cannot visit offices or contact relatives. A Cease-and-Desist Notice to Avanse Nodal Officers stops abuse right away.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Avanse Loan Delinquency Lifecycle
Under Ind AS 109 rules and RBI norms, student loan defaults move through distinct stages. Each stage changes how Avanse manages the debt:
SMA-0 (1–30 DPD): Initial Dishonour
Automated reminders and return fees begin. The loan is standard. No settlement discounts apply yet.
SMA-1 (31–60 DPD): Escalated Collections
Collections teams call co-signer parents in India to demand payment and income proof.
SMA-2 (61–90 DPD): Pre-NPA Warning
Recovery agents get assigned. Field visits begin. Section 25 PSSA legal notices are sent.
NPA (90+ DPD): Non-Performing Asset
Interest stops adding to books. Avanse sets aside 15% to 25% cash reserves under ECL rules.
Doubtful / Loss Asset (180–365+ DPD)
Avanse sets aside up to 100% loss reserves. Stressed Asset teams now hold power to grant 40% to 60% debt cuts.
Setting aside reserves locks up lender capital. Sending a checked hardship petition after NPA status helps lawyers settle the largest debt cuts.
Avanse OTS Haircut Policy
Settlements with Avanse follow cash recovery models. Under RBI rules, Credit Committees evaluate settlement offers. They compare cash recovery against long court cases. To win a good settlement, remove all bounce charges and penal interest first. Then reverse added study interest. Calculate discounts on the original loan amount.
| Facility Type. | default Stage. | Penal & Bounce Waiver. | Principal Haircut Range. | Optimal Settlement Strategy. |
|---|---|---|---|---|
| Avanse Unsecured Overseas Student Loan. | 90 – 180 Days (NPA Stage 1). | 100% Full Waiver. | 30% – 45% Principal Waiver. | Offer 45%–55% of Net Disbursed Principal. |
| Avanse Unsecured Overseas Student Loan. | 180+ Days (Doubtful / Loss Asset). | 100% Full Waiver. | 45% – 60% Principal Waiver. | Offer 30%–40% of Total Book Dues. |
| Avanse Domestic Student Loan. | 90 – 180 Days (NPA). | 100% Full Waiver. | 35% – 50% Principal Waiver. | show Domestic Entry-Level Salary Gap. |
| Avanse Secured Loan (Property Collateral). | 180+ Days (SARFAESI Active). | 100% Penal Waiver. | 20% – 35% Principal Waiver. | Anchor Offer Above Property Distress Sale Net. |
Avanse Education Loan Settlement & Legal Defense Blueprint
Defending Legal Action
If defaults continue, Avanse may issue legal notices. Knowing your rights helps you build a strong defense. Section 25 PSSA Notices (NACH Bounces): This is a 15-day notice for failed auto-debits. Your lawyer sends a legal reply showing financial hardship. This stops police claims and starts OTS talks. Sole Arbitration Defense: Under Supreme Court rulings in Perkins Eastman and TRF Ltd, one-sided arbitrator choices are invalid. Your lawyer files Section 12(5) objections to halt actions. SARFAESI Act Property Defense: If you get a Section 13(2) notice, your lawyer files a Section 13(3A) objection. This pauses property auctions to allow time to settle.
ASection 25 PSSA Demand Notices (NACH Bounces)
This is a 15-day notice for failed auto-debits. Your lawyer sends a legal reply showing money hardship. This stops police claims and starts OTS talks.
BUnilateral Sole Arbitration Defense
Under Supreme Court rulings in Perkins Eastman and TRF Ltd., one-sided arbitrator choices are invalid. Your lawyer files Section 12(5) objections to halt actions.
CSARFAESI Act Property Defense (Secured Loans)
If you get a Section 13(2) notice, your lawyer files a Section 13(3A) objection. This pauses property auctions . This allows time to settle.
| Notice status. | Governing legal Act. | Mandatory Response Window. | Debtor Risk Level. | Strategic Counter-Defense. |
|---|---|---|---|---|
| NACH Mandate Dishonour. | Section 25 PSSA, 2007. | 15 Calendar Days. | Moderate (Quasi-Criminal). | Send formal hardship reply. Case duplicate claims. |
| Sole Arbitrator Appointment. | Arbitration & settlement Act, 1996. | 30 Calendar Days. | High (Ex-Parte Award Risk). | Invoke Perkins Eastman precedent. Disqualify arbitrator under Sec 12(5). |
| Collateral Demand Notice. | Section 13(2) SARFAESI Act, 2002. | 60 Calendar Days. | Critical (Property Auction Risk). | Submit Section 13(3A) objection. Propose formal OTS settlement. |
| Pre-Court Case Lok Adalat. | Legal Services Authorities Act, 1987. | Fixed Session Date. | Low (Consensual Forum). | Appear with counsel. Secure binding decree at deep discount. |
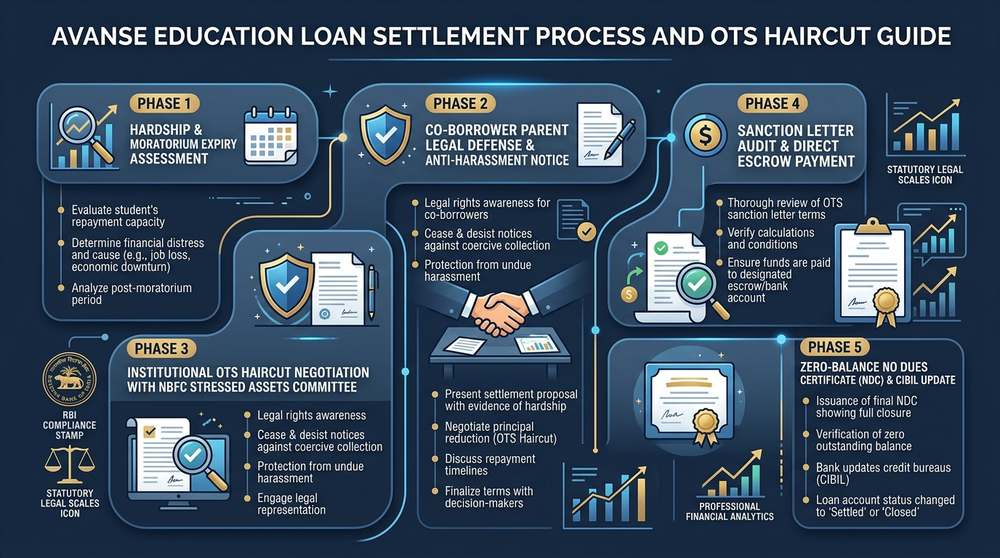
Step-by-Step Guide to an Institutional One-Time Settlement
1Ledger Forensic Audit & De-Capitalization
Get your full loan statement. Separate actual principal received from added study interest and late fines to set a clear baseline.
2Mandate Revocation & Parent Insulation
Cancel auto-debit payments at your bank under NPCI rules. Send a legal notice to Avanse to direct all calls only to your lawyer.
3Hardship Dossier Compilation
Collect job loss letters, visa papers, medical bills. And bank statements. Send a formal OTS request to Avanse's Stressed Assets team.
4Bilateral Credit Committee Negotiations
Your lawyers settle directly with credit managers. They show family money limits to win a 40% to 60% principal waiver.
5OTS Sanction Letter Forensic Verification
Review the settlement letter. Ensure it is on official Avanse letterhead confirming full balance waiver and closure of all legal actions.
6Direct Account Remittance & ₹0 NDC Delivery
Pay the agreed amount directly into the Avanse loan account. Avanse must deliver your No Dues Certificate and return property papers within 30 days.
OTS Sanction Letter Forensic Checklist
Always check your Avanse OTS Sanction Letter against four key points to avoid fraud:
Corporate Letterhead & CIN
Must be on official Avanse Money Services Limited letterhead with CIN and Mumbai registered office address.
Authorized Signatory & POA
Must be signed and stamped by an authorized Credit Committee officer holding Power of Attorney.
Full Balance Waiver Clause
Must clearly state that upon payment, all remaining balance, interest. And charges are completely closed.
Legal Proceedings Withdrawal
Must contain a clear term to withdraw all Section 25 PSSA notices, arbitration. And court filings unconditionally.
CIBIL Score Trajectory, Overseas Credit Isolation
Indian credit bureaus are separate from foreign bureaus. Under CICRA 2005, CIBIL defaults do not show on US, UK, or Canadian credit reports. A student loan default is a civil matter. It does not affect your student visa, OPT, or H-1B status. In India, the settlement marks the loan as "Settled" with a ₹0 balance. This stops further score damage. Get a secured credit card. Keep card spending under 25%. You can rebuild your score back above 750 in 18 to 24 months.
Institutional Debt Defense
SettleLoans represents student debtors and their parents in India. Our lawyers stop agent abuse and reply to legal notices. We negotiate 40% to 60% debt waivers under RBI rules.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: Avanse Education Loan Settlement & Legal Defense
What is the Avanse education loan settlement process and how does an NBFC compromise work?
How are co-borrower parents shielded when a student defaults on an Avanse loan after studying abroad?
How does compound interest during the study moratorium affect Avanse loan settlements?
What percentage of debt waiver or haircut can you realistically negotiate with Avanse Financial Services?
Can Avanse Financial Services file a criminal case or have the borrower arrested for student loan default?
How should borrowers handle Section 25 PSSA notices and arbitration notices sent by Avanse?
Does defaulting on an Avanse loan in India impact credit scores or employment in the US, UK, or Canada?
How are secured Avanse education loans resolved and property title deeds released?
Who within Avanse Financial Services has the legal authority to approve a loan settlement?
How long does Avanse take to issue the No Dues Certificate (NDC) after settlement payment?
Official Statutory & Regulatory References
- Reserve Bank of India (RBI): Master Direction – Settlement Settlements and Technical Write-offs Framework (RBI/2023-24/40).
- RBI Master Circular: Responsible Lending Conduct – Release of Movable/Immovable Property Documents on Repayment of Loans (RBI/2023-24/60).
- Avanse Money Services Limited: Fair Practices Code, Grievance Redressal Policy & Principal Nodal Officer Matrix.
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online Portal for Complaints on Recovery abuse, Illegal Mandate Sweeps & Document Delays.
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987. National Lok Adalat settlement Framework.