- Civil Contract Dispute: Defaulting on LiquiLoans P2P credit for EdTech or healthcare is a civil contract matter under the Indian Contract Act, 1872. It qualifies for One-Time Settlements (OTS).
- Halt Bounce Penalties: Canceling your e-NACH mandate stops repeat return fees. You can demand a 100% waiver of all penalty fees under RBI fair lending rules.
- Realistic 40% to 60% Haircut: Unsecured P2P loans carry no collateral. NDX P2P uses Net Present Value (NPV) recovery models to approve 40% to 60% debt discounts.
- Formal Legal Defense: You can counter Section 25 PSSA notices and single-arbitrator notices with legal replies. Many disputes settle at National Lok Adalat.
- Mandatory NDC Delivery: Under RBI Circular RBI/2023-24/60, NDX P2P must issue your No Dues Certificate within 30 days of settlement.
Understanding LiquiLoans
LiquiLoans is the brand name of NDX P2P Lending Technologies. It is an RBI-registered NBFC-P2P platform. It links borrowers with peer lenders for zero-cost EMI plans. These cover health bills and EdTech courses.
Borrowers sign a direct contract with NDX P2P. Job loss or health issues can cause loan defaults. NDX P2P treats this loan as a direct debt. It does not depend on course issues.
Loan default is a civil contract matter under the Indian Contract Act, 1872. You have the right to seek a compromise deal under RBI rules.
LiquiLoans Default Timeline
Unpaid LiquiLoans accounts follow RBI IRACP rules and the August 2024 P2P directions. In early stages (SMA-0 and SMA-1), calling systems send payment reminders.
After 90 days past due (DPD), the loan becomes an NPA. Peer lenders bear the credit risk. This leads LiquiLoans to recover cash quickly through compromise deals.
| Delinquency Stage. | Overdue Days (DPD). | Recovery Actions. | Legal Exposure. | Haircut Potential. |
|---|---|---|---|---|
| SMA-0 (Early Stage). | 1 – 30 Days. | Automated calls and repeat e-NACH debit attempts. | Zero legal risk. Initial bureau tracking begins. | Zero waiver. Full EMI payment required. |
| SMA-1 (Mid Stage). | 31 – 60 Days. | Phone calls and written reminder notices. | Formal demand warnings sent. Credit score drops. | Low waiver. Tenure changes or EMI pauses considered. |
| SMA-2 (Pre-NPA Stage). | 61 – 90 Days. | Agency assignment and formal loan recall notices. | Section 25 PSSA notices sent for failed debits. | Moderate waiver. Late fee waiver discussions start. |
| Substandard NPA. | 91 – 180 Days. | Transferred to Stressed Assets Desk. Loss reserves booked. | Magistrate Court notices under Sec 25 PSSA. Pre-litigation notices. | High (35% to 50% Haircut). |
| Written-Off Asset. | 181+ Days. | Written off in platform ledger. Full loss provisions made. | Digital arbitration or Lok Adalat summons. | Maximum (50% to 60% Haircut). |
Once a loan is overdue past 180 days, peer lenders absorb the accounting loss. A lump-sum OTS payment provides quick cash recovery, prompting NDX P2P to grant large debt discounts.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Stopping LiquiLoans NACH Bounce Penalty Loops
Repeated auto-debits drain bank accounts and add heavy bounce fees. NDX P2P systems make repeated NACH debit attempts. Each failed debit adds bank fees of ₹295 to ₹590. It also adds late fees and penal interest.
These extra fees inflate your balance unfairly. Under RBI Fair Lending rules (Circular RBI/2023-24/53), lenders cannot add penal charges to principal debt. They cannot charge compound interest on penalties.
You can cancel the e-NACH mandate through your bank under NPCI rules. During settlement talks, our team demands a 100% waiver of all bounce fees.
LiquiLoans Settlement Haircut Valuation
Under RBI Master Directions (DOR.STR.REC.20/21.04.048/2023-24), NDX P2P follows a clear settlement policy. EdTech and health loans have no collateral. The platform uses Net Present Value (NPV) models to judge offers.
LiquiLoans compares fast cash recovery against the high costs and long delays of civil court suits. An upfront settlement offer gives peer lenders the best cash return.
Where C_t is expected recovery cash, r is the discount rate, and deductions account for 2 to 4 years of legal delays and collection costs.
Realistic LiquiLoans Settlement Haircut Slabs by Product and Aging
| Credit Facility. | Delinquency Aging. | Fee Waiver. | Principal Haircut. | Target Settlement Offer. |
|---|---|---|---|---|
| EdTech Skilling Loan. | 90 – 180 Days (NPA). | 100% Full Waiver. | 35% to 45% Waiver. | Offer 45% to 55% of Dues. |
| EdTech Skilling Loan. | 181+ Days (Written Off). | 100% Full Waiver. | 45% to 60% Waiver. | Offer 35% to 40% of Dues. |
| Elective Healthcare EMI. | 90 – 180 Days (NPA). | 100% Full Waiver. | 30% to 45% Waiver. | Offer 45% to 55% of Dues. |
| Consumer Credit Line. | 180+ Days (Doubtful). | 100% Full Waiver. | 50% to 60% Waiver. | Offer 30% to 35% of Dues. |
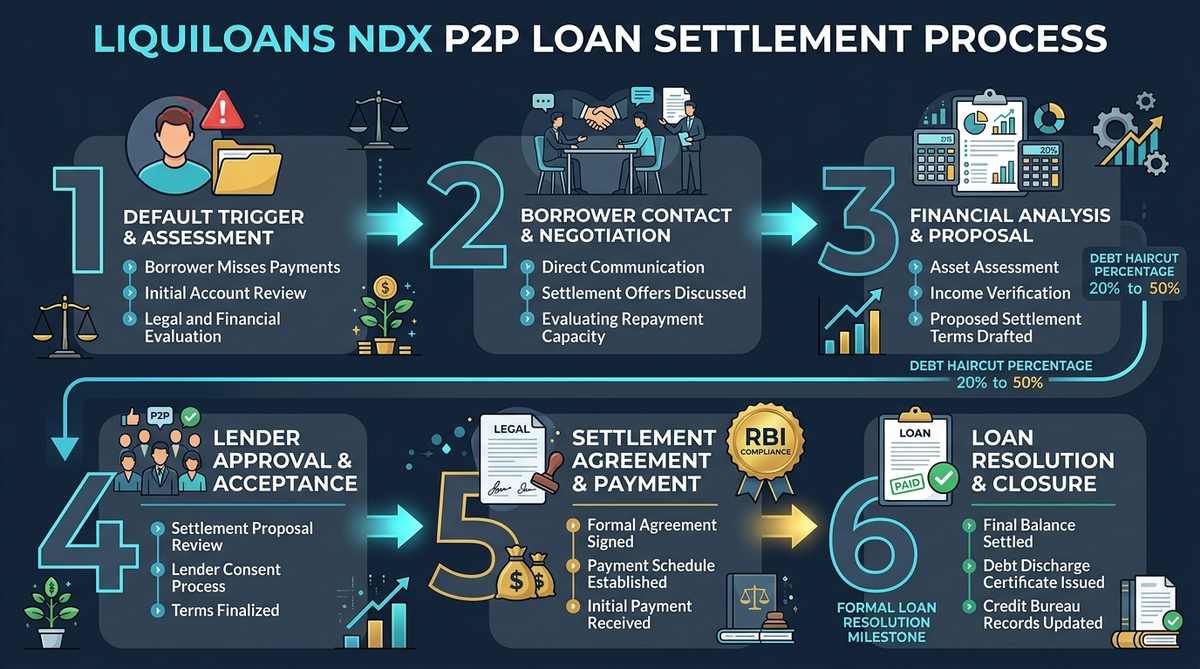
LiquiLoans (NDX P2P) Loan Settlement & Legal Resolution Blueprint
Defending Against Harassment Under RBI NBFC-P2P Rules
NDX P2P often hires third-party Debt Recovery Agencies (DRAs) to collect overdue loans. Tele-callers may call repeatedly, contact your friends, or message coworkers.
Under RBI Master Directions on Recovery Agents, strict rules protect borrowers. Agents cannot call before 8:00 AM or after 7:00 PM. They cannot contact family or visit your office without notice.
Save all call recordings and WhatsApp messages. A formal advocate notice to NDX P2P's Principal Nodal Officer stops harassment quickly. You can also file an RBI Ombudsman complaint.
Step-by-Step Guide to a Compromise Settlement with NDX P2P
Follow this 6-step roadmap to settle your LiquiLoans facility safely:
1Hardship Dossier & Service Failure Documentation
Gather proof of hardship. Include layoff letters, medical bills, or course cancellation records. This proves your default is non-wilful under RBI compromise guidelines.
2NACH Mandate Revocation & Counsel Notice
Cancel the e-NACH mandate via your bank to stop bounce fees. Send a written notice directing all collection calls to your advocate.
3Submitting Structured Compromise Petition
Submit a formal settlement petition directly to NDX P2P's Stressed Assets Desk. Start your opening settlement offer at 25% to 30% of total dues.
4Managing Counter-Demands & Haircut Approvals
Present proof of available lump-sum funds. Negotiate firmly with the Credit Committee to secure a 40% to 60% principal debt waiver.
5Forensic Verification of Stamped Sanction Letter
Review the written OTS letter carefully. Ensure it includes your loan account number, CIN (U67200MH2015PTC262114), agreed amount, and full-discharge terms.
6Direct Remittance & ₹0 NDC Enforcement
Pay the agreed sum directly into the NDX P2P loan account via RTGS or NEFT. Under RBI rules, NDX P2P must send your No Dues Certificate within 30 days.
Navigating LiquiLoans Sec 25 PSSA & Lok Adalat
A Section 25 PSSA notice gives you 15 days to reply. Your lawyer should explain your hardship and dispute unfair bounce fees. LiquiLoans may also start digital arbitration in Mumbai. Under Supreme Court rulings (Perkins Eastman and TRF Ltd.), unilateral arbitrator appointments are void ab initio. Your counsel can challenge the arbitrator under Sections 12 and 14 of the Arbitration Act.
NDX P2P also joins National Lok Adalat sessions held by the DLSA. Bank officers can approve 45% to 60% debt waivers here. Lok Adalat settlements end with a final Civil Court Decree with zero appeals.
| Resolution Channel. | Legal Mechanism. | Haircut Potential. | Timeline. | Enforceability. |
|---|---|---|---|---|
| Direct P2P OTS. | Compromise agreement under RBI rules. | 40% to 60% Debt Haircut. | 15 to 30 Days. | Binding private contract with ₹0 NDC. |
| National Lok Adalat. | Judicial conciliation before DLSA panel. | 45% to 60% Debt Haircut. | Single-day session. | Civil Court Decree (Zero appeal). |
| Arbitration Defense. | Contesting unilateral arbitrator jurisdiction. | Variable (Converts to OTS). | 3 to 8 Months. | Section 34 / 14 challenge. |
| Section 25 PSSA Defense. | Magistrate court compoundable defense. | 35% to 50% Debt Haircut. | 2 to 6 Months. | Formal case withdrawal upon payment. |
Authenticating LiquiLoans Settlement Sanction Letters
Never pay settlement money based on phone calls or WhatsApp chats. Your OTS sanction letter must come on official NDX P2P Lending Technologies letterhead. It must show CIN U67200MH2015PTC262114, Mumbai address, loan details, agreed amount, and official stamp.
Pay only into the official NDX P2P bank account. Under RBI Circular RBI/2023-24/60, NDX P2P must issue your No Dues Certificate within 30 days. Delays carry a penalty of ₹5,000 per day.
LiquiLoans CIBIL Score Trajectory & Score Recovery
Settling with NDX P2P marks your loan as 'Settled' with a ₹0 balance across CIBIL, Experian, Equifax, and CRIF High Mark. Your score may dip at first, but all default growth stops.
You can rebuild your credit score back above 750 within 18 to 24 months. Use secured credit cards, keep your credit usage under 25%, and pay all bills on time.
Why Distressed LiquiLoans Borrowers Trust SettleLoans
SettleLoans provides expert legal help for P2P loan defaults. We issue cease-and-desist notices to stop harassment. We handle Section 25 PSSA notices and arbitration claims. Our advocates negotiate directly with LiquiLoans for maximum debt waivers and verified ₹0 NDCs.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: LiquiLoans (NDX P2P) Loan Settlement
What is LiquiLoans and how does settlement work?
LiquiLoans is run by NDX P2P Lending Technologies, an RBI-registered NBFC-P2P. Under RBI rules, NDX P2P approves One-Time Settlements (OTS). Borrowers can get 40% to 60% debt waivers to close their loans.
Can zero-cost EMI loans for EdTech or healthcare be settled?
Yes. Zero-cost EMI loans for EdTech or healthcare are unsecured credit lines. Default is a civil contract dispute. You can settle these loans under RBI compromise rules.
How can borrowers stop repetitive LiquiLoans NACH bounce charges?
Ask your bank to cancel the e-NACH mandate under NPCI rules. This stops fresh charges. During settlement talks, demand a 100% waiver of all past bounce fees under RBI Fair Lending rules.
What debt haircut percentage can you negotiate on LiquiLoans defaults?
Borrowers can negotiate 40% to 60% principal waivers on loans overdue past 90 days (NPA). You can also get a 100% waiver on all late fees and penalty charges.
How to handle recovery agent harassment from LiquiLoans?
Under RBI rules, recovery agents cannot call before 8:00 AM or after 7:00 PM. They cannot call family or visit your workplace. You can send a legal notice and file an RBI Ombudsman complaint.
Can NDX P2P file a criminal case or arrest a borrower?
No. Loan default is a civil dispute under the Indian Contract Act, 1872. Police cannot arrest you or file an FIR for unpaid personal loans.
What is a Section 25 PSSA notice from LiquiLoans?
A Section 25 PSSA notice is a 15-day demand notice for a bounced auto-debit. Your lawyer should send a reply showing hardship and start settlement talks.
How long does NDX P2P take to issue the No Dues Certificate?
Under RBI Circular RBI/2023-24/60, NDX P2P must issue your No Dues Certificate within 30 days of payment. If they delay, they must pay ₹5,000 per day in compensation.
Official Regulatory References & Statutory Directives
- Reserve Bank of India (RBI): NBFC Peer to Peer Lending Directions, 2017 (Updated August 2024).
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements (DOR.STR.REC.20/21.04.048/2023-24).
- NDX P2P Lending Technologies: Fair Practices Code, Grievance Policy and Nodal Officer Matrix.
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Portal for Complaints on NBFC-P2P Harassment.
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987 — Lok Adalat Settlement Rules.