- Statutory Compromise Rights: Defaulting on an IIFL loan is a civil matter. Borrowers have the right to seek a legal One-Time Settlement (OTS) under RBI Master Directions.
- Gold Auction Shortfall Defense: If sold gold leaves an unpaid balance, it becomes an unsecured debt. You can settle it with a 50% to 75% waiver under Section 176 of the Indian Contract Act.
- Halting Compounding Penalties: Cancel your e-NACH mandate via your bank under NPCI rules. This stops extra fees. You can seek a 100% waiver on bounce charges under RBI rules.
- Defending Legal Notices: You can contest Section 25 PSSA notices and sole arbitrator notices in Mumbai. Resolve them through conciliation or Lok Adalat orders.
- Mandatory ₹0 NDC Guarantee: Under RBI Circular RBI/2023-24/60, IIFL must give you a No Dues Certificate within 30 days. They must pay ₹5,000 per day if they delay.
Understanding IIFL Finance's Multi-Product Architecture
IIFL Finance is an NBFC regulated by the RBI. It gives personal loans, MSME business loans, and gold loans. When you face job loss, income cuts, or medical bills, you may miss EMIs. IIFL then starts recovery steps. These include repeat NACH debit attempts, bounce fees, and extra interest.
Missing loan EMIs is purely a civil matter under the Indian Contract Act, 1872. Police cannot file criminal cases for genuine loan defaults. Under RBI Master Directions, you have the right to stop harassment. You can also waive penalty charges and settle your debt with the IIFL team.
IIFL Finance Delinquency Lifecycle
IIFL Finance tracks overdue loans using RBI IRACP norms and Ind AS 109 rules. When a loan is unpaid for 90 days, it turns into an NPA. IIFL must then set aside funds for bad debt. The lender then shifts focus from routine EMI calls to one-time debt settlements.
| Loan Stage | Overdue Days (DPD) | IIFL Action | Legal Steps | Settlement Waiver |
|---|---|---|---|---|
| SMA-0 (Early Default) | 1 – 30 Days | Automated reminder calls, text alerts, and repeat NACH debits. | No court action. Credit score tracking starts. | Low. IIFL asks for full EMI payment. |
| SMA-1 (Mid Default) | 31 – 60 Days | Frequent recovery calls and loan recall warning letters. | Legal warning notices sent. CIBIL score falls. | Low. Loan tenure change or EMI pause may be offered. |
| SMA-2 (Pre-NPA Stage) | 61 – 90 Days | Home visits by agents and loan recall notices. | Notices under Section 25 PSSA or Section 138 NI Act issued. | Fair. Lenders may agree to drop penalty fees. |
| NPA (Substandard Asset) | 91 – 180 Days | Case moves to the Zonal Stressed Assets Desk under Ind AS 109. | Magistrate Court summons under Sec 25 PSSA or conciliation letter. | High. 35% to 50% waiver possible. |
| Doubtful / Loss Asset | 181 – 365+ Days | Full funds set aside. Loan ready for bad debt write-off. | Arbitration notices, Order 37 CPC suits, or Lok Adalat summons. | Best. 50% to 60% waiver possible. |
When a loan is 180+ DPD, IIFL writes off the debt. An OTS payment gives them quick cash. This helps credit teams grant large loan waivers.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
How to Stop IIFL Finance Bounce Charges
Borrowers face heavy bank fees when IIFL presents NACH debits again and again. Each bounce causes bank charges and penalty fees. Under RBI Fair Lending Practice rules (2023), lenders cannot add extra charges to your principal debt.
You can stop these fees easily. Ask your bank to stop the e-NACH mandate under NPCI rules. During OTS talks, ask for a 100% waiver of all bounce fees. This ensures your discount applies straight to your main loan balance.
Resolving IIFL Gold Loan Auction Shortfall Notices
If you miss gold loan EMIs, IIFL sells the pledged gold in an auction. If the sale does not clear the full debt, IIFL sends demand letters. They claim this unpaid gap as an unsecured shortfall.
You have legal rights under Section 176 of the Indian Contract Act, 1872. The lender must give you clear notice before any auction. They must check gold purity and set fair market prices. If IIFL sold your gold too cheap, you can legally challenge the gap claim.
Since no gold remains, this shortfall is an unsecured debt. IIFL teams often settle these claims through an OTS. They approve 50% to 75% debt waivers with an official ₹0 No Dues Certificate.
IIFL Finance One-Time Settlement (OTS)
Under RBI Master Directions on Compromise Settlements (2023), IIFL tests OTS offers using Net Present Value (NPV). They compare fast cash today against slow, costly court cases.
Here C_t is the expected recovery money, r is the discount rate, and deductions cover court fees and locked NPA funds.
Realistic IIFL Finance Settlement Haircut Slabs by Product & Aging
| Loan Type | Overdue Time | Fee Waiver | Principal Discount | Best Target Offer |
|---|---|---|---|---|
| IIFL Personal Loan | 90 – 180 Days (NPA) | 100% Full Waiver | 30% – 45% Waiver | Offer 40%–50% of Total Dues |
| IIFL Personal Loan | 181 – 365+ Days (Doubtful) | 100% Full Waiver | 45% – 60% Waiver | Offer 35%–40% of Total Dues |
| IIFL MSME Business Loan | 90 – 180 Days (NPA) | 100% Full Waiver | 30% – 45% Waiver | Offer 45%–55% of Total Dues |
| IIFL MSME Business Loan | 180+ Days (Written Off) | 100% All Penalty Charges | 50% – 65% Waiver | Offer 30%–35% of Total Dues |
| IIFL Gold Auction Shortfall | Post-Auction Leftover Dues | 100% Penalty Waiver | 50% – 75% Waiver | Offer 25%–35% of Balance |
IIFL Finance Loan Settlement & Legal Defense Blueprint
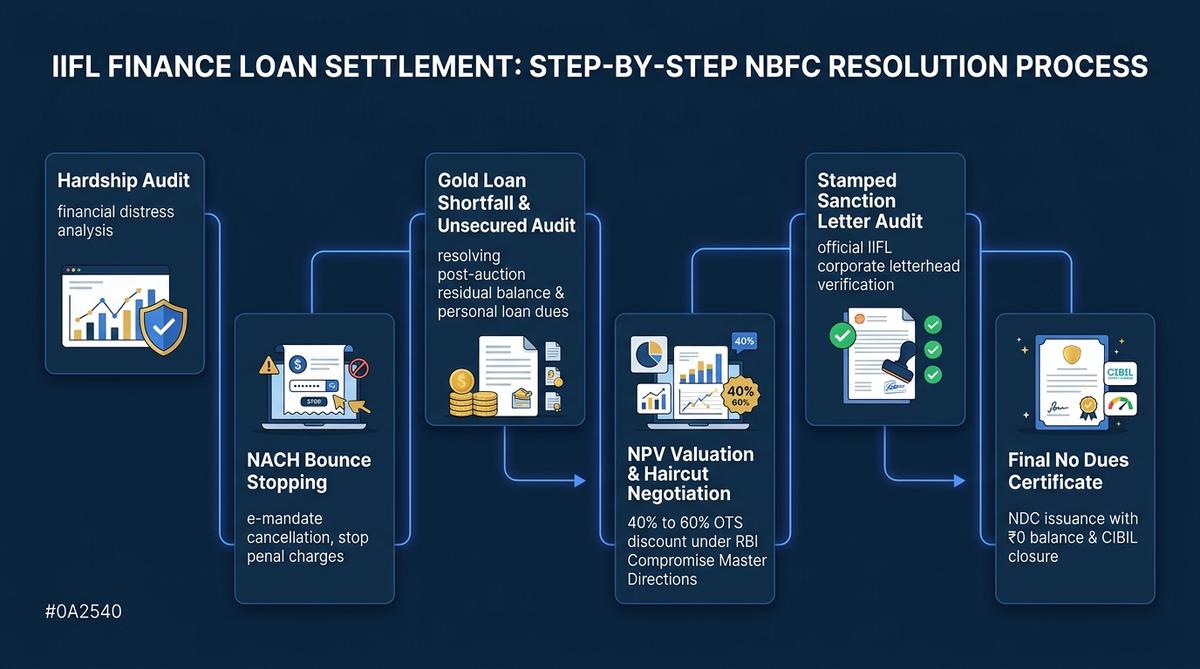
Defending Against Aggressive IIFL Recovery Tactics Under RBI
IIFL Finance hires third-party recovery agencies. These agents often push hard to meet monthly targets. But RBI Master Directions and Fair Practice Codes set clear rules. Agents can only call between 8:00 AM and 7:00 PM. They cannot call your family, boss, or friends. Workplace visits and threats are illegal.
Always save call recordings and abusive messages. Send a formal legal notice to the IIFL Principal Nodal Officer. You can also file a complaint on the RBI Integrated Ombudsman portal (CMS). This forces IIFL to resolve your loan through legal settlement talks.
Step-by-Step IIFL Finance Settlement Roadmap
Follow these 6 simple steps to settle your IIFL loan:
1Hardship Dossier Compilation & Ledger Audit
Collect proof of your financial crisis. Gather salary cut letters, medical bills, or business loss statements. This proves non-wilful default under RBI rules.
2Revoking NACH Mandates & Formalizing Communication
Cancel the e-NACH auto-debit with your bank to stop bounce charges. Shift all loan talks to written emails or your lawyer.
3Submitting Hardship Proposal to Stressed Assets Desk
Send a formal OTS letter to the IIFL Zonal Stressed Assets Desk. Cite RBI Master Directions and start with an offer of 25% to 35% of dues.
4Managing Counter-Offers & Credit Committee Approval
Handle counter-offers by showing limited family funds. Guide the Credit Committee to agree to a 40% to 60% principal waiver.
5Forensic Audit of the Official Sanction Letter
Check the settlement letter carefully. It must be on official IIFL letterhead with full loan details, agreed amount, and legal closure terms.
6Account Remittance & ₹0 NDC Enforcement
Pay the agreed amount directly to your IIFL loan account. Collect your official ₹0 No Dues Certificate within 30 days under RBI rules.
Navigating IIFL Sec 25 PSSA, Arbitration & Lok Adalat
After 60 to 90 days of default, IIFL may send legal notices under Section 25 of the Payment and Settlement Systems Act (PSSA). They may also send arbitration notices in Mumbai. Section 25 cases are compoundable matters. Your lawyer can reply by explaining your real financial hardship.
The Supreme Court in Perkins Eastman and TRF Ltd ruled that lenders cannot name sole arbitrators on their own. Your counsel can challenge the arbitrator under Section 12 and Section 14 of the Arbitration Act. This redirects your case to an OTS. Settling your matter in National Lok Adalat gives you a final Civil Court Decree with zero appeal risk.
| Option | Legal Path | Waiver Range | Time Needed | Final Legal Status |
|---|---|---|---|---|
| Direct NBFC OTS | Settlement pact under RBI Master Directions. | 40% – 60% Waiver | 15 to 30 Days | Private contract with ₹0 NDC. |
| National Lok Adalat | Court hearing before a judge and panel. | 45% – 60% Waiver | 1-day session | Civil Court Decree (No appeal). |
| Arbitration Defense | Contesting private hearings in far-off cities. | Variable (Converts to OTS) | 3 to 9 Months | Subject to Section 34 challenge. |
| Section 25 / 138 Defense | Legal defense in cheque and NACH bounce cases. | 35% – 50% Waiver | 2 to 6 Months | Case closed and dropped. |
Authenticating IIFL Finance OTS Sanction Letters
Always check your settlement letter carefully. It must come on official IIFL Finance Limited letterhead. It should show the Corporate Identification Number (CIN: L67100MH1995PLC093797), registered office address, unique reference number, and official seal. Never pay money on verbal promises or unverified links.
Under RBI Circular RBI/2023-24/60, IIFL Finance must issue your No Dues Certificate (NDC) within 30 days of full payment. They must also remove all security liens. If the lender delays, they must pay you ₹5,000 per day of delay.
IIFL Post-Settlement CIBIL Score Trajectory
After settlement, IIFL marks your loan across credit bureaus (CIBIL, Experian, Equifax, CRIF High Mark) as 'Settled' with an outstanding balance of ₹0. Your score may drop by 75 to 150 points initially. But all default interest and daily penalties stop permanently.
You can rebuild your credit score back to 750+ within 18 to 24 months. Use a fixed-deposit secured credit card (FD card). Keep your credit usage below 25%. Pay all utility bills and active EMIs on time every month.
Why Distressed IIFL Finance Borrowers Trust SettleLoans
SettleLoans stops recovery agent harassment with legal cease-and-desist notices. We audit gold loan auction shortfalls under Section 176. We defend Section 25 PSSA court notices and contest sole arbitration claims. Our team works directly with IIFL Zonal Stressed Assets teams to secure maximum debt waivers and genuine ₹0 No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs: IIFL Finance Loan Settlement
What is the IIFL Finance loan settlement process and how does an NBFC compromise work?
The IIFL Finance loan settlement process is a legal debt relief option under RBI rules. If you cannot pay your loan for over 90 days, your account becomes an NPA. You can then submit a hardship letter to IIFL. The bank team reviews your case and offers an OTS deal. Once you pay the agreed amount, IIFL closes your loan. You then get an official No Dues Certificate (NDC).
How should borrowers handle IIFL gold loan auction shortfall residual balance demand notices?
If auctioned gold does not cover your loan, IIFL demands the leftover balance. This balance is an unsecured debt. You can challenge this under Section 176 of the Indian Contract Act. Ask IIFL for auction records, gold weight proofs, and base price details. You can settle this residual debt through an OTS with a 50% to 75% waiver.
What percentage of debt waiver or OTS haircut can you realistically negotiate with IIFL Finance?
For personal and MSME loans, IIFL often gives 40% to 60% debt waivers. They also waive 100% of unpaid bounce fees and penal interest. If your loan is over 180 days past due, waivers can reach 50% to 75%.
How can borrowers stop IIFL Finance repeated NACH bounce penalties and auto-debit sweeps?
You can stop auto-debit bounce fees right away. Ask your bank to cancel your e-NACH mandate under NPCI rules. Tell IIFL to stop auto-debit sweeps. During settlement, ask for a full waiver of all bounce charges under RBI rules.
How do you protect against aggressive IIFL Finance recovery agents and collection harassment?
RBI rules protect borrowers from recovery agent abuse. Agents can only call between 8 AM and 7 PM. They cannot call your family, boss, or friends. If agents harass you, send a legal notice to the IIFL Nodal Officer. You can also file a complaint on the RBI CMS portal.
Can IIFL Finance file a criminal police case or arrest a borrower for loan default?
No. A loan default is a civil dispute under the Indian Contract Act, 1872. Police cannot arrest you for genuine financial default. Section 25 PSSA notices for bounced mandates go to court. You can easily settle these cases with legal help.
How should borrowers handle unilateral arbitration notices issued by IIFL Finance in Mumbai?
The Supreme Court ruled that lenders cannot pick sole arbitrators on their own. This was decided in the Perkins Eastman and TRF Ltd cases. Your lawyer can challenge the arbitrator under Section 12 and Section 14 of the Arbitration Act, 1996. This moves the case to an OTS.
Who within IIFL Finance holds the authorized delegation of powers to approve an OTS proposal?
Recovery agents and call center staff cannot approve debt discounts. Only IIFL Zonal Credit teams and Risk Officers can approve an OTS. Always demand a formal settlement letter on official IIFL letterhead.
How does settling an IIFL loan affect your CIBIL score and credit bureau history?
IIFL will mark your loan as 'Settled' with a zero balance on your CIBIL report. Your credit score may drop by 75 to 150 points at first. But all negative marks stop. You can rebuild your score back to 750+ within 18 to 24 months using secured credit cards.
What is the mandatory timeline for IIFL Finance to issue the No Dues Certificate (NDC) post-settlement?
Under RBI Circular RBI/2023-24/60, IIFL must issue your NDC within 30 days of full payment. They must also update your credit report. If they delay, they must pay you ₹5,000 for each day of delay.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Master Direction on Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Master Circular: Fair Practices Code for Non-Banking Financial Companies (NBFCs) & Gold Loan Auction Guidelines
- IIFL Finance Limited: Fair Practices Code, Customer Grievance Redressal Mechanism & Principal Nodal Officer Directory
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online Portal for Complaints on NBFC Recovery Harassment, Gold Auction Irregularities & NDC Delays
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987 — National Lok Adalat Conciliation Framework