- legal Compromise Framework: Defaulting on an Amex Platinum, Gold, or revolving credit card is a civil dispute under the Indian Contract Act, 1872. Cardholders have legal rights under RBI Master Directions to request a structured One-Time Settlement (OTS).
- Eliminating Predatory APR Levies: High finance charges of 42% to 52% APR plus 18% GST can be frozen. They are 100% waived during formal legal talks with American Express.
- Substantial 45%–60% Haircut: When an account passes 90 days past due, it becomes an NPA. Amex recalculates its recovery math. This allows deep cuts on the principal balance.
- Gurugram Legal Defense: Pre-litigation notices, Section 25 PSSA summons. And sole arbitrator notices can be challenged under Supreme Court rulings. Cases can be settled in Lok Adalat.
- Mandatory ₹0 NDC Guarantee: Under RBI Circular RBI/2023-24/60, Amex must issue a No Dues Certificate within 30 days. It must also update credit bureaus to a ₹0 balance.
American Express Banking Corp. India
American Express Banking Corp. (AEBC) is a foreign commercial bank licensed under Section 22 of the Banking Regulation Act, 1949. Its Indian headquarters, collections unit. And legal teams sit at DLF Cyber City in Gurugram, Haryana. Amex serves high-spending clients with Centurion, Platinum, and Gold cards.
Cardholders must understand the difference between Amex Charge Cards and Revolving Credit Cards. The Platinum Card and Gold Card are mostly Charge Cards. They have No Pre-set Spending Limit. You must pay the full balance every month. In contrast, cards like Membership Rewards and SmartEarn are revolving credit cards. They have fixed limits and allow paying a Minimum Amount Due.
When business losses or medical emergencies occur, charge card defaults happen fast. Since there is no revolving option, missing one bill blocks the card immediately. Amex then demands the full balance at once. However, all credit card debt is strictly unsecured civil debt under the Indian Contract Act, 1872. Borrowers can seek a lawful OTS under RBI guidelines.
The Anatomy of Amex Financial Escalation
Distressed debt on American Express cards grows rapidly due to high interest rates. Amex charges 3.5% to 4.25% per month. This equals 42% to 52.86% APR. In addition, an 18% GST applies on all interest and fees. This creates a fast adding debt trap.
Paying only the Minimum Amount Due keeps borrowers in debt for decades. On a ₹10 Lakh balance, around 80% of each payment goes toward interest and GST alone. It can take over 20 years to clear the debt this way. Missing a payment adds late fees up to ₹1,500 and removes all interest-free grace periods.
On Amex Charge Cards, non-payment triggers default interest from the date of each purchase. An original ₹15 Lakh spend can grow to ₹24 Lakhs within a year. During an OTS, a full ledger audit separates real spending from penal interest. Legal advocates demand a 100% waiver on all penalty charges.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
American Express Delinquency Lifecycle
American Express Banking Corp. follows RBI Prudential Norms for Asset status (IRACP). As an unpaid card account ages, the bank becomes much more willing to offer debt waivers.
The default process moves through five distinct stages:
Stage 1: Days Past Due 1 to 30 (Special Mention Account 0 - SMA-0)
Digital recovery starts at once. The cardholder receives calls, SMS. And email alerts. Card spending is paused. Amex pushes for full payments or EMI conversions.
Stage 2: Days Past Due 31 to 60 (SMA-1 Classification)
Card suspension becomes permanent. Internal phone collections begin. Late fees add up. And calls warn about CIBIL score drops. No principal cuts are given yet.
Stage 3: Days Past Due 61 to 90 (SMA-2 Classification)
The account is close to NPA status. Amex assigns field collection agencies. Preliminary legal notice letters arrive from Gurugram legal cells.
Stage 4: Days Past Due 91 to 180 (Sub-Standard Asset / NPA Classification)
Under RBI rules, the account becomes a defaulted Asset (NPA). Amex must set aside capital reserves for the bad debt. The file moves to the Stressed Assets Desk in Gurugram. This is the best window to negotiate 45% to 55% waivers.
Stage 5: Days Past Due 181 to 365+ (Doubtful / Loss Asset & Technical Write-Off)
The bank writes off the debt in its balance sheet. Amex may send court notices or move the case to National Lok Adalat. Debt waivers reach 55% to 65% with proof of hardship.
Amex NPV Recovery Valuation Modeling
Many cardholders believe debt settlements are random talks with phone callers. In reality, American Express evaluates settlements using financial math. Under RBI Master Directions, banks calculate the Net Present Value (NPV) of recovery. They compare an immediate cash payment against the cost of fighting a long court battle.
When an Amex card defaults, the bank estimates court delays of 3 to 7 years. It adds legal fees and the drag of locked capital under 100% NPA reserves. If a borrower offers an immediate lump sum that beats this net recovery value, the Amex Credit Committee approves a large waiver.
Where C_t is the expected recovery in year t. The letter r is the bank cost of funds. Long court delays and locked capital reduce returns. This makes an early cash settlement far better for the bank.
Realistic American Express Settlement Haircut Matrix by Card Product & Aging
| Amex Card Category. | default Aging. | Interest &. Fee Waiver. | Principal Haircut Range. | Target OTS Settlement. |
|---|---|---|---|---|
| Amex Platinum / Gold (Charge). | 90 to 180 Days (NPA). | 100% full waiver. | 35% to 50% principal cut. | Pay 45% to 55% of principal. |
| Amex Platinum / Gold (Charge). | 181 to 365+ Days (Loss Asset). | 100% full waiver. | 50% to 65% principal cut. | Pay 35% to 45% of principal. |
| Amex Revolving (Platinum Travel / MR). | 90 to 180 Days (NPA). | 100% penal interest waived. | 40% to 55% principal cut. | Pay 40% to 50% of total dues. |
| Amex Revolving (SmartEarn / Business). | 180+ Days (Written Off). | 100% penalty charges waived. | 55% to 65% principal cut. | Pay 30% to 40% of total dues. |
American Express Credit Card Settlement & Legal Resolution Blueprint
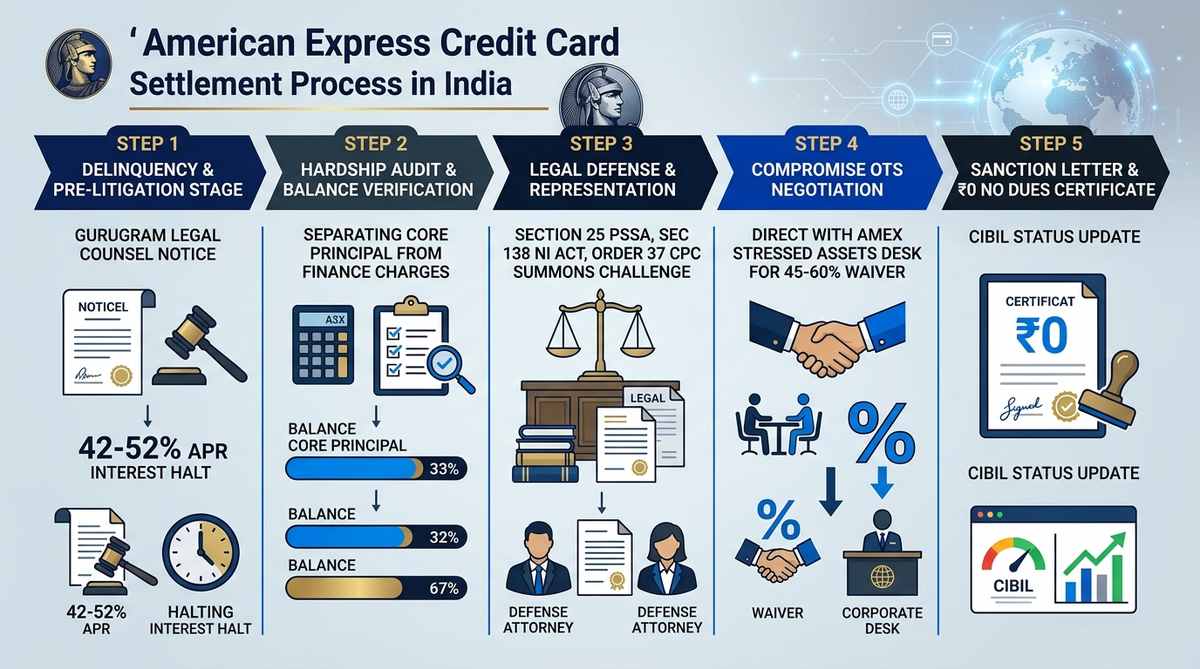
Demystifying Amex Gurugram Legal Notices
American Express manages all legal cases from Gurugram, Haryana. When an account becomes an NPA, cardholders across India receive legal notices from Amex empanelled law firms in Gurugram and New Delhi. These notices use formal legal terms to pressure borrowers.
The common legal actions started by Amex include:
1. Section 25 Payment and Settlement Systems Act (PSSA), 2007: When an auto-debit NACH bounces, Amex issues a 15-day notice under Section 25 PSSA. Like cheque bounce cases, this is a bailable and compoundable quasi-criminal matter. It is not an arrest warrant. Advocates file legal replies showing hardship and settle the case out of court.
2. Summary Recovery Suits under Order 37 of the Code of Civil Procedure (CPC), 1908: Amex may file summary suits in District Commercial Courts. The cardholder has 10 days to appear and apply for Leave to Defend. Legal counsel highlights valid disputes like unfair APR rates and penalty fees. The court grants leave to defend. This leads the bank to settle.
3. Section 138 Negotiable Instruments Act, 1881: If physical cheques bounce, Section 138 notices are sent. These cases are fully compoundable and get closed once the OTS is completed.
Challenging Unilateral Arbitration
Many Amex card agreements contain arbitration clauses in Delhi or Gurugram. Cardholders often receive letters stating that Amex has appointed a sole arbitrator. one-sided arbitrator appointments by lenders are legally invalid.
Under Supreme Court rulings in the Perkins Eastman and TRF Ltd cases, a lender cannot choose a sole arbitrator on its own. Advocates file objections under Section 12(5) of the Arbitration Act, 1996. This halts one-sided arbitration and brings Amex to the negotiation table.
Also, National Lok Adalats organized by NALSA offer a trusted forum to settle Amex dues. Settlements reached in Lok Adalat have the power of a Civil Court Decree under Section 21 of the Legal Services Authorities Act, 1987. No court fees apply. And the settlement is final.
Step-by-Step Amex Settlement Roadmap
Reaching a safe and cost-effective settlement with American Express requires a clear 5-step roadmap:
Collect past card statements. Separate the actual spent amount from interest, annual fees, late fees, and GST. This gives you your true settlement base.
Send a formal legal help to American Express and its Nodal Officer. Demand an immediate end to third-party calls to coworkers and family under RBI rules.
Send a formal hardship proposal to the Amex Stressed Assets team in Gurugram. Include proof like layoff letters, business losses, or medical bills.
Negotiate with Amex Zonal Credit Managers. Work down from low initial discounts to an approved 45% to 60% waiver based on account age.
Check the stamped settlement letter on official Amex letterhead before paying. Pay only into your official Amex card account through RTGS or NEFT.
Amex Sanction Letter Forensics & NDC
The biggest risk in card settlement is paying on verbal promises from recovery agents. Agents often make fake promises or treat your money as a partial payment. This keeps the loan active and growing.
Before paying, you must verify the sanction letter carefully:
- Official Corporate Letterhead: The letter must be on official American Express Banking Corp. letterhead with registered company details.
- Clear Card Details: It must show your 15-digit card number, your full name, the total dues, the agreed settlement amount. And payment dates.
- Full Discharge Clause: The letter must state that once paid, Amex closes all dues and withdraws all court notices and arbitration cases.
- Authorized Signature: The letter must carry the official stamp and signature of an authorized Amex Credit Officer.
Under RBI Circular RBI/2023-24/60, American Express must issue a No Dues Certificate (NDC) within 30 days of full payment. If Amex fails to issue it within 30 days, it must pay ₹5,000 per day of delay to the cardholder.
Post-Amex CIBIL Score Rehabilitation
Knowing how an OTS affects your credit score is vital. After a settlement, American Express reports the card as 'Settled&apos. with a ₹0 balance to CIBIL, Experian, Equifax, and CRIF.
A 'Settled&apos. mark causes an initial score drop of 75 to 150 points. But it gives big benefits: it stops rolling monthly default marks and clears all legal risk. You can rebuild your CIBIL score back above 750 in 18 to 24 months with simple steps:
| recovery Phase. | Target Timeline. | Primary Action Item. | Expected CIBIL Trajectory. |
|---|---|---|---|
| Phase 1: Zero Balance Audit. | Month 1 to 2. | Check that CIBIL and Experian show a ₹0 balance. | Score stabilizes around 580 to 620. |
| Phase 2: Secured Card Inception. | Month 3 to 6. | Open a fixed-deposit (FD) backed credit card. | Score climbs to 650 to 680. |
| Phase 3: Utilization Discipline. | Month 7 to 12. | Keep card spending below 25% of the limit. | Score crosses 700 to 720. |
| Phase 4: Prime Credit Restoration. | Month 13 to 24. | Pay all utility bills and EMIs on time. | Score reaches prime 750 to 780+. |

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
American Express Credit Card Settlement
What is the American Express credit card settlement process in India?
How does an Amex Charge Card default differ from a Revolving Credit Card default?
What percentage of debt waiver or haircut can you negotiate with American Express India?
How should cardholders handle legal notices from American Express legal counsel in Gurugram?
Can American Express file a criminal case or have a cardholder arrested for card default in India?
How do you stop aggressive recovery calls and workplace harassment from Amex collection agencies?
Can American Express unilaterally appoint a sole arbitrator to resolve credit card disputes?
Who within American Express Banking Corp. has the authority to sanction an OTS compromise?
How does an Amex credit card settlement impact your CIBIL score and credit report?
How long does American Express take to issue the No Dues Certificate (NDC) after settlement?
Official Statutory & Regulatory References
- Reserve Bank of India (RBI): Master Direction – Credit Card and Debit Card – Issuance and Conduct Directions, 2022 (Updated 2026)
- RBI Master Circular: Prudential Framework for Resolution of Stressed Assets and Compromise Settlements
- American Express Banking Corp. India: Grievance Redressal Policy, Most Important Terms &. Conditions (MITC) &. Nodal Officer Matrix
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online Complaint Portal for Card Harassment, Excessive Charges &. NDC Non-Compliance
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987. National Lok Adalat settlement Framework