- LSP Platform Setup: CRED is not a bank. You cannot settle in the app. You must talk directly to IDFC FIRST, Newtap, or L&T Finance.
- Stop Extra Fees: Cancel your e-NACH mandate at your bank to stop bounce charges. Legal steps remove 100% of penal interest under RBI rules.
- Big 40% to 60% Waivers: After 90 days of default (NPA), banks prefer quick cash settlement over slow court recovery.
- RBI Anti-Harassment Rules: Agents cannot call your office coworkers, friends, or family. They cannot call before 8 AM or after 7 PM.
- Guaranteed ₹0 NDC Delivery: Under RBI Circular RBI/2023-24/60, lenders must give your No Dues Certificate within 30 days of full payment.
Deconstructing CRED Cash
CRED Cash offers quick personal credit lines to borrowers with CIBIL scores over 750. But CRED does not lend its own money. Under RBI Digital Lending Guidelines (2022), CRED is only a digital loan agent (LSP).
The actual funds come from regulated partner institutions:
1. IDFC FIRST Bank Limited: Provides large personal loans to salaried corporate staff.
2. Newtap Finance Private Limited: CRED's own NBFC unit that manages credit lines.
3. L&T Finance Limited & Partner NBFCs: Financial partners like KrazyBee Services and LiquiLoans that co-lend credit.
If you miss payments, the CRED app cannot help you settle. App chat systems only ask for full dues. To get a true One-Time Settlement (OTS) with deep fee cuts, you must speak directly to the actual lender.
CRED Cash Delinquency Lifecycle
Defaulted CRED Cash loans move through set stages under RBI IRACP rules and Ind AS 109 norms. Early default brings automated alerts. Once overdue past 90 days, the loan becomes a Non-Performing Asset (NPA). At that point, the bank shifts from simple collection to loss recovery.
| Delinquency Bucket | Days Past Due (DPD) | Lender & Platform Actions | Legal & Judicial Exposure | Settlement Haircut Window |
|---|---|---|---|---|
| SMA-0 (Initial Default) | 1 – 30 Days | App alerts, automated phone calls, and daily e-NACH debit tries. | No legal action yet. Initial 30-DPD mark on credit file. | Low. Bank asks for full EMI payment. |
| SMA-1 (Mid Delinquency) | 31 – 60 Days | Handed to call centers. Constant SMS and WhatsApp messages. | Formal warning notices sent. CIBIL score drops 50 to 90 points. | Low. Bank may offer small tenure changes. |
| SMA-2 (Pre-NPA Escalation) | 61 – 90 Days | Field recovery team assigned. Home and office visits planned. | Legal 15-day demand notice under Section 25 PSSA. | Medium. Discussions on penal interest waivers begin. |
| NPA (Substandard Asset) | 91 – 180 Days | Moved to Stressed Assets team. Bank sets aside 15% to 25% capital. | Court summons under Section 25 PSSA or Lok Adalat notices. | High (35% to 50% Principal Haircut). |
| Doubtful / Loss Asset | 181 – 365+ Days | Technical write-off under Ind AS 109 rules. 50% to 100% loss booked. | Arbitration notices and civil suits filed. | Maximum (50% to 60% Total Haircut). |
After 180 days, the lender books the loss on its balance sheet. A single cash payment helps them recover money fast. This allows them to offer large principal cuts.
Check Your Loan Settlement Options
Answer 2 quick questions to evaluate your settlement eligibility.
1. What type of loan do you want to settle?
Stopping Predatory e-NACH Presentations
When you miss a CRED Cash EMI, automated systems present your e-NACH mandate up to 4 times a month. Each failed debit brings heavy double fees. Your bank charges ₹250 to ₹500 plus GST. The lender also adds ₹500 to ₹1,000 plus GST in bounce fines. Penal interest of 24% to 36% per year gets added on top.
Under RBI Fair Lending Practices rules (2023), lenders cannot add extra interest on penalty charges. You can stop these charges in two simple steps:
First, tell your bank in writing or online to cancel the e-NACH mandate under NPCI rules. Second, during formal OTS talks, have your advocate demand a 100% waiver of all bounce fees and penal interest.
Partner Bank OTS Haircut Valuation
Under RBI compromise rules, partner banks assess settlement offers using Net Present Value (NPV) recovery math. Personal credit lines have no physical collateral. So lenders compare quick settlement cash against long court battles, lawyer costs, and bad-loan provisioning loss.
Here C_t is future money recovered and r is the discount rate. Deductions cover court delays, legal fees, and locked capital.
Realistic CRED Cash Settlement Haircut Slabs by Partner Entity & Aging
| Underwriting Partner Entity | Delinquency Aging Category | Penal & Bounce Waiver | Principal Haircut Range | Target Settlement Benchmark |
|---|---|---|---|---|
| IDFC FIRST Bank (CRED Cash) | 90 – 180 Days (NPA) | 100% Full Waiver | 30% – 45% Principal Waiver | Pay 45%–55% of Core Principal |
| IDFC FIRST Bank (CRED Cash) | 181 – 365+ Days (Written Off) | 100% Full Waiver | 45% – 60% Principal Waiver | Pay 35%–40% of Core Principal |
| Newtap Finance (Captive NBFC) | 90 – 180 Days (NPA) | 100% Full Waiver | 35% – 50% Principal Waiver | Pay 40%–50% of Core Dues |
| Newtap Finance (Captive NBFC) | 180+ Days (Doubtful Asset) | 100% Full Waiver | 50% – 65% Principal Waiver | Pay 30%–35% of Total Book Dues |
| L&T Finance / KrazyBee | 120+ Days (Substandard/NPA) | 100% Full Waiver | 40% – 55% Principal Waiver | Pay 35%–45% of Utilized Principal |
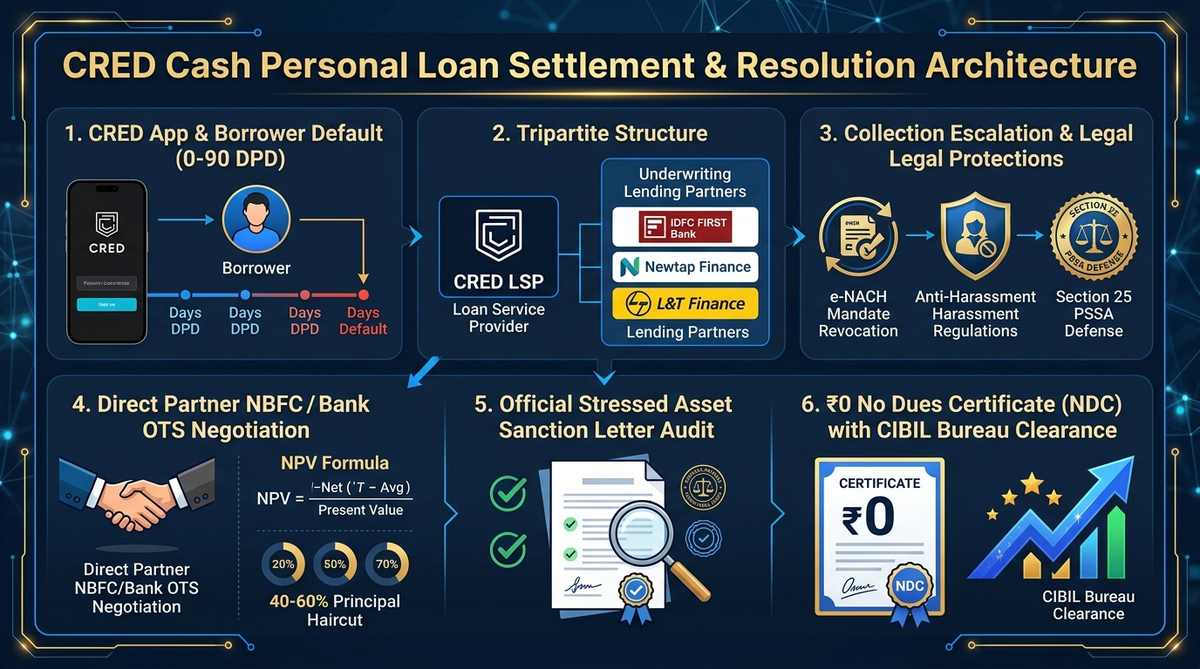
CRED Cash Personal Loan Settlement & Partner Bank Resolution Architecture
Halting CRED Cash Harassment Under RBI Directives
Many collection agencies use harsh pressure tactics. They call your office phone, contact coworkers on social networks, and threaten home visits.
RBI rules strictly ban these actions: (a) Agents cannot contact employers or references; (b) Calls are allowed only between 8:00 AM and 7:00 PM; (c) Threats, abuse, and fake police claims are strict regulatory offenses.
Sending a legal cease-and-desist letter to the bank's Nodal Officer stops agency calls quickly. You can also file a complaint on the RBI Ombudsman portal (CMS).
Step-by-Step Guide to CRED Cash Settlement
Follow these clear legal steps to settle your CRED Cash loan safely:
1Identify the Underwriting Regulated Entity & Loan Number
Check your loan letter or credit report. Find whether your loan is with IDFC FIRST Bank, Newtap Finance, or L&T Finance. Note down your loan account number.
2Revoke e-NACH Mandates & Formalize Communication
Stop auto-debit payments at your bank to avoid extra bounce fees. Inform the lender in writing to route all notices through your legal counsel.
3Submit Formal Hardship Petition to Stressed Assets Desk
Gather proof of hardship like job loss letters, salary cuts, or hospital bills. Send an OTS request directly to the partner bank's stressed asset desk.
4Negotiate Committee-Level Principal Haircut
Reject initial low-discount offers with proof of low income. Negotiate directly with credit managers for a 40% to 60% principal waiver.
5Forensic Verification of the OTS Sanction Letter
Review the settlement letter carefully. Ensure it is on the partner bank's official letterhead with loan details, amount, due date, and debt release terms.
6Direct Account Remittance & Secure ₹0 NDC
Pay the agreed settlement amount directly to the bank via RTGS or NEFT. The lender must issue your No Dues Certificate within 30 days under RBI rules.
Sec 25 PSSA & Lok Adalat Defense for CRED Cash
After 60 to 90 days of default, lenders may send 15-day statutory notices under Section 25 of the Payment and Settlement Systems Act (PSSA) for bounced auto-debits. They may also start sole arbitration in distant cities.
A Section 25 PSSA notice is only a demand notice, not a police warrant. A quick legal reply showing financial hardship keeps you safe and opens settlement talks. Under Supreme Court rulings in Perkins Eastman and TRF Ltd, unilateral arbitrator appointments are invalid under Sections 12 and 14 of the Arbitration Act.
Lenders also settle cases at the National Lok Adalat under the Legal Services Authorities Act, 1987. An award passed in Lok Adalat has the force of a final Civil Court Decree. No one can appeal it.
| Dispute Resolution Channel | Governing Legal Mechanism | Haircut Potential | Resolution Timeline | Judicial Finality |
|---|---|---|---|---|
| Direct Partner Bank OTS | Compromise pact under RBI Master Directions. | 40% to 60% Debt Haircut | 15 to 30 Days | Private deal with ₹0 NDC. |
| National Lok Adalat | Judicial talks before a sitting judge and bench. | 45% to 60% Debt Haircut | Single-day session | Civil Court Decree (No appeals). |
| Arbitration Challenge | Challenging unfair sole-arbitrator choice. | Variable (Leads to OTS) | 3 to 8 Months | Stayed under Perkins Eastman rule. |
| Section 25 PSSA Defense | Magistrate court compoundable legal defense. | 35% to 50% Debt Haircut | 2 to 6 Months | Case closed upon settlement payment. |
Authenticating CRED Cash OTS Sanction Letters
Never pay money based on phone calls or WhatsApp chats from recovery agents. An authentic OTS letter must come on the lender's official corporate letterhead (such as IDFC FIRST Bank, Newtap Finance, or L&T Finance). It must list the company CIN, office address, exact loan number, agreed amount, and full debt release terms.
Under RBI Circular RBI/2023-24/60, the lender must issue the No Dues Certificate and update credit bureaus within 30 days. If they delay, they must pay you ₹5,000 for each day of delay.
Post-Settlement CIBIL Recovery for CRED Cash
Settling your loan marks the account as 'Settled' with an outstanding balance of ₹0. This causes a short-term drop in your score. But it permanently stops ongoing default remarks and legal risks.
You can raise your score back above 750 in 18 to 24 months. Use a secured fixed-deposit credit card (FD card), keep card use below 25%, and make all payments on time.
Why Distressed CRED Cash Borrowers Trust SettleLoans
SettleLoans stops collection harassment through legal notices. We handle Section 25 PSSA notices and challenge unfair arbitration. We negotiate directly with IDFC FIRST Bank, Newtap Finance, and L&T Finance to secure large debt cuts and genuine No Dues Certificates.

Settle Loan is India's trusted debt relief and loan settlement platform. We help borrowers overcome financial distress by negotiating with banks and NBFCs to legally settle personal loans and credit card debts. With our transparent, performance-based approach, you can achieve debt freedom and regain your financial peace of mind.
COMPUTER
FAQs on CRED Cash Loan Settlement & RBI Rules
Can I settle a CRED Cash personal loan directly inside the CRED mobile app?
No. CRED is only a digital loan platform (LSP). It does not lend its own funds. You must settle directly with the partner bank or NBFC. This includes lenders like IDFC FIRST Bank, Newtap Finance, or L&T Finance.
Who are the primary lending partners underwriting CRED Cash loans in India?
RBI-regulated lenders provide all CRED Cash loans. Main partners are IDFC FIRST Bank, Newtap Finance, L&T Finance, and KrazyBee Services. Your sanction letter and CIBIL report name your exact lender.
How can borrowers stop continuous e-NACH auto-debit bounce fees on CRED Cash defaults?
Ask your bank to cancel the e-NACH auto-debit mandate under NPCI rules. Send a written notice to the lender as well. During settlement talks, ask for a 100% waiver on bounce fees under RBI rules.
What percentage of debt waiver or haircut can be negotiated on a defaulted CRED Cash loan?
Loans overdue by more than 90 to 180 days can get a 40% to 60% principal waiver. Lenders also drop 100% of unpaid late fees and penal interest.
How do you defend against recovery agents calling workplace colleagues or visiting home for CRED Cash dues?
RBI rules bar agents from calling coworkers, friends, or family. Agents cannot call outside 8 AM to 7 PM. Send a cease-and-desist letter to the bank's Nodal Officer and complain to the RBI Ombudsman.
Can the partner bank file a police FIR or arrest me for defaulting on a CRED Cash loan?
No. Default on an unsecured personal loan is a civil matter. The police cannot file an FIR or arrest you for loan defaults due to money problems.
What should you do upon receiving a Section 25 PSSA notice for a bounced CRED Cash payment?
A Section 25 PSSA notice gives you 15 days to act. Hire an advocate to send a formal legal reply. State your genuine money hardship and request a mutual settlement or Lok Adalat session.
How does settling a CRED Cash loan impact your CIBIL score and credit history?
The lender marks the loan as 'Settled' with a ₹0 balance. Your score drops at first. But you can rebuild your score past 750 in 18 to 24 months with a secured credit card.
How do you verify if a CRED Cash settlement sanction letter is genuine and authentic?
Make sure the letter is on the official letterhead of the partner bank or NBFC. Check for company CIN, correct loan number, agreed settlement amount, payment dates, and full debt release terms.
What is the statutory timeline for receiving the No Dues Certificate (NDC) after settlement?
Under RBI Circular RBI/2023-24/60, lenders must give you the No Dues Certificate within 30 days. They must also update credit bureaus. Late delays carry a penalty of ₹5,000 per day payable to you.
Official Regulatory References & Statutory Circulars
- Reserve Bank of India (RBI): Guidelines on Digital Lending (DOR.CRE.REC.66/21.07.001/2022-23) — Lending Service Providers (LSP) & Digital Lending Apps (DLA)
- RBI Master Direction: Compromise Settlements and Technical Write-offs (DOR.STR.REC.20/21.04.048/2023-24)
- RBI Circular: Fair Lending Practice - Penal Charges in Loan Accounts & Release of Movable/Immovable Property Documents (RBI/2023-24/60)
- Reserve Bank - Integrated Ombudsman Scheme, 2021: Online Grievance Redressal Mechanism for Unlawful Recovery Harassment & Excessive NACH Penalties
- National Legal Services Authority (NALSA): Legal Services Authorities Act, 1987 — National Lok Adalat Pre-Litigation Conciliation Framework